Daily Pulse · · 11:00 CET · 6 min read · market · FLOT
In this edition
Pattern alerts
- FLOT floating-rate-plus-3.2-ytd-rates-up-regime BULLISH
- TLT long-treasuries-minus-8.4-ytd-10y-5.28 BEARISH
- ZROZ zero-coupon-minus-64.7-from-2020-high WARNING
Every few years someone declares the 60/40 portfolio dead — 60% stocks, 40% bonds. After 2022 the case looked closed: stocks and bonds fell together, and the 40% that was supposed to cushion the fall made it worse. But look at what actually broke. It was not the idea of holding bonds next to stocks. It was the habit of holding the same bonds in every regime — usually long-dated Treasuries — as if the bond half needed no decision.
Nobody runs the stock half that way. Investors move between tech and value, growth and defensives, depending on rates, growth and inflation. The bond half needs the same regime call. Long bonds are the right tool in one regime and the wrong one in another, and there are instruments built for exactly the regimes where long bonds fail.
Four regimes, four different winners
We split the years since January 2020 into the rate regimes the market went through and measured the main bond tools in each — total return, distributions reinvested, from monthly closes. The pattern is plain: every regime had a different winner.
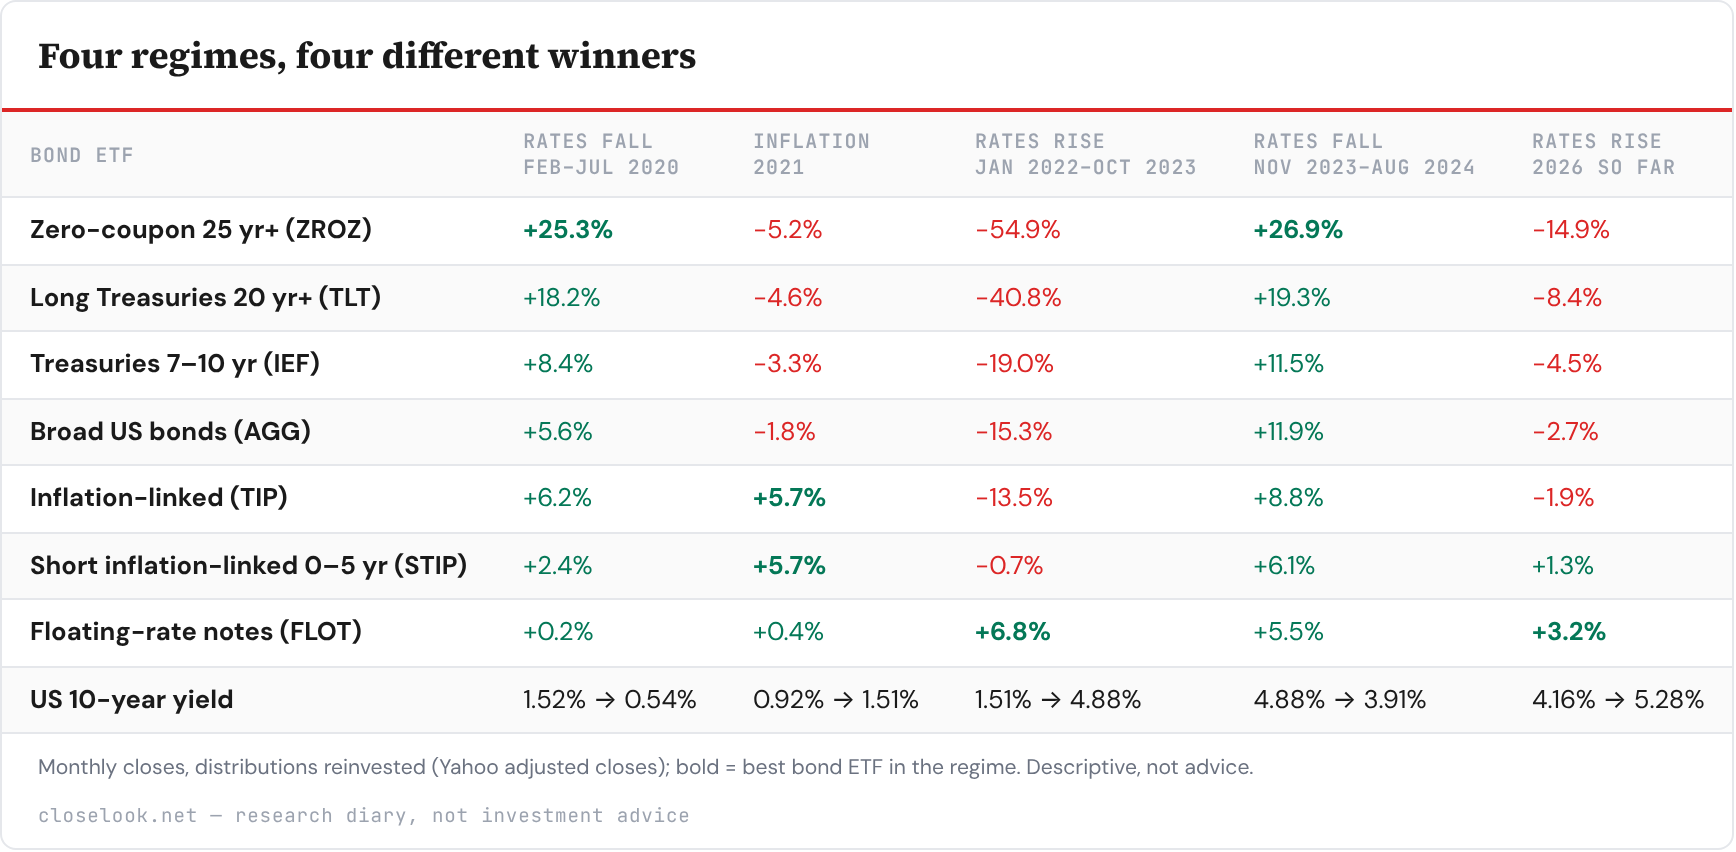
Table as text
| Bond ETF | Rates fall Feb–Jul 2020 | Inflation 2021 | Rates rise Jan 2022–Oct 2023 | Rates fall Nov 2023–Aug 2024 | Rates rise 2026 so far |
|---|---|---|---|---|---|
| Zero-coupon 25 yr+ (ZROZ) | +25.3% | −5.2% | −54.9% | +26.9% | −14.9% |
| Long Treasuries 20 yr+ (TLT) | +18.2% | −4.6% | −40.8% | +19.3% | −8.4% |
| Treasuries 7–10 yr (IEF) | +8.4% | −3.3% | −19.0% | +11.5% | −4.5% |
| Broad US bonds (AGG) | +5.6% | −1.8% | −15.3% | +11.9% | −2.7% |
| Inflation-linked (TIP) | +6.2% | +5.7% | −13.5% | +8.8% | −1.9% |
| Short inflation-linked 0–5 yr (STIP) | +2.4% | +5.7% | −0.7% | +6.1% | +1.3% |
| Floating-rate notes (FLOT) | +0.2% | +0.4% | +6.8% | +5.5% | +3.2% |
| US 10-year yield | 1.52% → 0.54% | 0.92% → 1.51% | 1.51% → 4.88% | 4.88% → 3.91% | 4.16% → 5.28% |
Monthly closes, distributions reinvested (Yahoo adjusted closes); bold = best bond ETF in the regime. Descriptive, not advice.
When rates fall hard, length pays. A bond's price moves against its yield, and the longer the bond, the bigger the move. The extreme case is a zero-coupon bond: it pays nothing until it matures, so all of its value sits far in the future. The zero-coupon fund ZROZ gained 25.3% in the first half of 2020 and 26.9% when rates came down from late 2023. We do not show it as the normal tool — it is the far end of the scale. It shows the direction: in a falling-rate regime, the bond half gets longer.
When rates climb, length kills. The same zero-coupon fund lost 54.9% between January 2022 and October 2023; long Treasuries (TLT) lost 40.8%. Today ZROZ is 64.7% below its July 2020 high, the deepest point of the whole period. The tool for this regime sits at the other end: floating-rate notes. Their coupon is reset every few months to the short-term rate plus a fixed margin, so when the central bank hikes, the income rises with it and the price barely moves. The floating-rate fund FLOT gained 6.8% while long bonds lost 40%.
Inflation protection is not rate protection. Inflation-linked Treasuries (TIPS) did their job in 2021, when inflation took off: +5.7%. But the broad TIPS fund TIP still lost 13.5% in 2022–23, because its bonds are long and rising rates hit them too. Short TIPS (STIP, up to five years) kept the inflation link without the rate risk and lost only 0.7%.
C — free account
The free C account unlocks the full Daily Pulse — every section of this read.
One tap with Google or one email — no password, no card. You are signed in until you sign out, on this browser, from then on.
Join the Look — freeAlready joined on this browser? The full edition shows automatically — if it doesn't, sign in again here. Looking for the archive, portfolios and realtime? That is C+.
One more block on our desk — tomorrow's levels and what we're watching into the next session. Join the Look — it’s free.