Source page — copy text into Substack/LinkedIn, upload the visuals. noindex · not public
Closelook@US Stock Markets · Weekly Edition
S&P 500 — The Winners Get Sold, Staples and Health Care Take Over
The selling that started in the chips spread to software and the hyperscalers into Friday — broad profit-taking in everything that had won the year. The chip fund fell 11.8%, software 7.4%, CrowdStrike 17.3%, Oracle 9.3%; the Nasdaq 100 fund lost 5.5% and closed under the rising line that had held since the 30 March low. Underneath, seven of eleven sectors rose — consumer staples +5.0% to their best close since March, health care +3.5% after a one-year high on Thursday, energy +4.9%. The equal-weight S&P rose, the Nasdaq without its tech stocks rose for a second week, and the ten-year yield fell to 5.10% despite hot inflation numbers. Money did not leave the market. It left the winners.
Closelooknet is a reader-supported publication — to receive new posts and support the work, become a free or paid subscriber.
1 · This Week's Action
The winners were sold — all of them, and hardest into Friday. It started with the chips and did not stay there. The chip fund SOXX fell 11.8% to 493.39, its eighth down day in a row on Friday. Software joined on Wednesday and again on Friday: the software fund IGV fell 7.4%, 4.8% of it on Friday alone; CrowdStrike −17.3%, Palo Alto −18.3%, Snowflake −16.8%, Palantir −11.0%. And the hyperscalers went with them: Oracle −9.3%, Amazon −4.7%, Alphabet −3.1%, Microsoft −1.1%, with Alphabet −2.5%, Meta −3.7% and Microsoft −1.9% on Friday alone. Nvidia fell 6.6% to 214.13. This was not one sector's bad week. It was broad profit-taking in everything that had carried the year.
The index and the market under it. The S&P 500 fund fell 1.97% to 763.25. The Nasdaq 100 fund fell 5.52% to 709.80. But the equal-weight S&P rose 0.49% — the average stock was up in a week the index was down two percent and the Nasdaq five. The Nasdaq 100 without its tech stocks rose 0.82% to 98.95, its second week up; the tech half of the Nasdaq 100 fell 9.15%. Small caps fell 3.05%.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| USO | United States Oil LP | 161.76 | +9.15% | +3.58% | +35.59% | +28.54% | +133.89% |
| TLT | iShares 20+ Year Treasury Bond | 80.05 | +2.65% | -1.03% | -4.94% | -7.22% | -8.16% |
| IEF | iShares 7-10 Year Treasury Bon | 90.42 | +1.14% | -0.34% | -3.52% | -5.23% | -5.97% |
| UUP | Invesco DB US Dollar Index Bul | 28.92 | -0.34% | +1.83% | +2.05% | +5.66% | +6.99% |
| GLD | Gold Shares | 382.01 | -0.67% | -2.48% | +4.67% | -13.20% | -3.61% |
| IBIT | iShares Bitcoin | 46.15 | -0.86% | +7.23% | +26.82% | +8.00% | -7.05% |
| SPY | S&P 500 | 763.25 | -1.97% | +1.22% | +1.67% | +8.78% | +11.93% |
| TOPT | iShares Top 20 U.S. Stocks | 34.6 | -2.54% | +2.52% | +3.87% | +10.65% | +10.79% |
| QQQ | Invesco QQQ | 709.8 | -5.52% | +0.72% | +0.55% | +10.82% | +15.54% |
| SLV | iShares Silver | 51.51 | -5.97% | -9.71% | +2.22% | -27.70% | -20.04% |
| QTOP | iShares Nasdaq Top 30 Stocks | 37.19 | -6.44% | +0.49% | +0.38% | +10.40% | +16.36% |
| COPX | Global X - Copper Miners | 79.98 | -6.73% | -5.00% | +7.10% | -7.23% | +11.41% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The tech bull channels broke. Since the 30 March low every dip in the tech funds stopped on a rising line, drawn from that low through the late-July low. This week QQQ closed under it — the line runs at about 729 to 732 now, the fund closed Friday at 709.80. Wednesday and Thursday it closed right on the line, at 728.95 and 728.00; Friday's 2.5% drop took it through. The tech sector fund XLK closed at 183.47 against a line at about 193; the chip fund SMH at 539.79 against about 601. Software is the one that kept its spring line — IGV at 104.34 sits above the line from the April low through the June low, near 100 — but it fell through the steeper line it had followed since August.
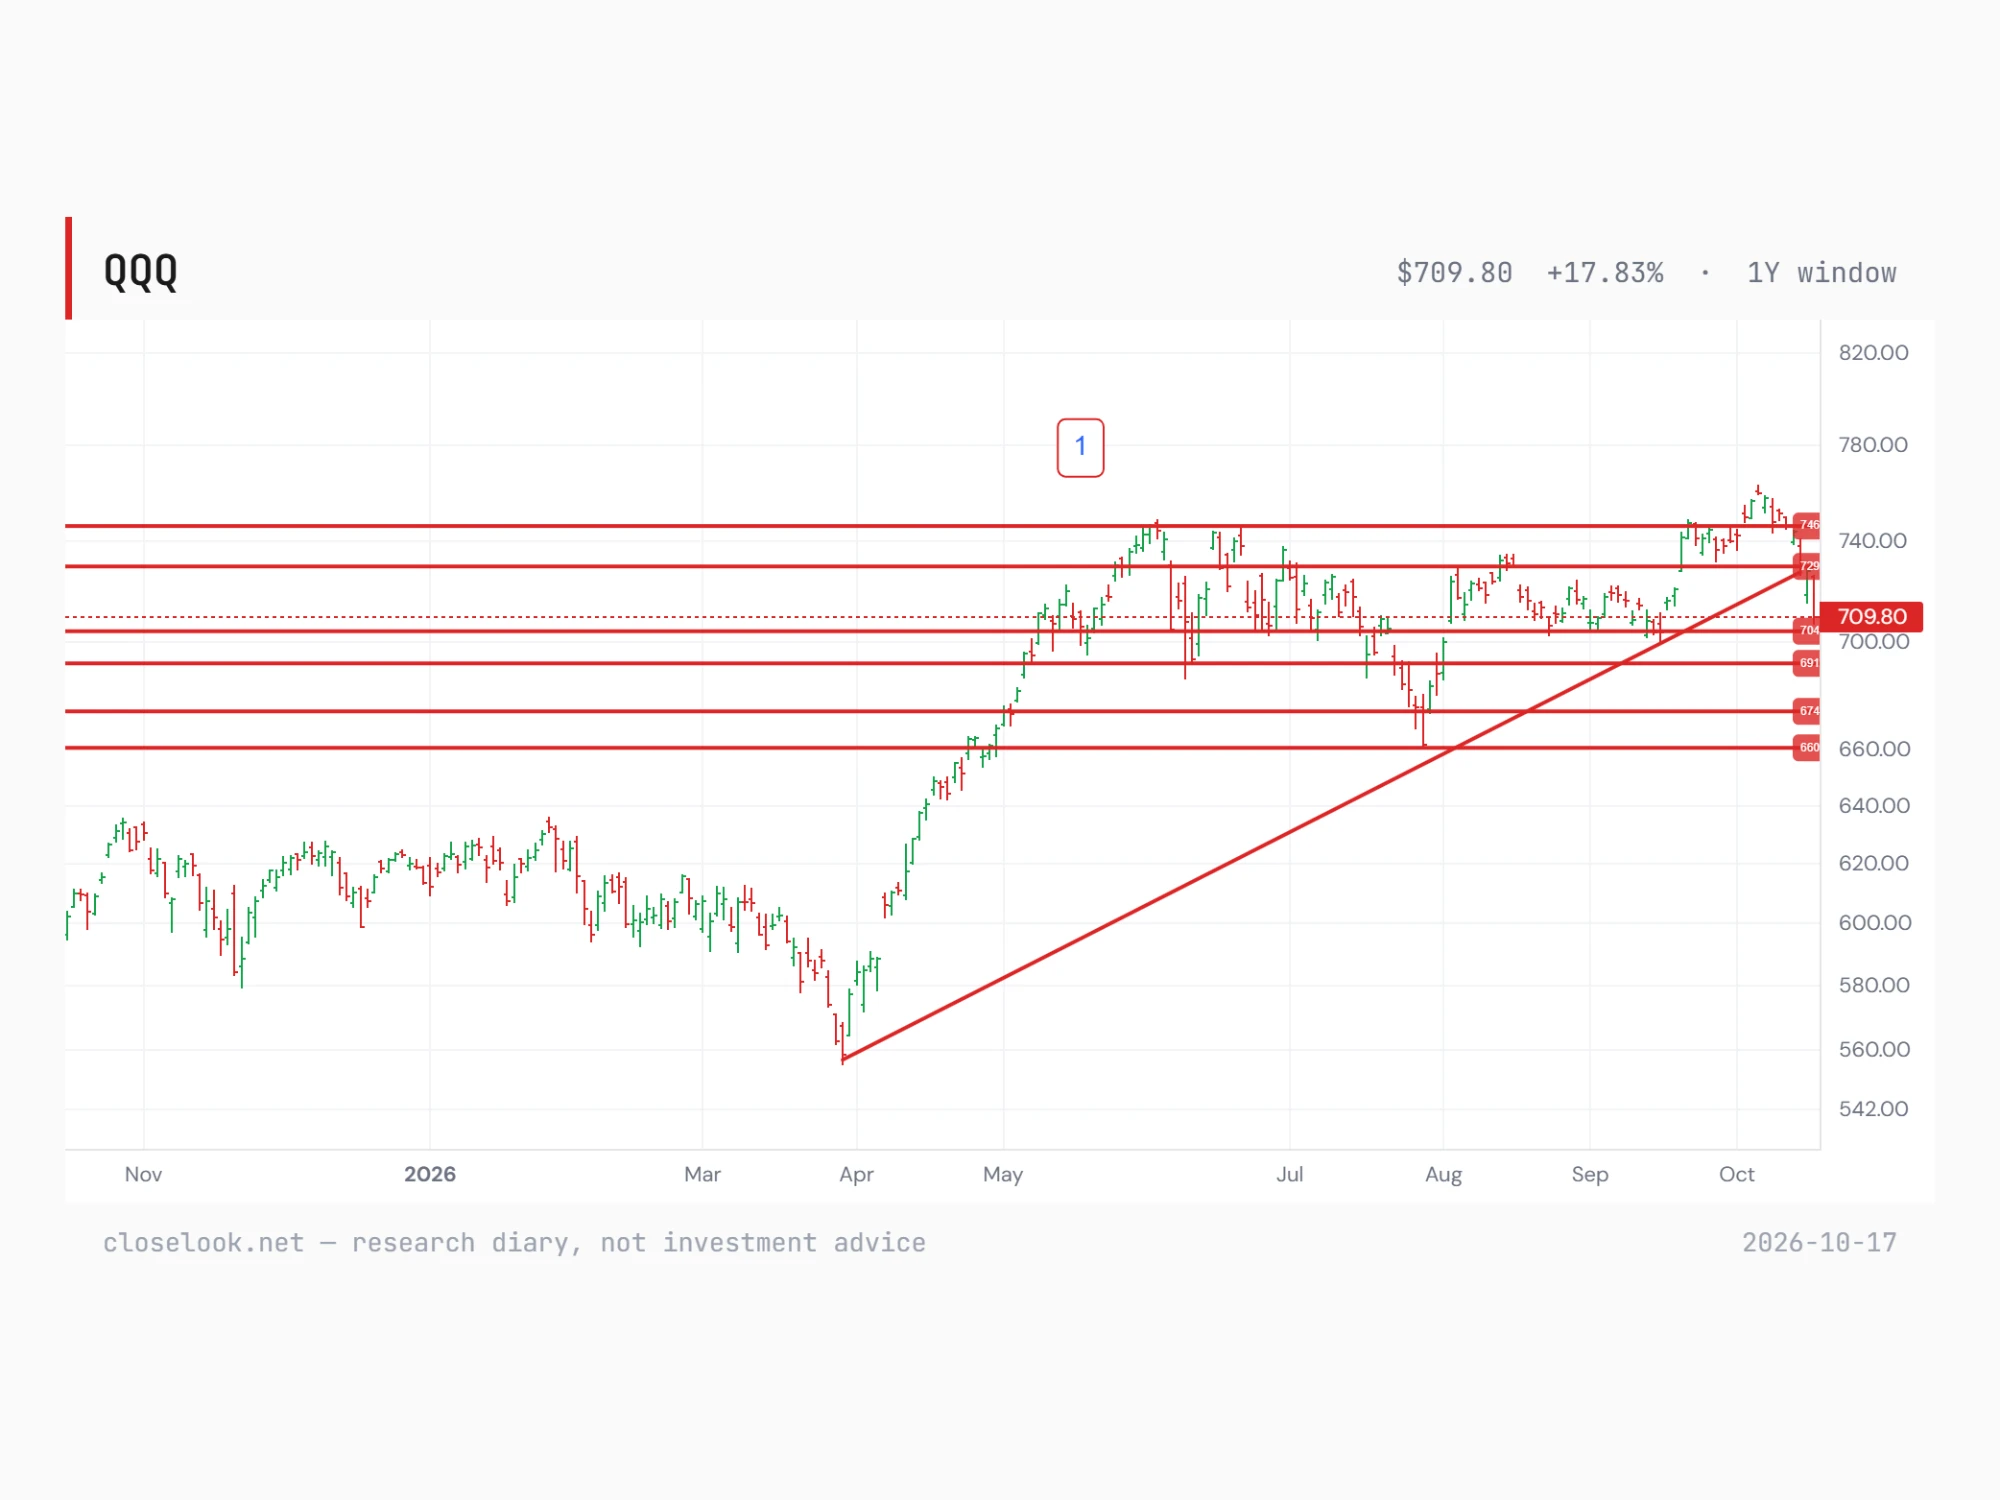
The editor's chart: QQQ over one year — the rising line from the 30 March low through the late-July low, broken on Friday at 709.80; horizontal lines at 746, 729, 704, 691, 674 and 660; the editor marks the June top as wave 1.
The levels under it, from the editor's chart. 746 — last week's confirmation line — was lost on Monday by twelve cents and never regained. 729 went on Friday. The next lines are 704, the area of the September low (704.54 on 15 September, 700.00 intraday the day after), then 691, 674 and 660 — the last the July low that the rising line was drawn through.
The eleven S&P 500 sectors
Seven of eleven up — in a week the Nasdaq fell 5.5%. Consumer staples +5.02% to 87.62, their highest close since 3 March. Energy +4.86%. Health care +3.45% to 176.71, after a one-year closing high of 177.19 on Thursday. Materials +3.01%, utilities +1.93%, financials +1.44%, real estate +1.32%. Communications −0.05%, consumer discretionary −0.35%, industrials −0.88% — and technology −7.70%, the only sector with a real loss and still +27.4% on the year.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| XLP | Consumer Staples | 87.62 | +5.02% | +5.15% | +2.11% | +7.60% | +12.80% |
| XLE | Energy | 68.24 | +4.86% | +6.58% | +19.68% | +20.61% | +52.63% |
| XLV | Health Care | 176.71 | +3.45% | +5.33% | +9.22% | +20.53% | +14.15% |
| XLB | Materials | 50.92 | +3.01% | +1.11% | +0.06% | -1.60% | +12.28% |
| XLU | Utilities | 42.21 | +1.93% | +2.15% | -7.17% | -8.93% | -1.12% |
| XLF | Financial | 55.52 | +1.44% | -0.73% | -2.17% | +6.71% | +1.37% |
| XLRE | Real Estate | 42.16 | +1.32% | -1.52% | -7.26% | -3.77% | +4.49% |
| XLC | Communication Services | 110.32 | -0.05% | -2.37% | -2.07% | -7.16% | -6.29% |
| XLY | Consumer Discretionary | 112.46 | -0.35% | +2.07% | -4.16% | -4.40% | -5.82% |
| XLI | Industrial | 167.76 | -0.88% | -0.56% | -6.88% | -1.51% | +8.15% |
| XLK | Technology | 183.47 | -7.70% | -0.25% | +3.35% | +20.69% | +27.44% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The shape of it: defensive growers. Staples and health care are the companies that keep growing when the economy slows — food, soap, medicine. Friday's Pulse put it in one line: out of chips, into pills and soap. Since the 6 October record health care is up 6.0% and staples 6.0%, technology down 6.3%, chips 12.7%. Against the S&P this week staples beat it by 7.0 points, energy by 6.8, health care by 5.4; technology trailed by 5.7.
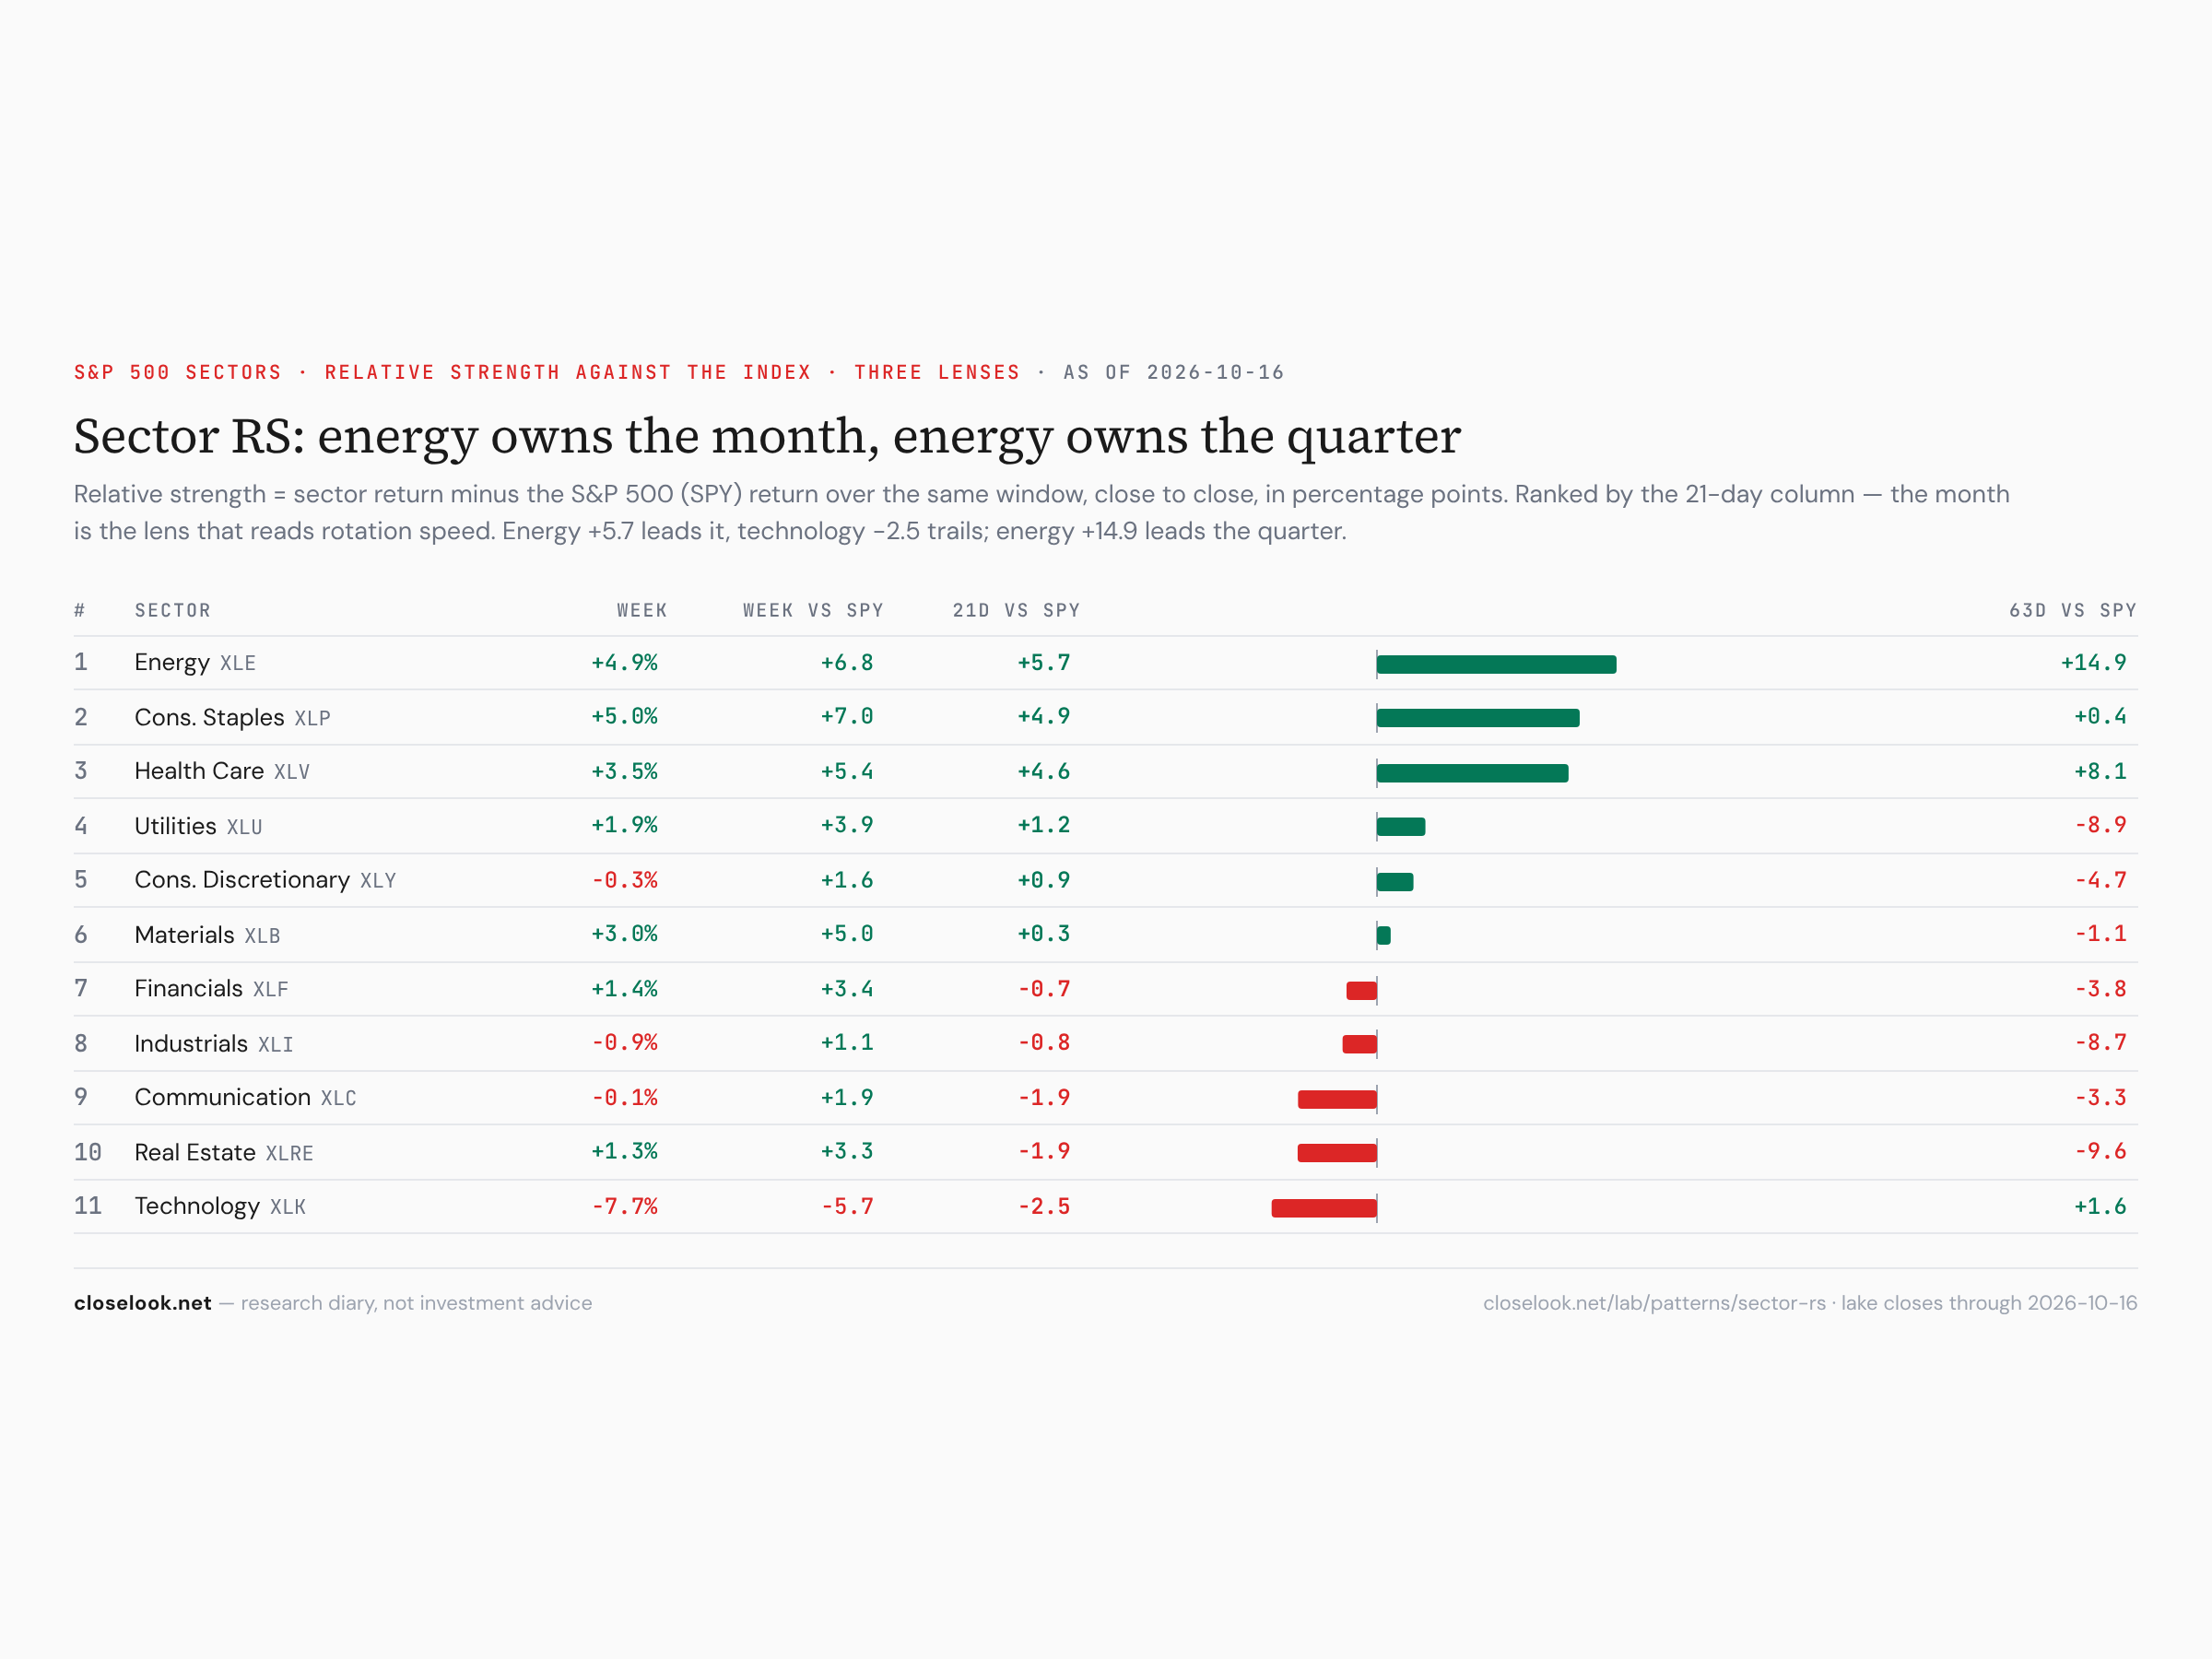
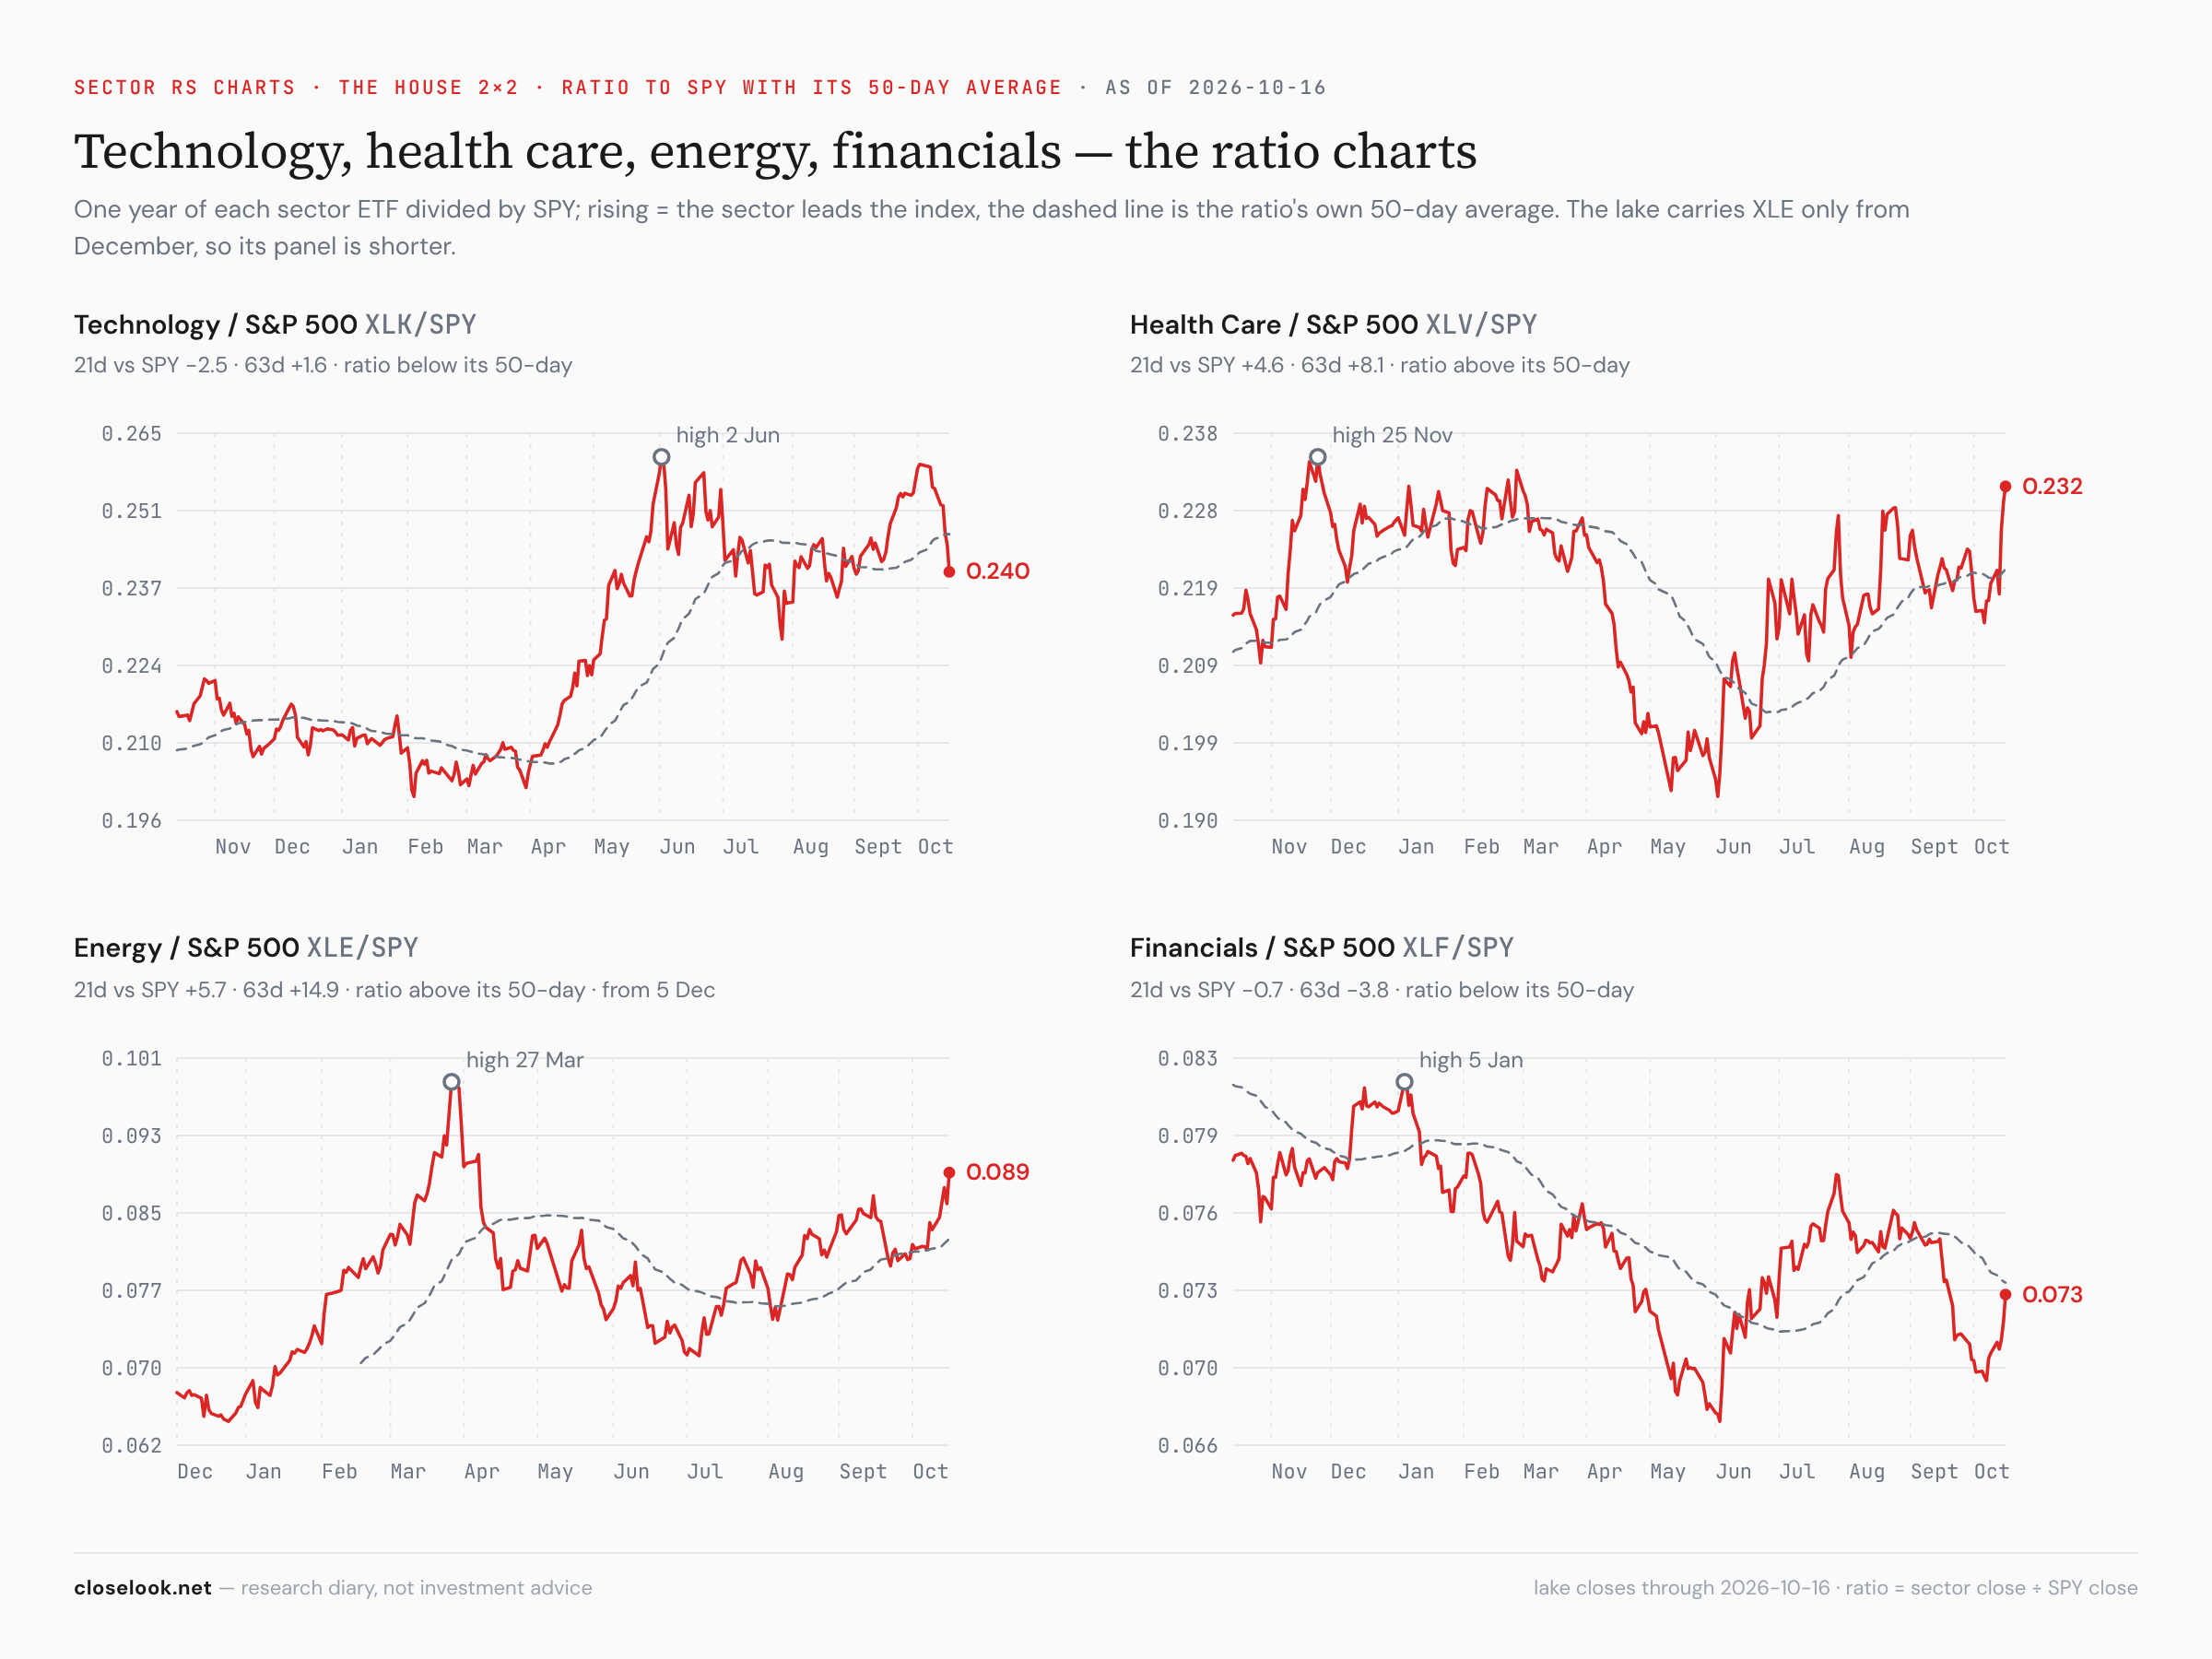
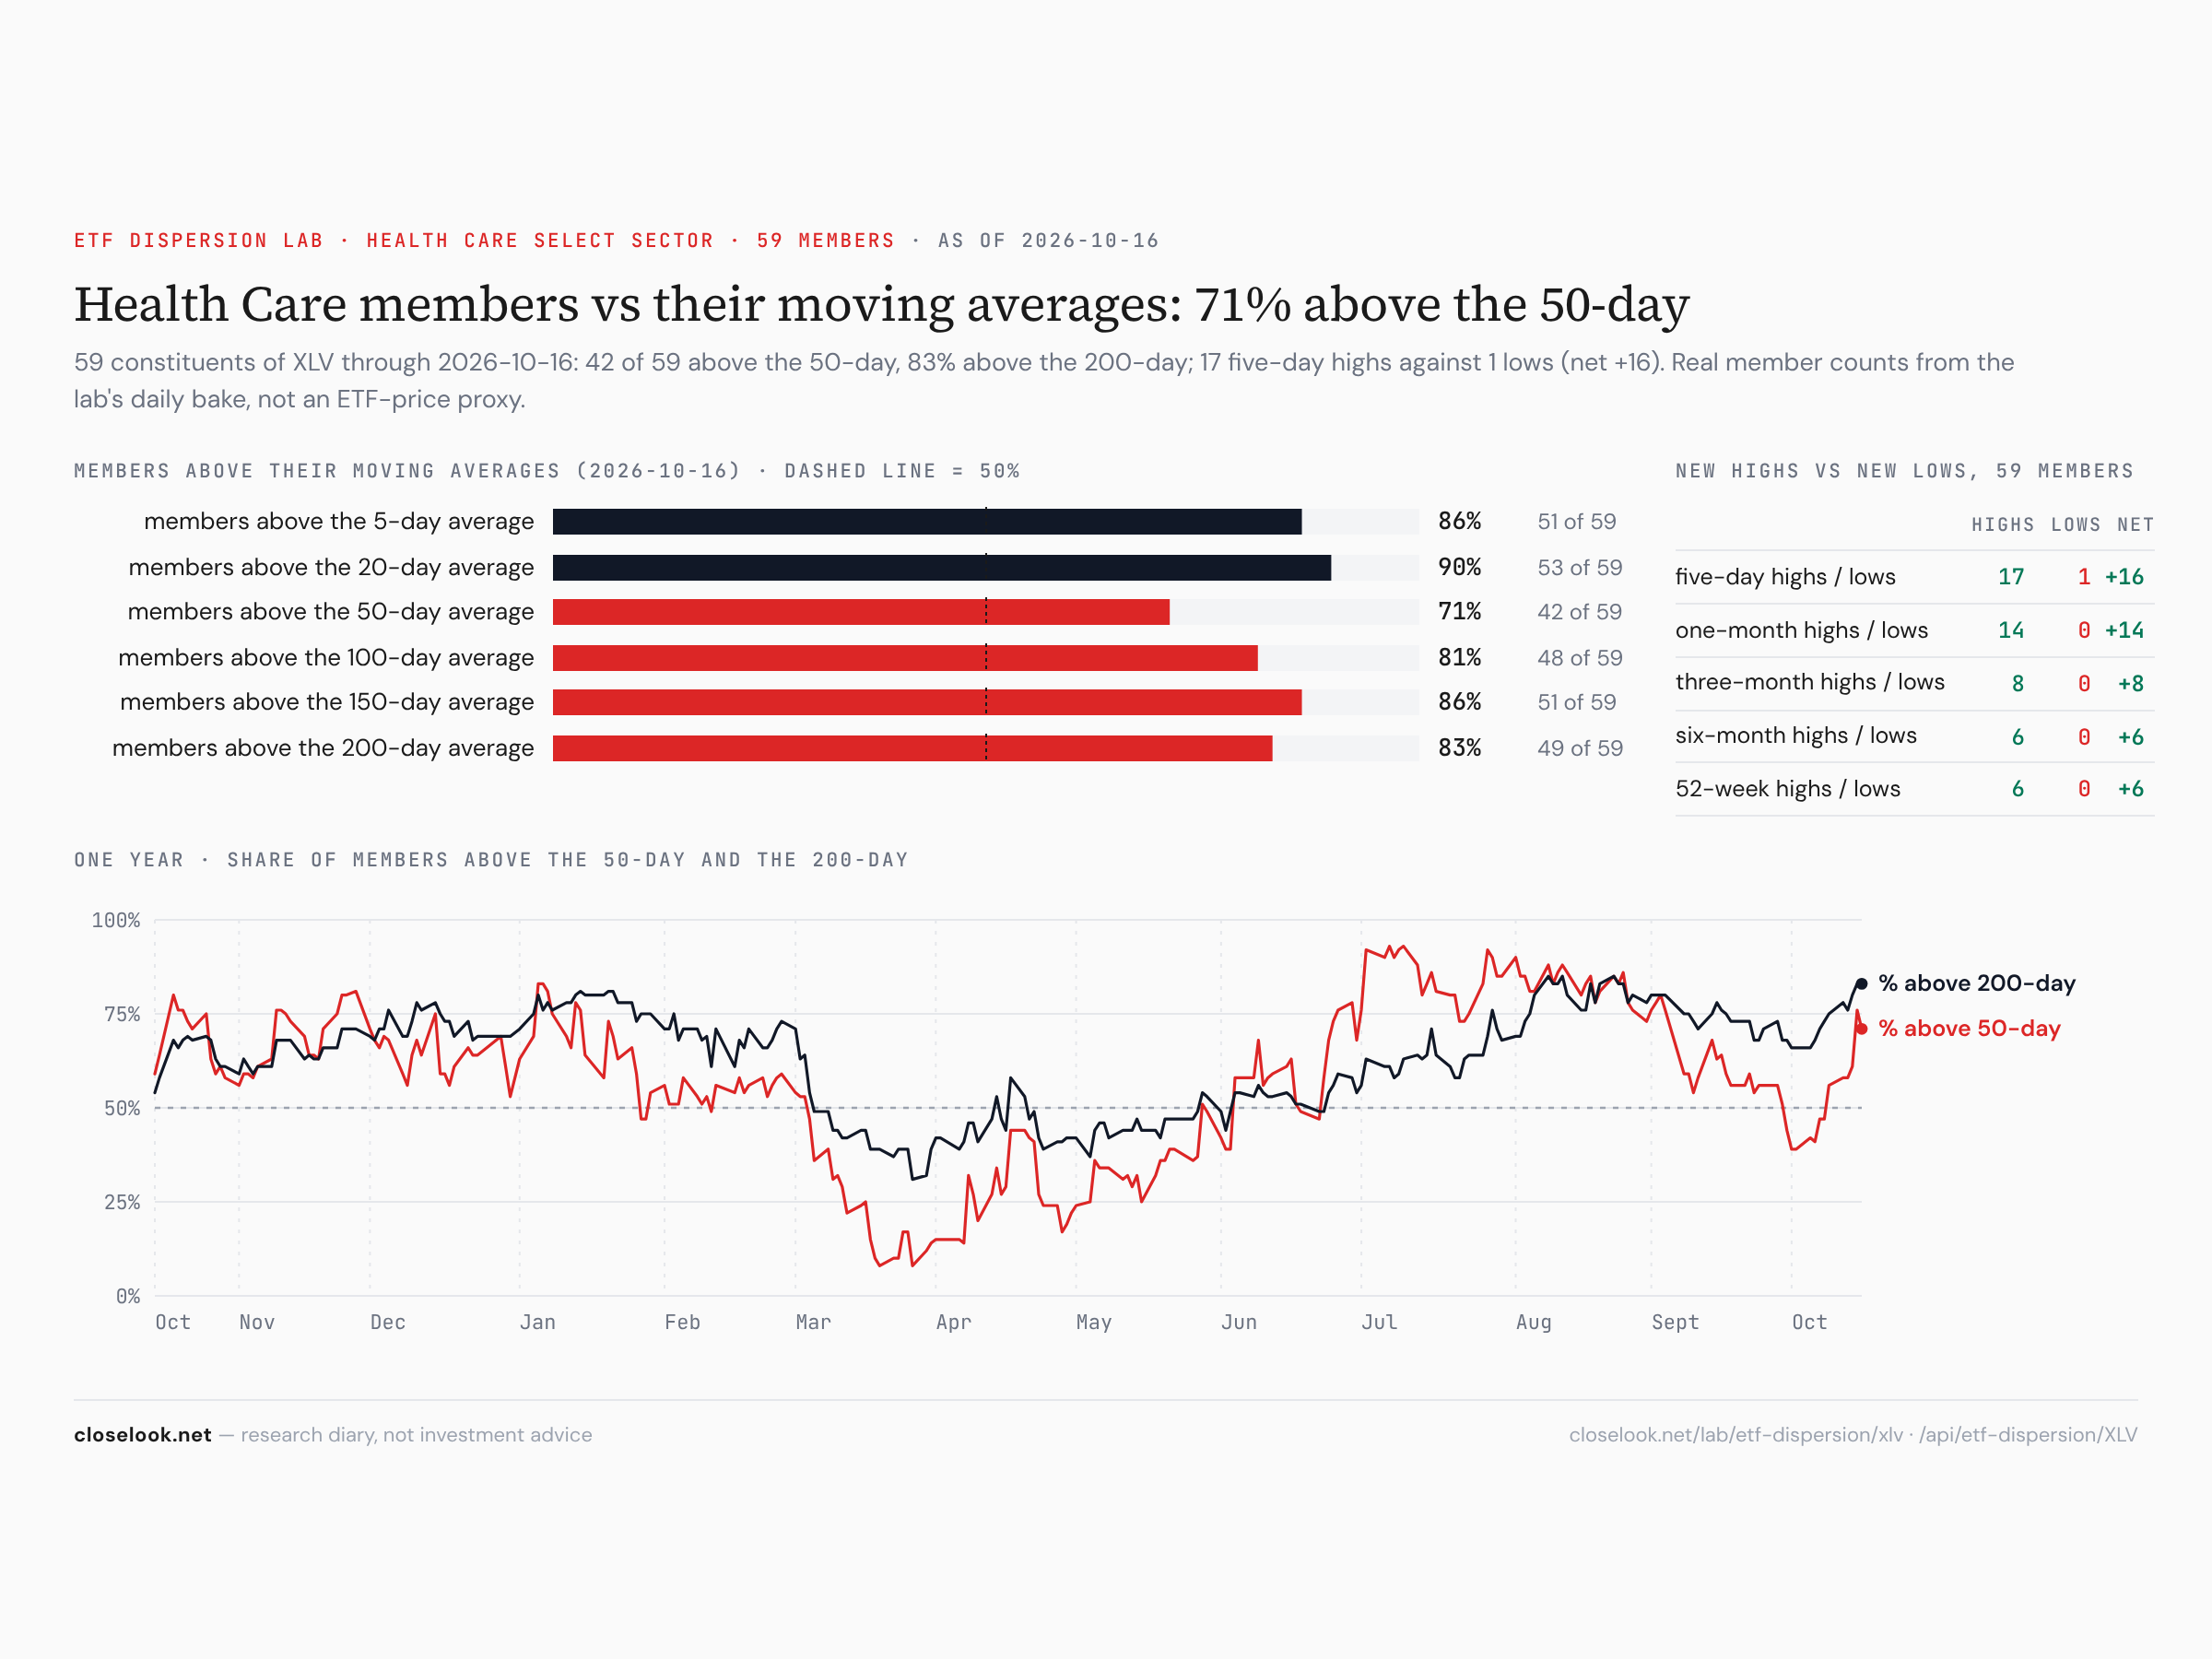
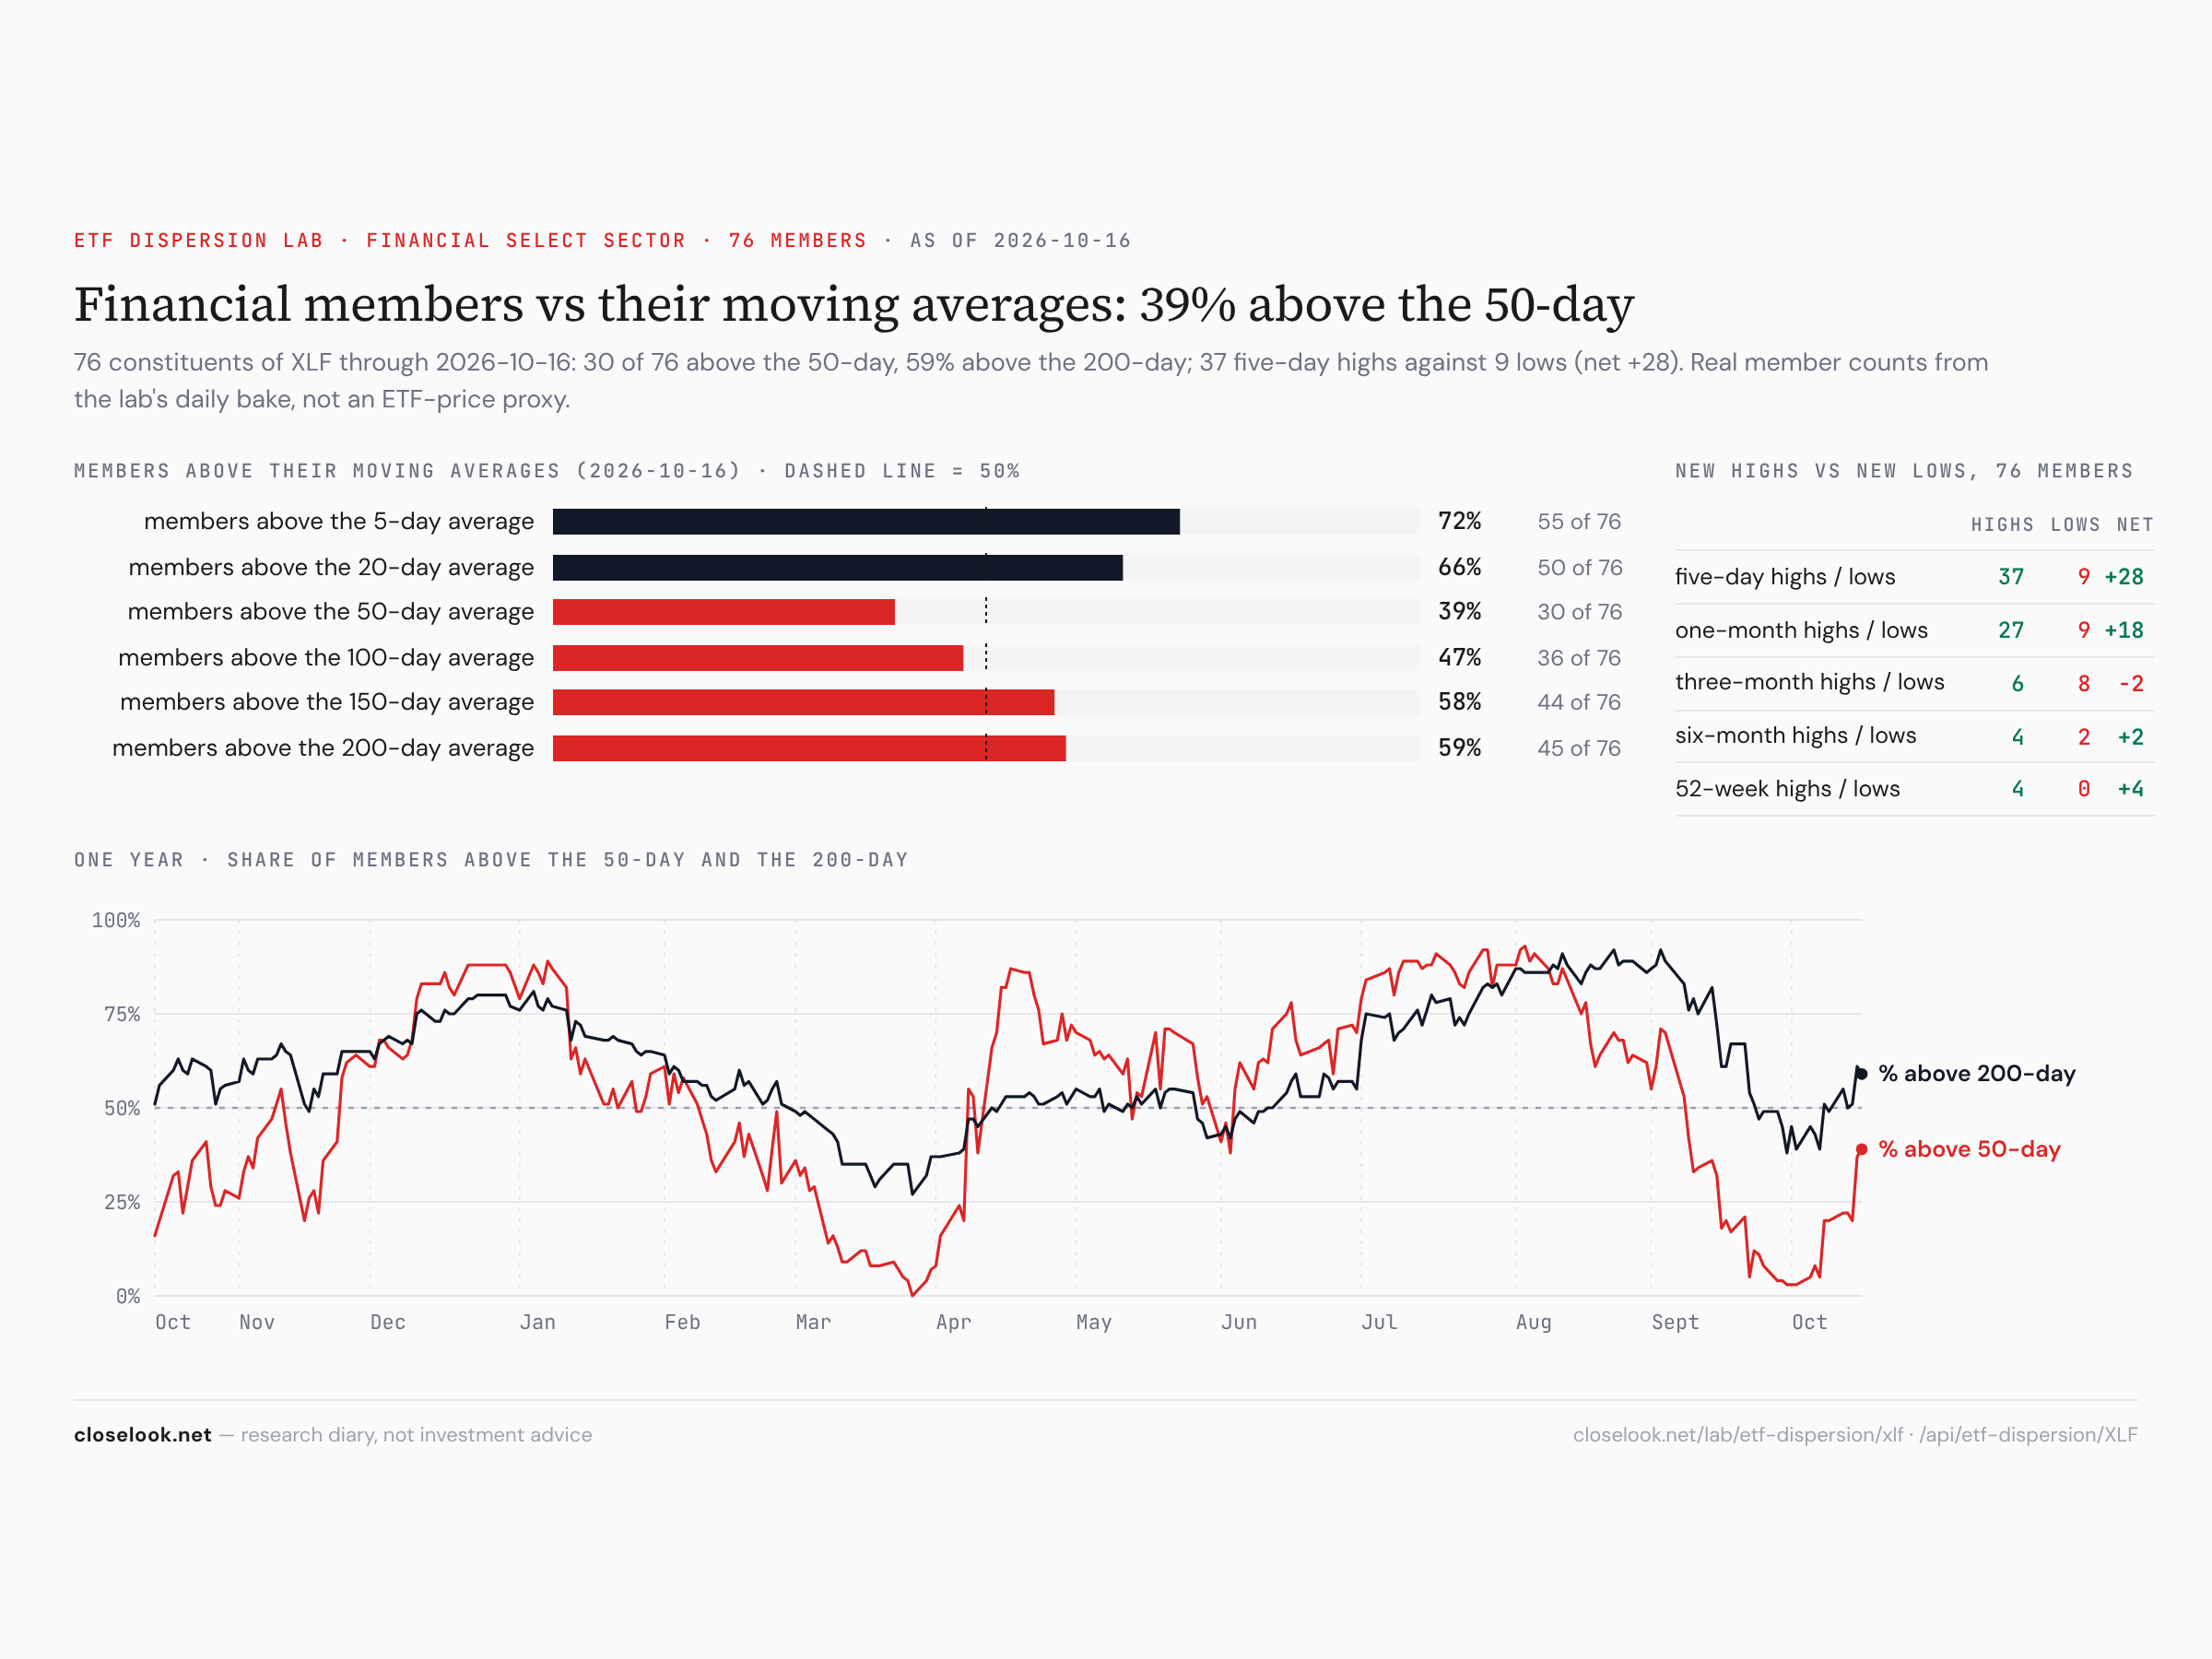
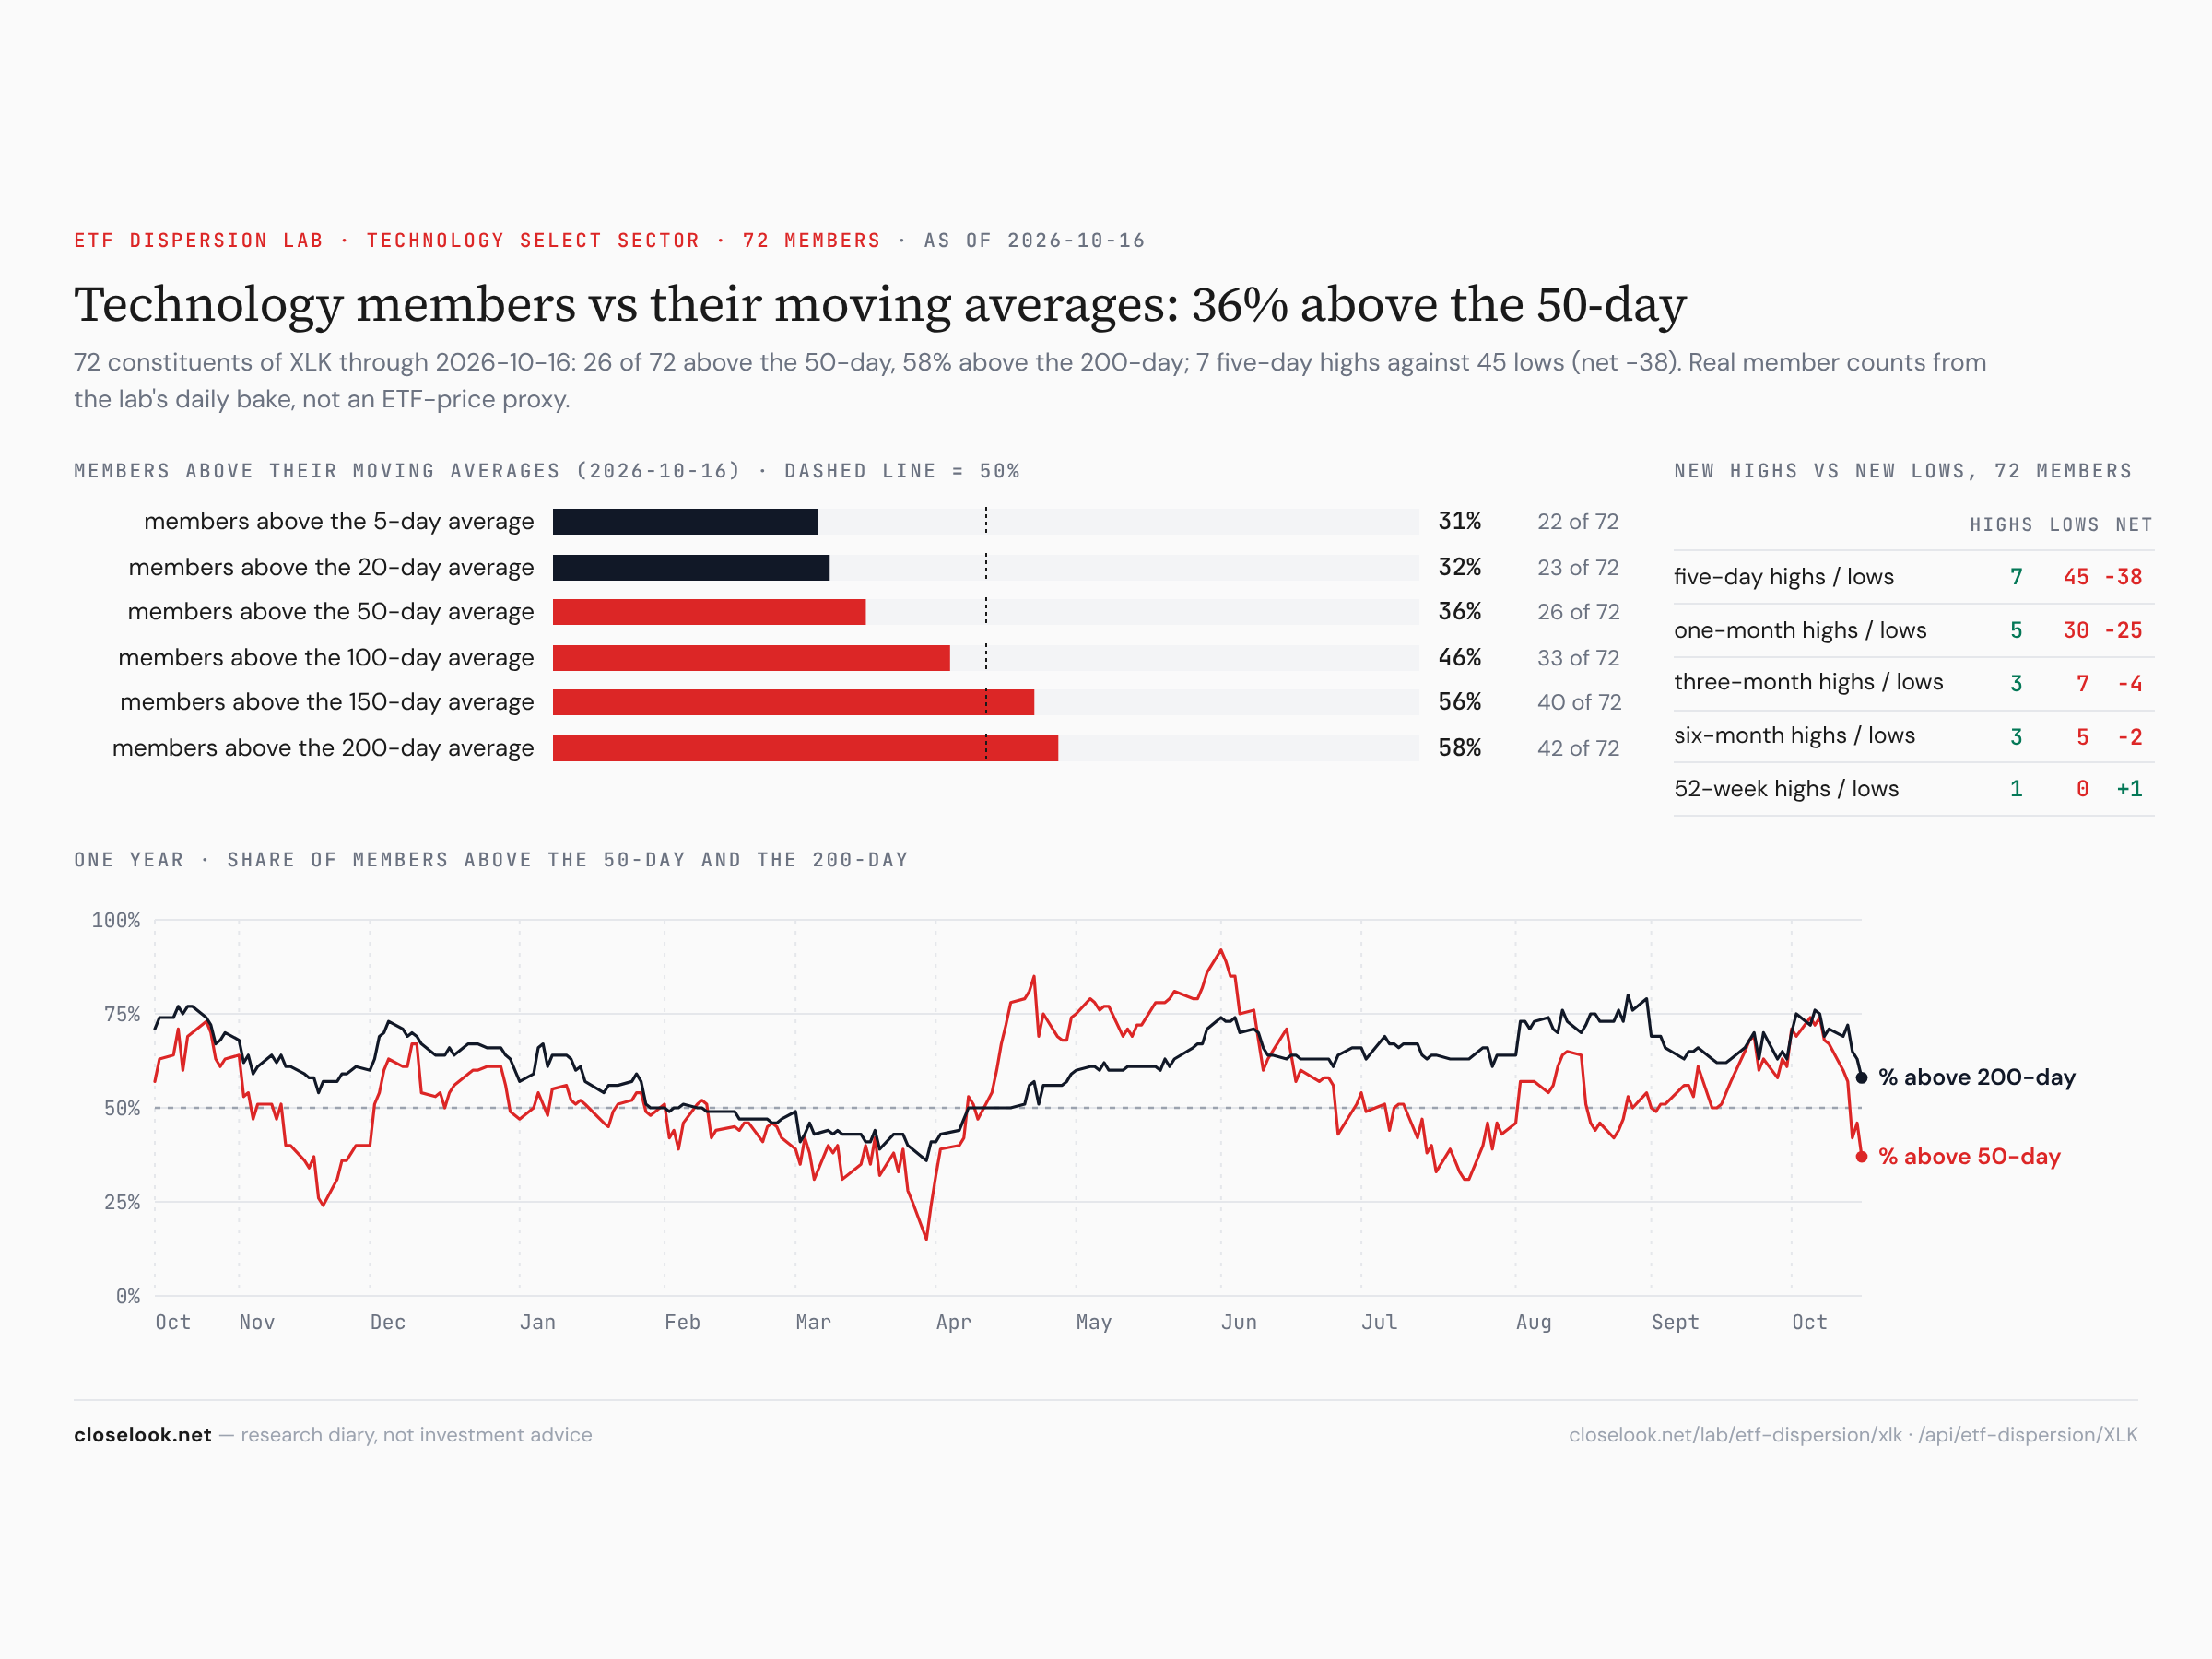
Breadth — health care and energy strong, tech thin. In health care 51 of 59 members closed above their 5-day average and 42 above the 50-day, with 17 new five-day highs against one low. In energy 16 of 21 are above the 50-day. In financials 55 of 76 are above the 5-day, 30 above the 50-day — up from none above the 20-day two weeks ago. Technology is the mirror: 26 of 72 above the 50-day, 45 new five-day lows against 7 highs.
The Nasdaq 100, cut six ways
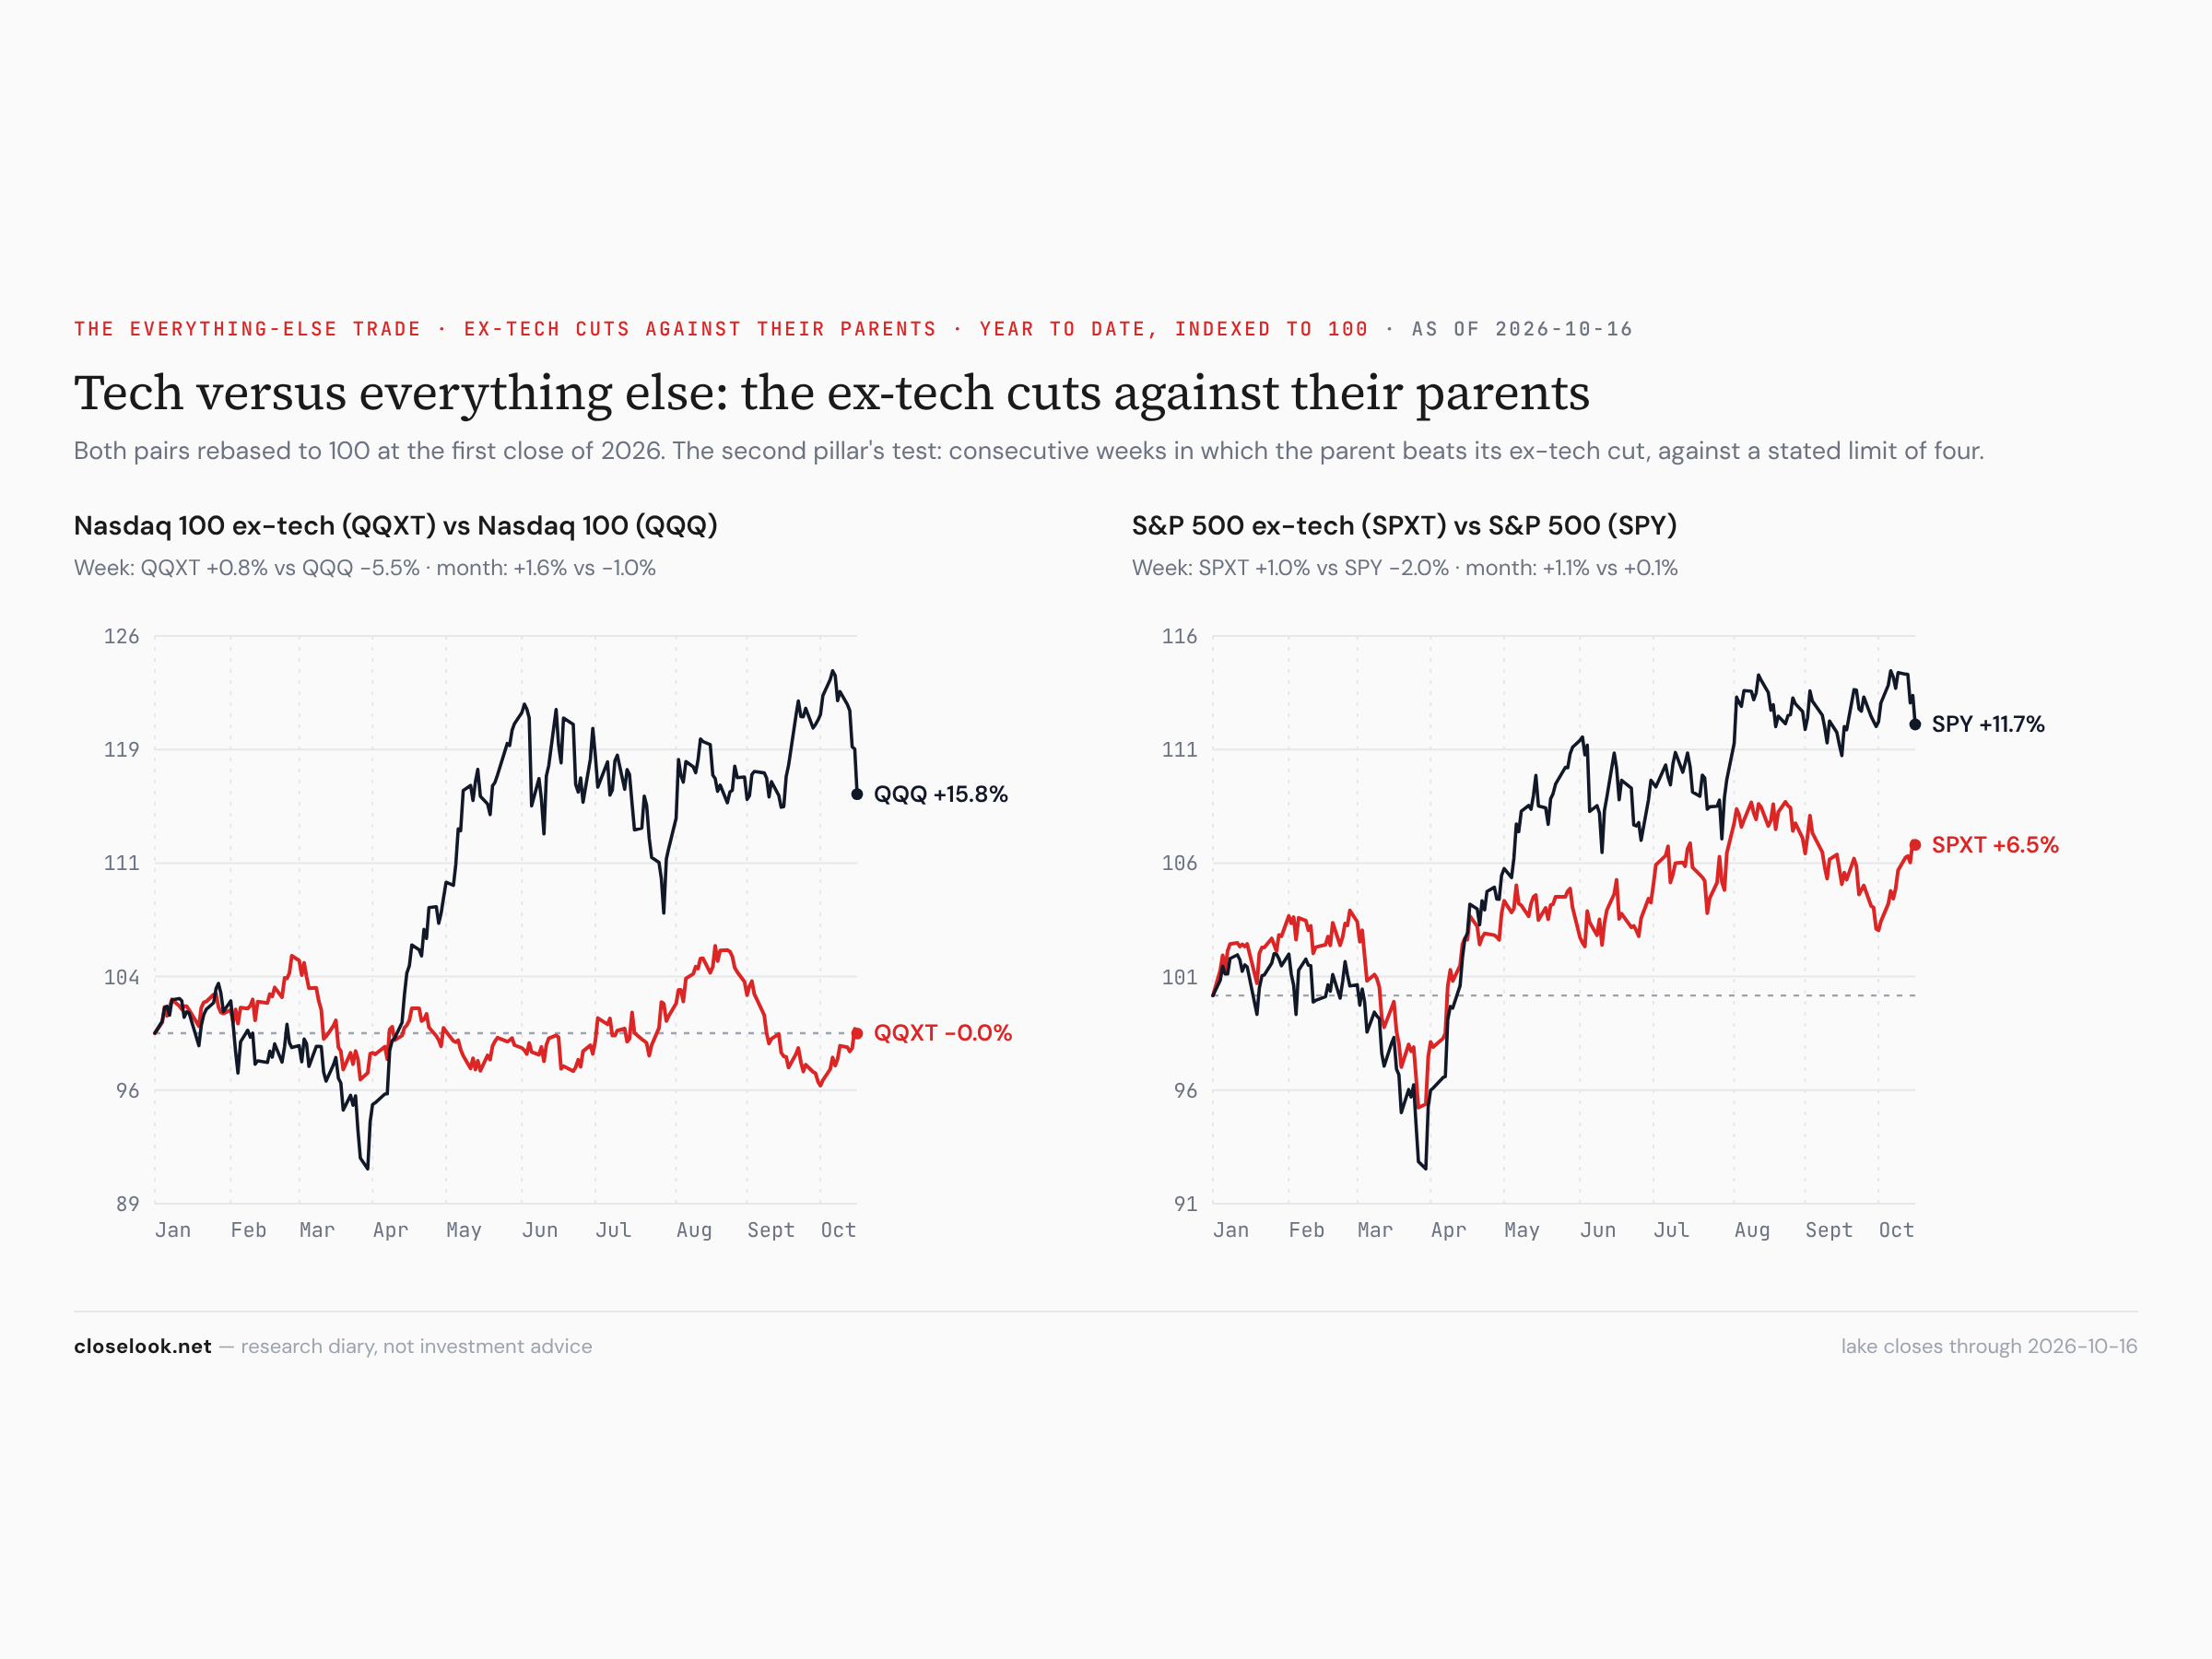
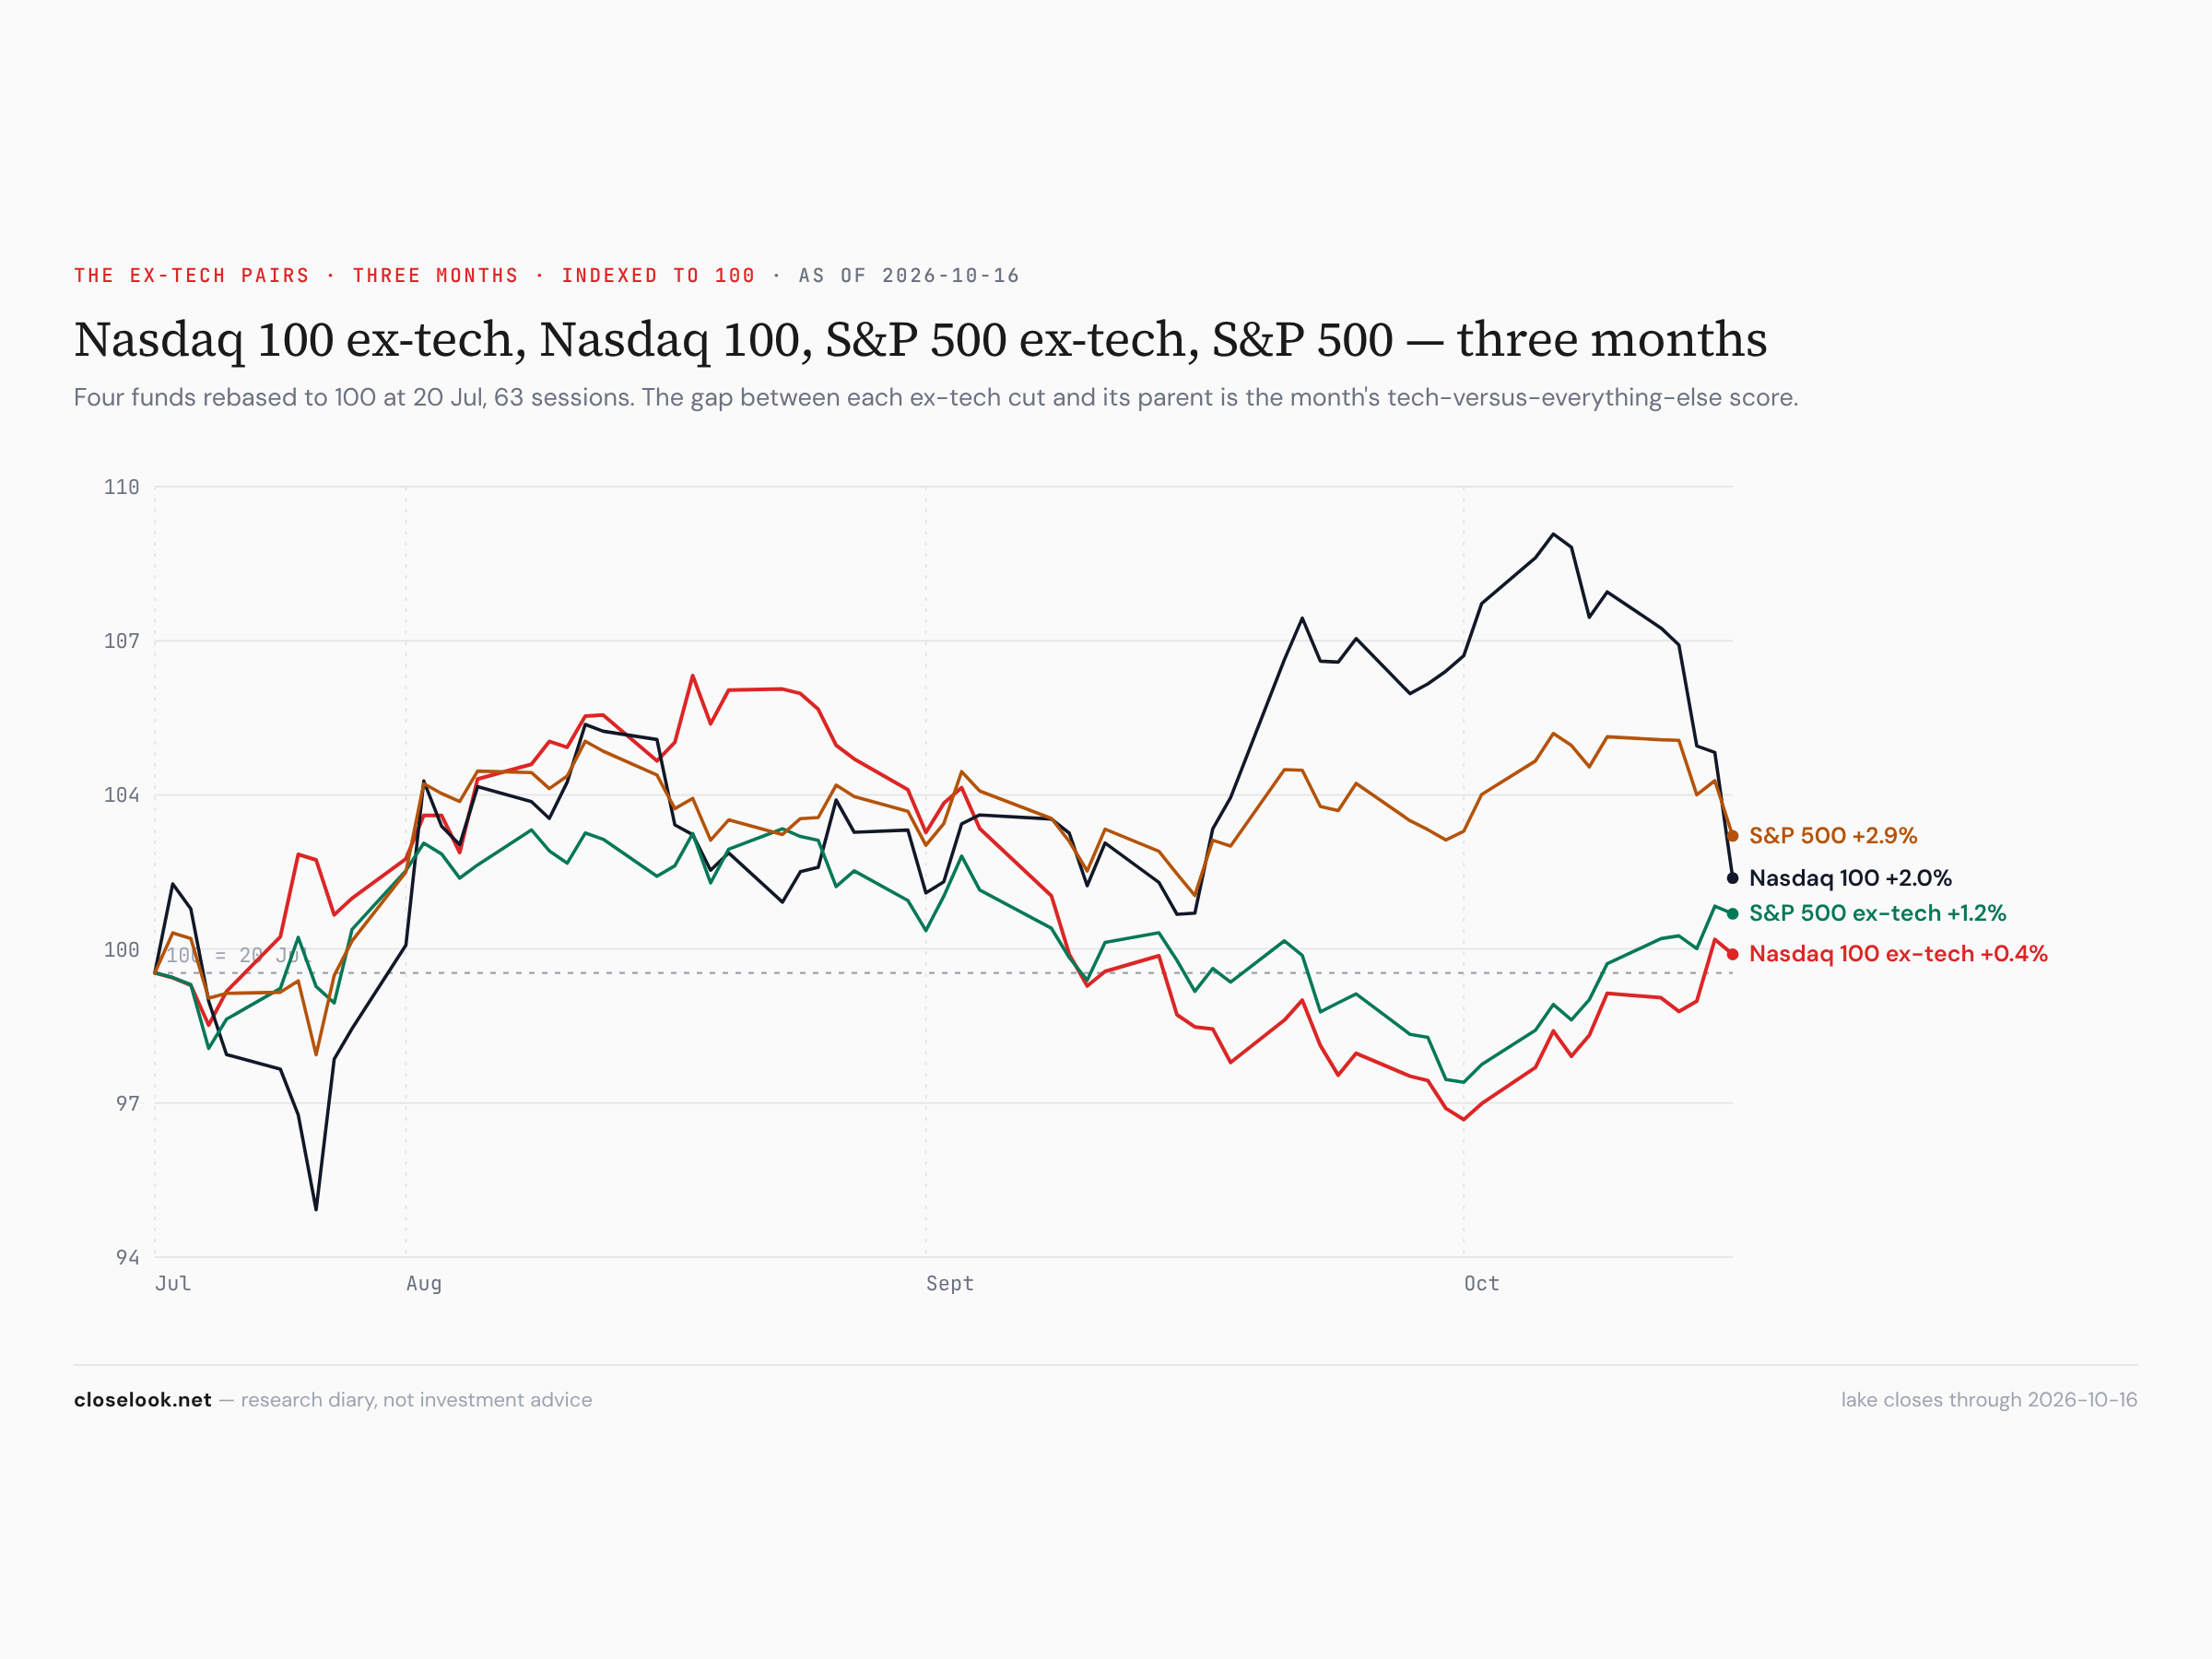
The week: the Nasdaq 100 without tech +0.82%, the S&P 500 without tech +1.04%, the S&P without the Magnificent Seven −1.65%, the S&P −1.97%, the Magnificent Seven fund −3.38%, the Nasdaq 100 −5.52%, the Nasdaq tech sector −9.15%. On the year: Nasdaq tech +30.8% (from +44.0% a week ago), the Nasdaq 100 +15.5%, the S&P +11.9%, the S&P without tech +6.7%, the Nasdaq without tech −0.4%. Thirteen points of the tech half's year went in five sessions.
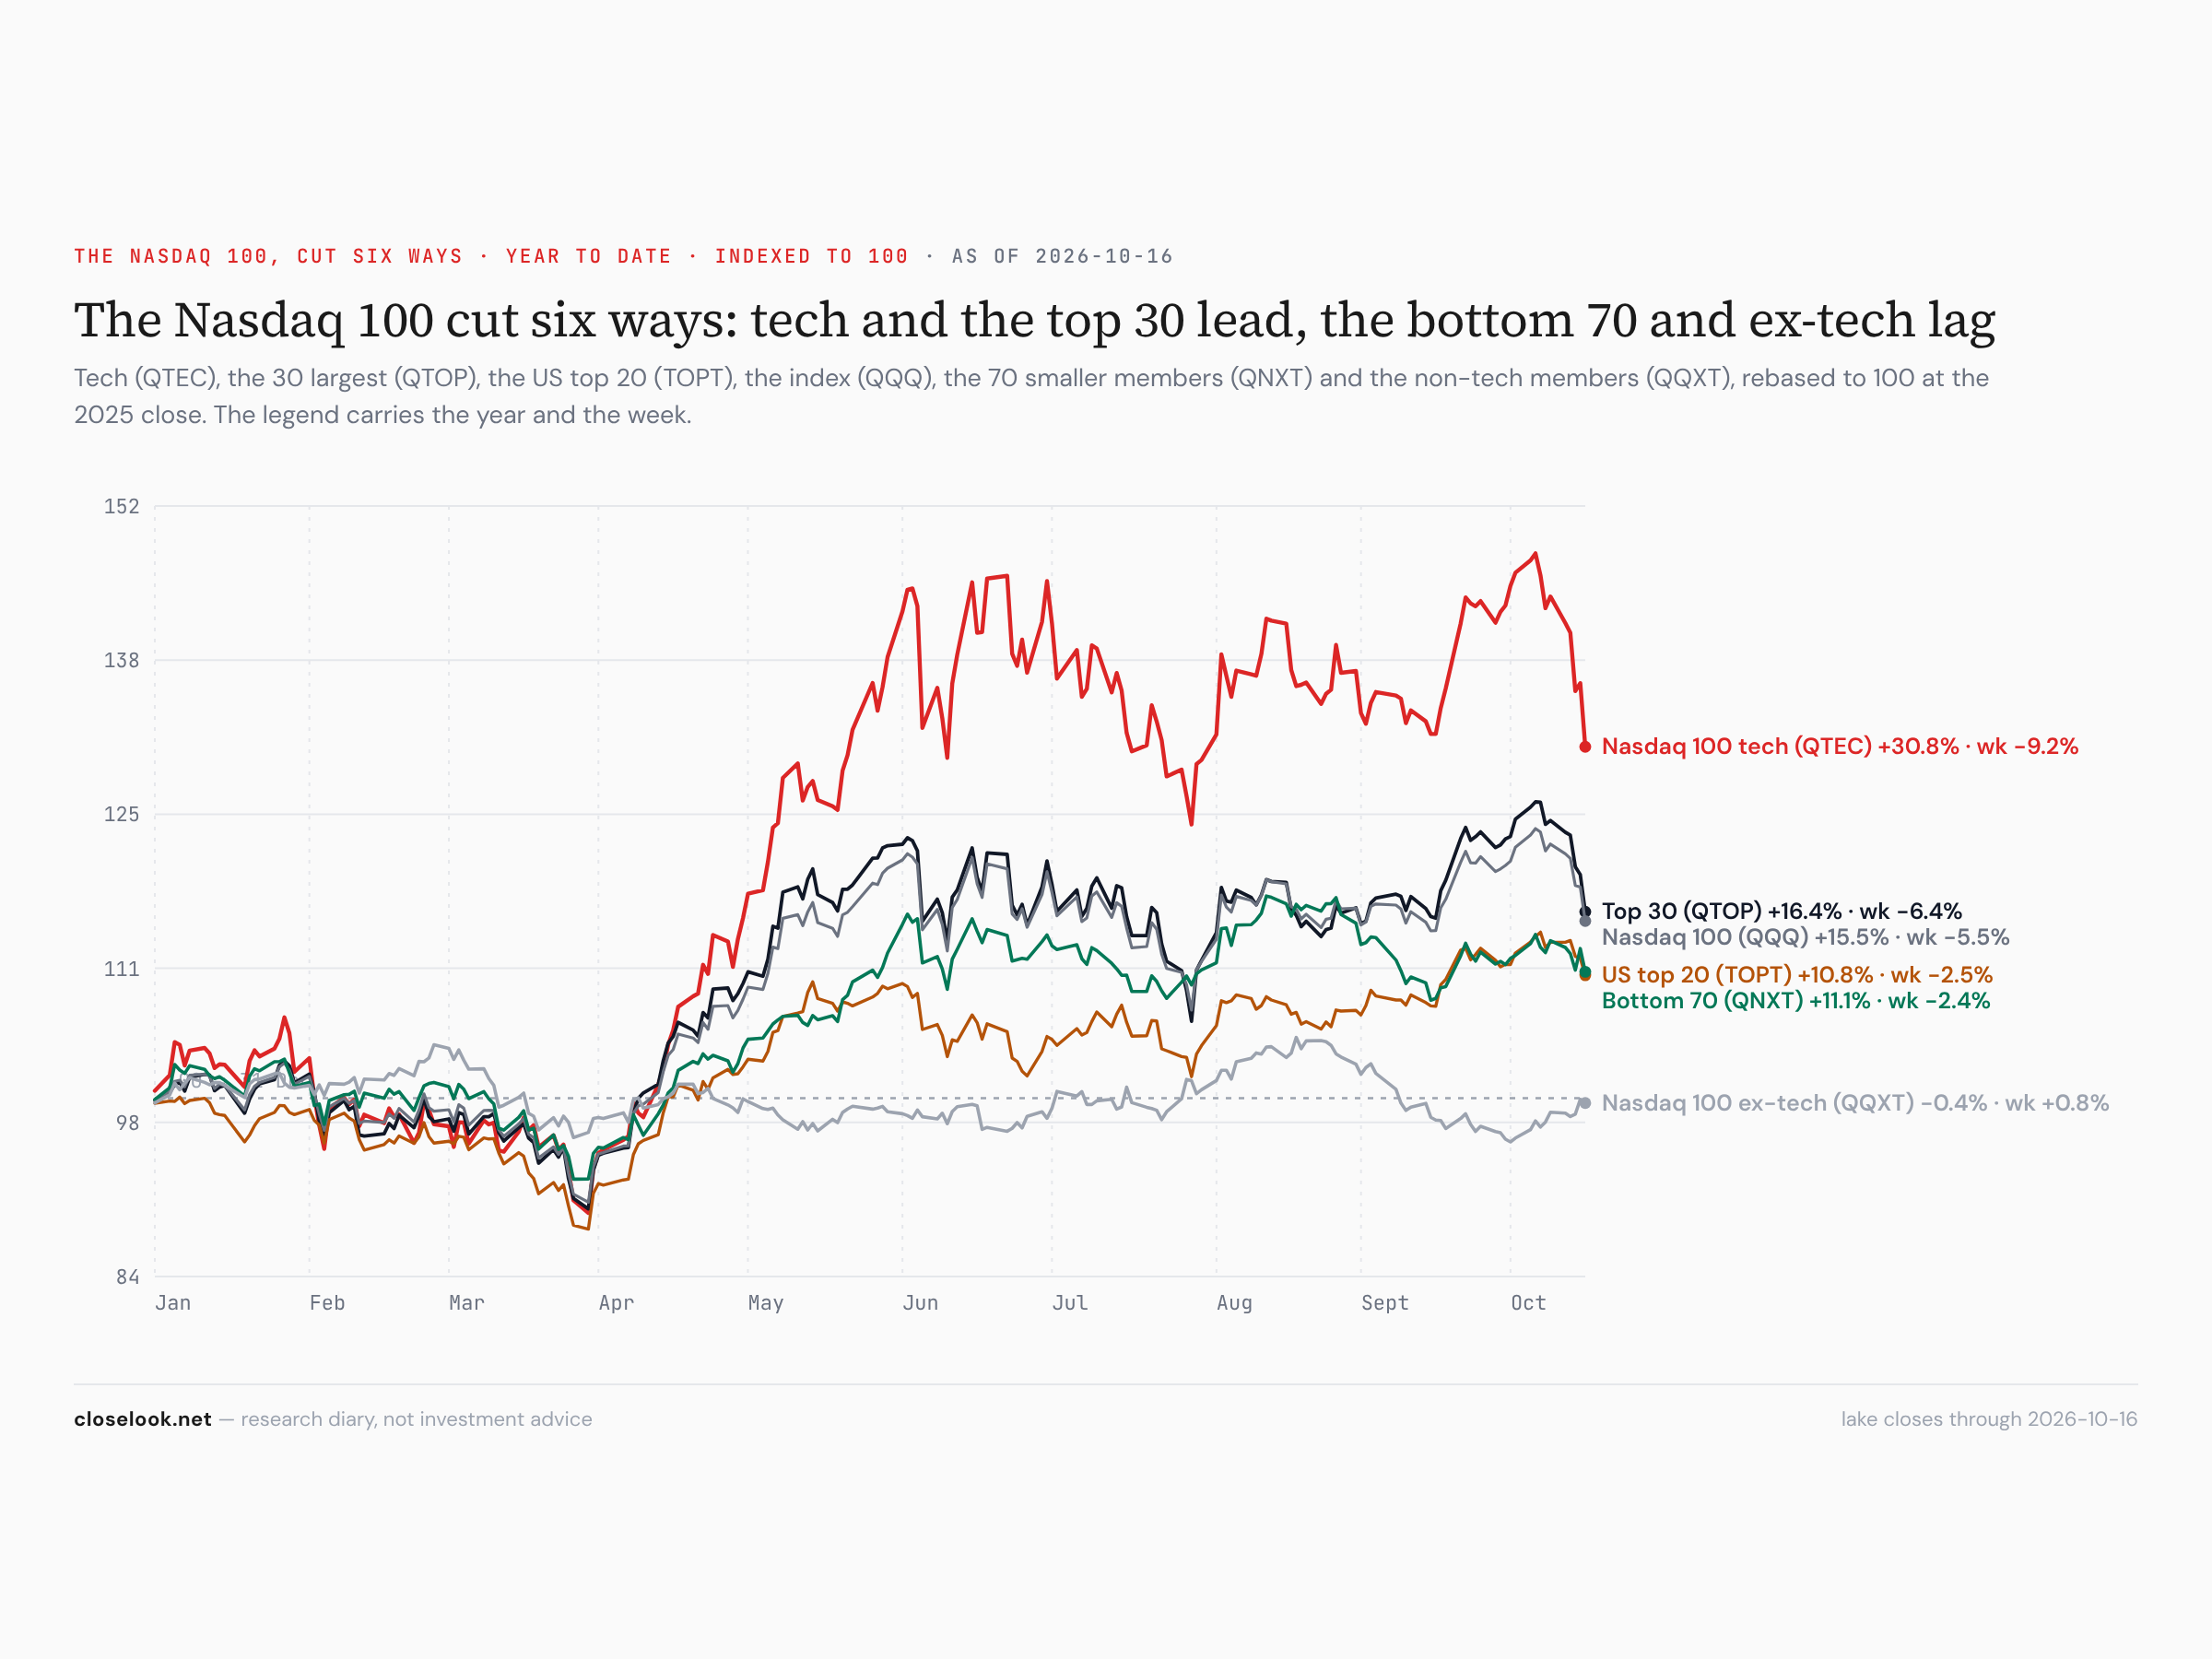
The counterpoint: the Nasdaq without tech is green. QQXT closed at 98.95 — its low of the year was 95.56 on 1 October, and it closed at 99.26 on Thursday, the best close since the low. In the week the tech half fell 9%, the other half of the same index rose. That is rotation inside the Nasdaq, not a sell-everything week: the money that left Nvidia, CrowdStrike and Oracle went to the drug makers, the retailers and the food companies in the same index.
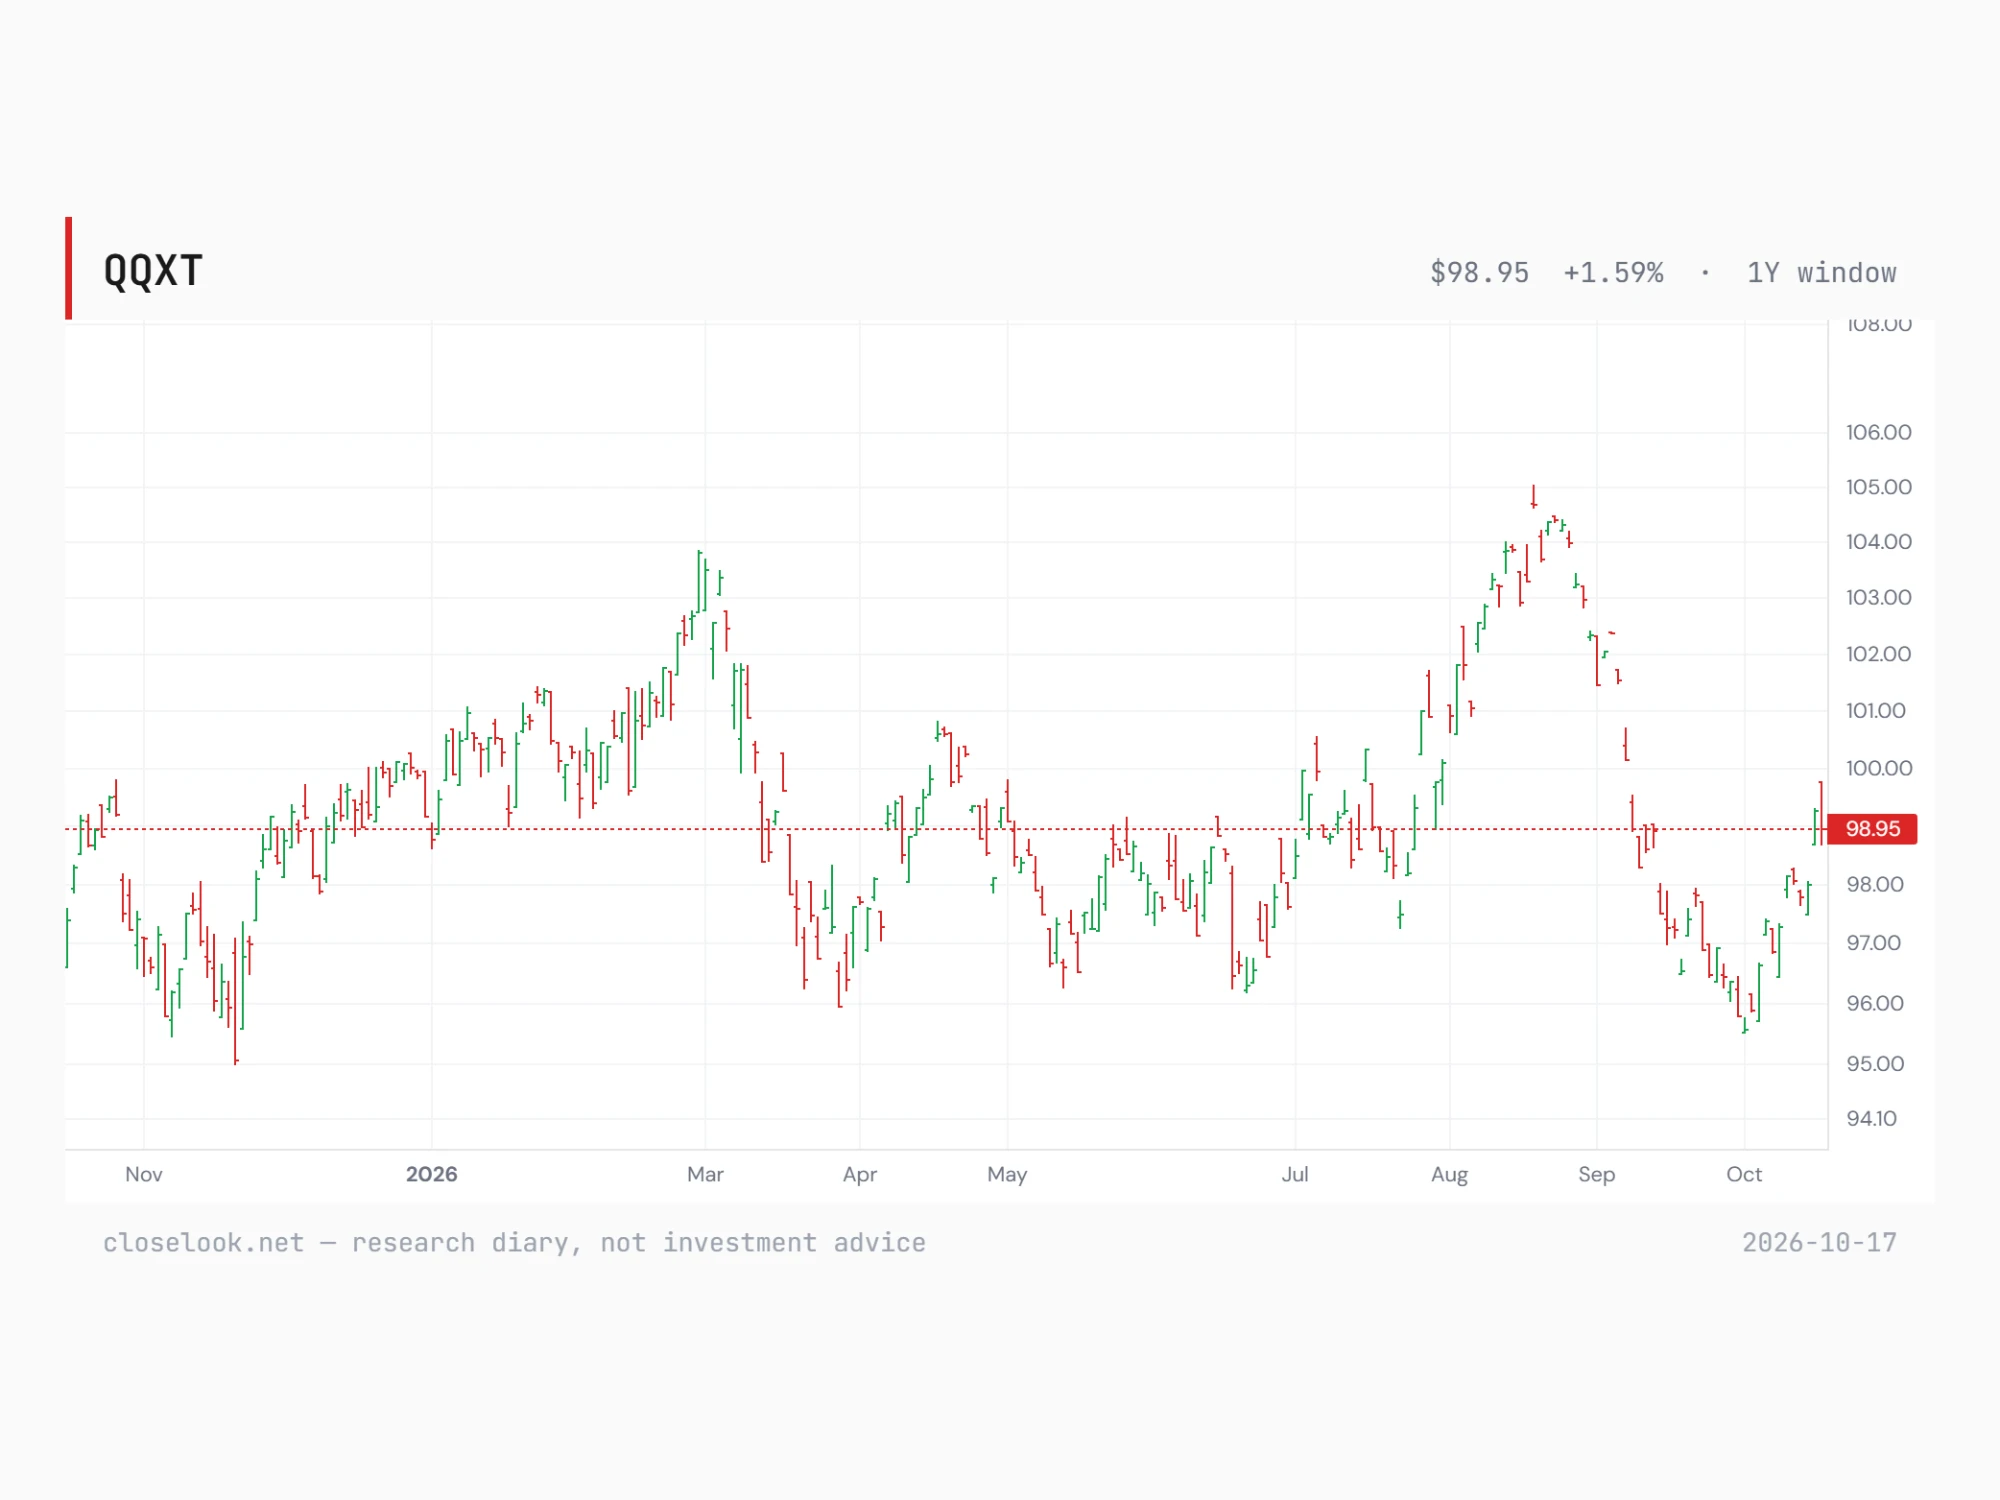
The editor's chart: the Nasdaq 100 without tech over one year — at 98.95, two weeks off its early-October low near 95.5 and still under its August high near 105.
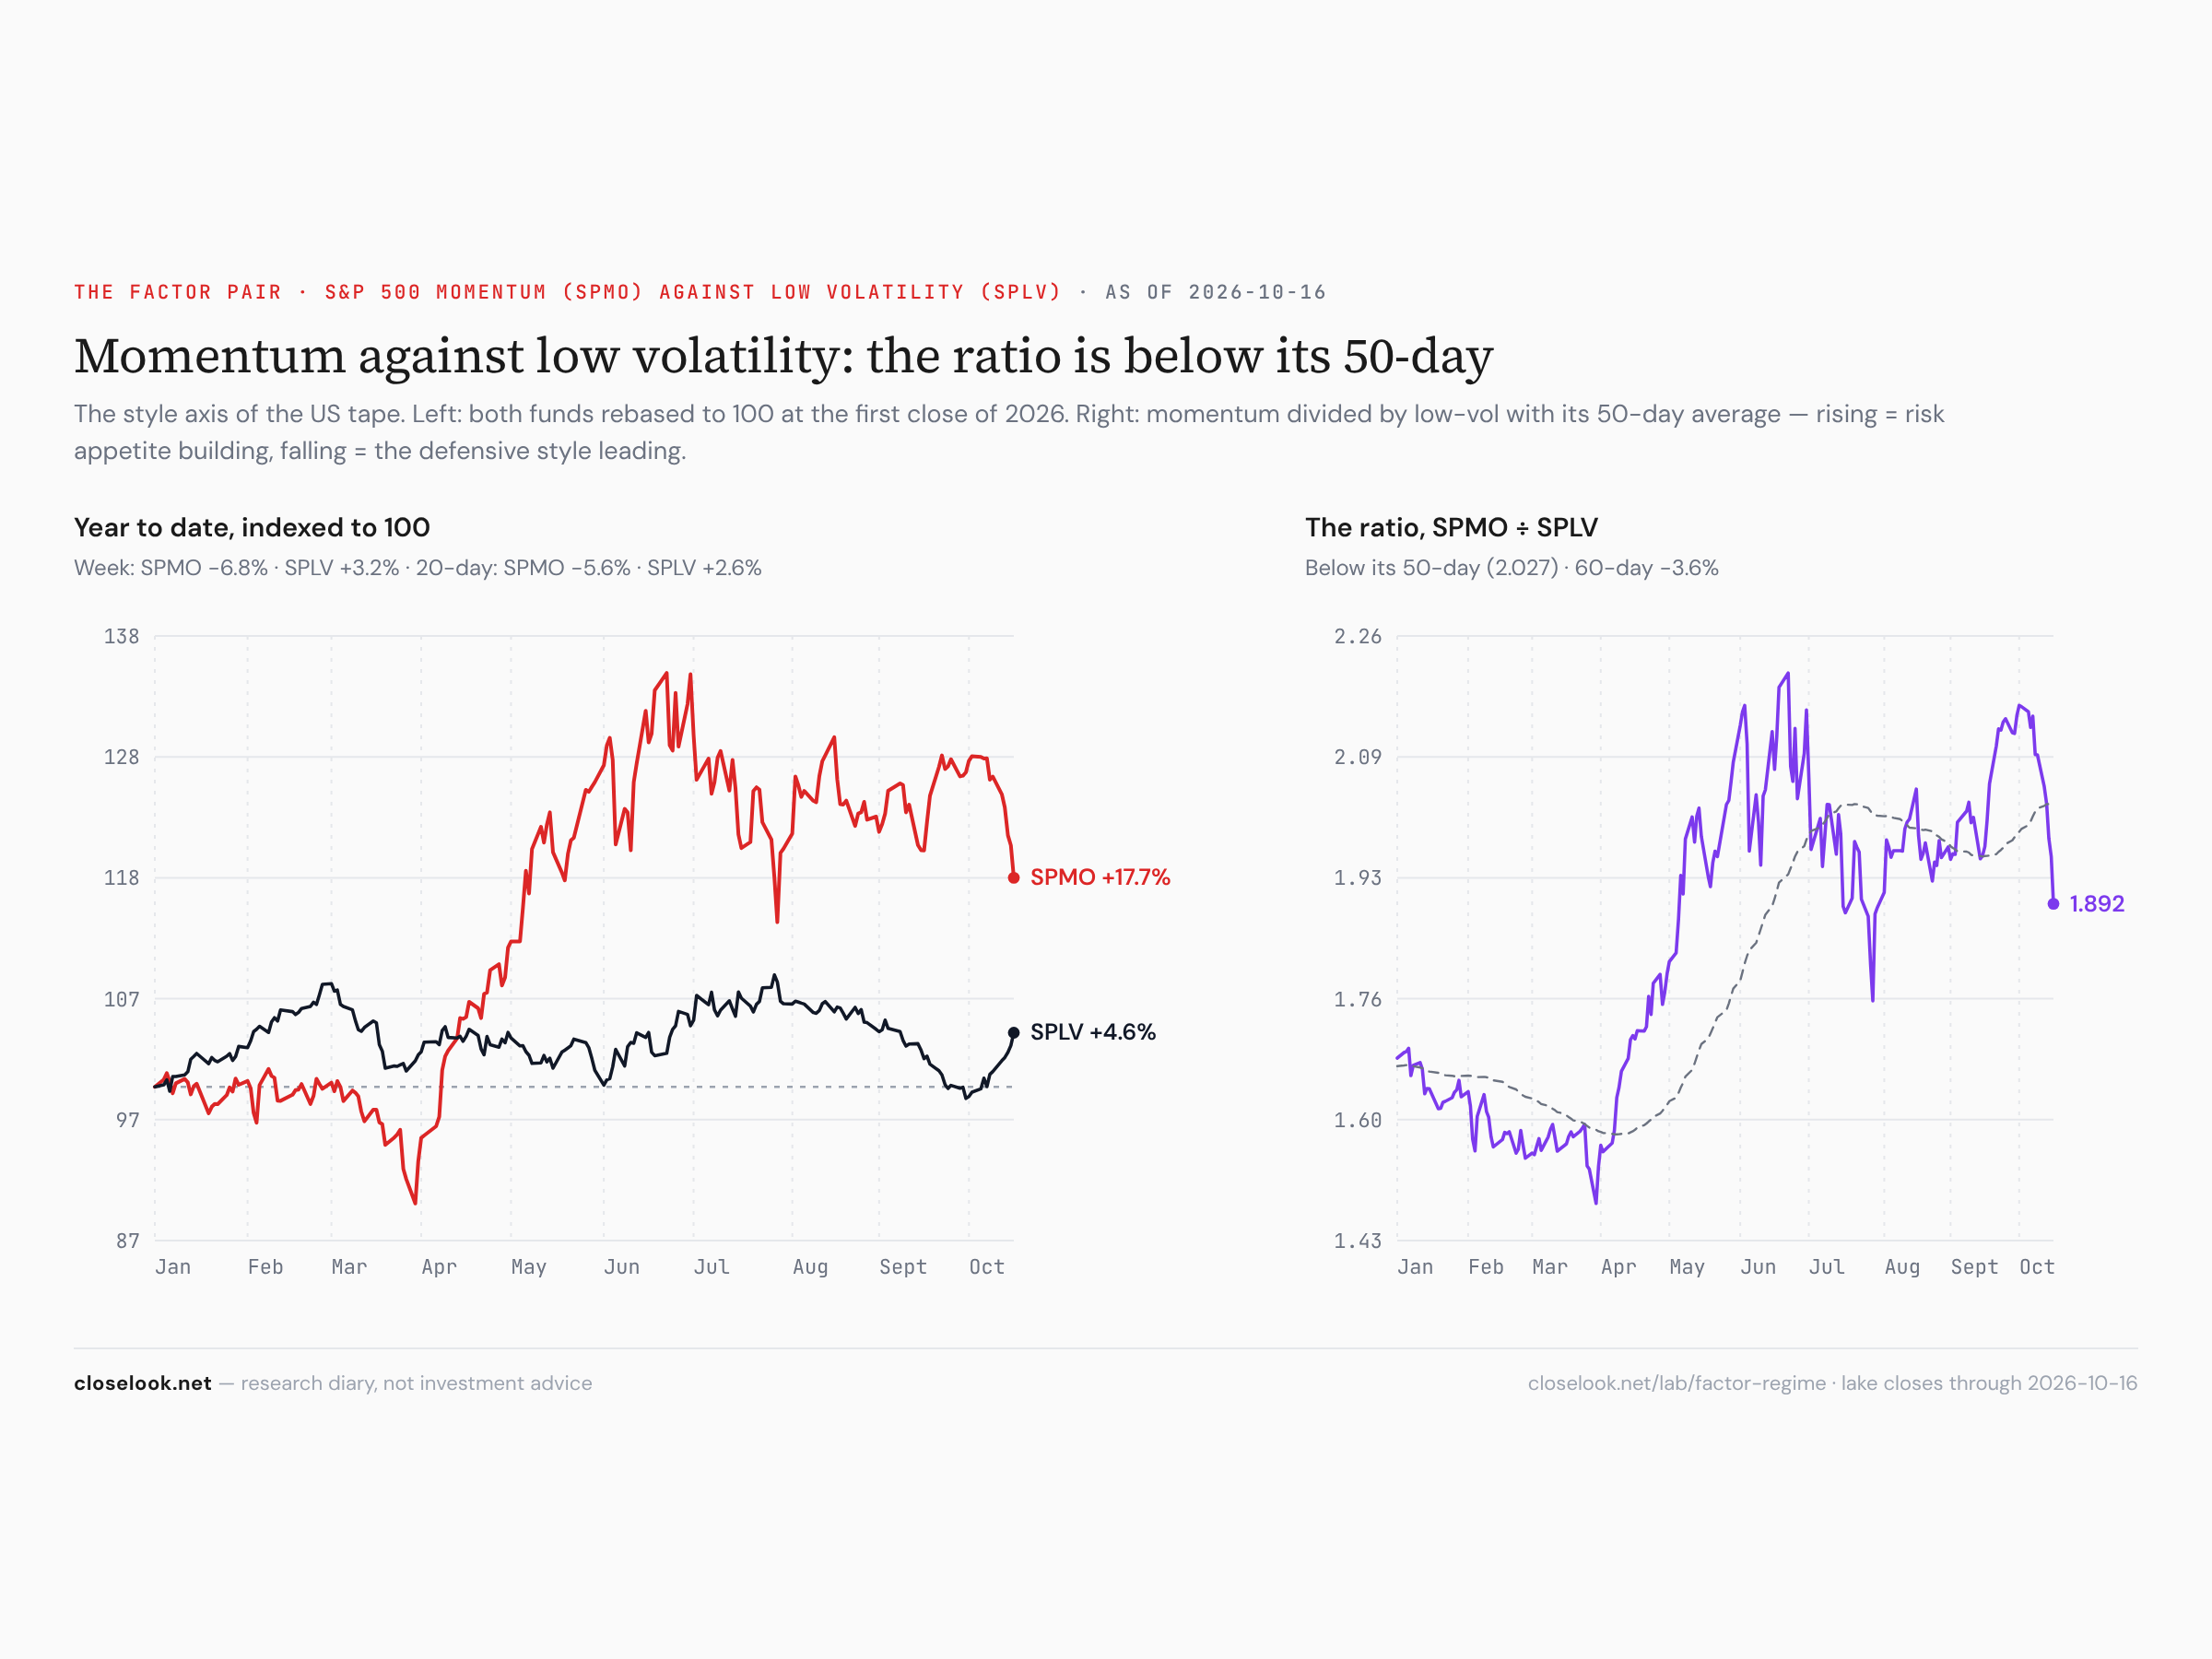
Momentum against low volatility — the turn. Momentum fell 6.79%, low volatility rose 3.24%. The ratio dropped below its 50-day average — from an indexed 166.4 to 150.2 — and the factor board now reads "defensive rotation — low-vol leading, regime-change watch." It is still in the 82nd percentile of its range. One week does not end a momentum regime; it does mark the first real crack in it.
The tech ETFs we carry
Nineteen of twenty-one red. XSD −12.48%, SMHX −12.14%, SOXX −11.80%, SMH −10.53%, cybersecurity −10.16%, software −7.39%, cloud −6.78%. Only defence tech (SHLD +2.69%) and gaming (ESPO +0.65%) rose. The software-over-semis ratio still rose 3.5% — software fell less — and is 48% above its June low, but this week software was not the shelter it was a week ago; it was the second wave of the selling.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| SHLD | Global X - Defense Tech | 61.48 | +2.69% | -1.90% | +2.65% | -16.63% | -5.11% |
| ESPO | VanEck Video Gaming and eSport | 100.76 | +0.65% | +4.35% | +9.92% | +6.15% | -2.75% |
| FINX | Global X - FinTech | 24.33 | -2.66% | -3.26% | -5.62% | -6.03% | -17.33% |
| SNSR | Global X - Internet of Things | 45.91 | -5.55% | -1.80% | -0.67% | +9.88% | +24.23% |
| FDN | First Dow Jones Internet Index | 283.9 | -5.78% | -1.65% | +4.00% | +8.69% | +5.47% |
| GRID | First NASDAQ Clean Edge Smart | 169.84 | -6.11% | -2.53% | -4.41% | -5.63% | +10.99% |
| CLOU | Global X - Cloud Computing | 28.07 | -6.78% | +0.18% | +15.85% | +43.14% | +24.09% |
| AIQ | Global X - Artificial Intellig | 62.02 | -6.88% | -1.57% | +4.57% | +15.95% | +21.94% |
| BOTZ | Global X - Robotics & Artifici | 33.02 | -6.93% | -4.90% | -7.06% | -10.05% | -8.86% |
| IGV | iShares Expanded Tech-Software | 104.34 | -7.39% | -0.59% | +11.36% | +23.68% | -1.28% |
| DTCR | Global X - Data Center & Digit | 25.78 | -7.83% | -5.50% | -6.39% | -6.25% | +22.18% |
| LIT | Global X - Lithium & Battery T | 64.05 | -8.15% | -8.30% | -6.99% | -22.18% | -1.25% |
| NLR | VanEck Uranium and Nuclear | 94.34 | -8.72% | -12.13% | -9.87% | -35.14% | -24.04% |
| ARKK | ARK Innovation | 81.65 | -8.89% | -1.84% | +6.50% | +5.57% | +6.15% |
| QTUM | Defiance Quantum | 137.14 | -9.81% | -4.28% | -4.02% | +9.56% | +25.06% |
| CIBR | First Nasdaq Cybersecurity | 98.82 | -10.16% | -1.48% | +7.54% | +49.91% | +38.31% |
| SMH | VanEck Semiconductor | 539.79 | -10.53% | -1.06% | -5.12% | +18.69% | +49.89% |
| SMHX | VanEck Fabless Semiconductor | 53.97 | -12.14% | -0.13% | -4.25% | +19.06% | +41.91% |
| XSD | S&P Semiconductor | 462.03 | -12.48% | -3.70% | -8.83% | +14.35% | +43.67% |
| DAPP | VanEck Digital Transformation | 15.58 | -12.57% | -16.42% | -10.36% | -15.97% | -5.75% |
| WTAI | WisdomTree Artificial Intellig | 37.74 | -14.54% | -6.79% | -5.20% | +12.56% | +29.51% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
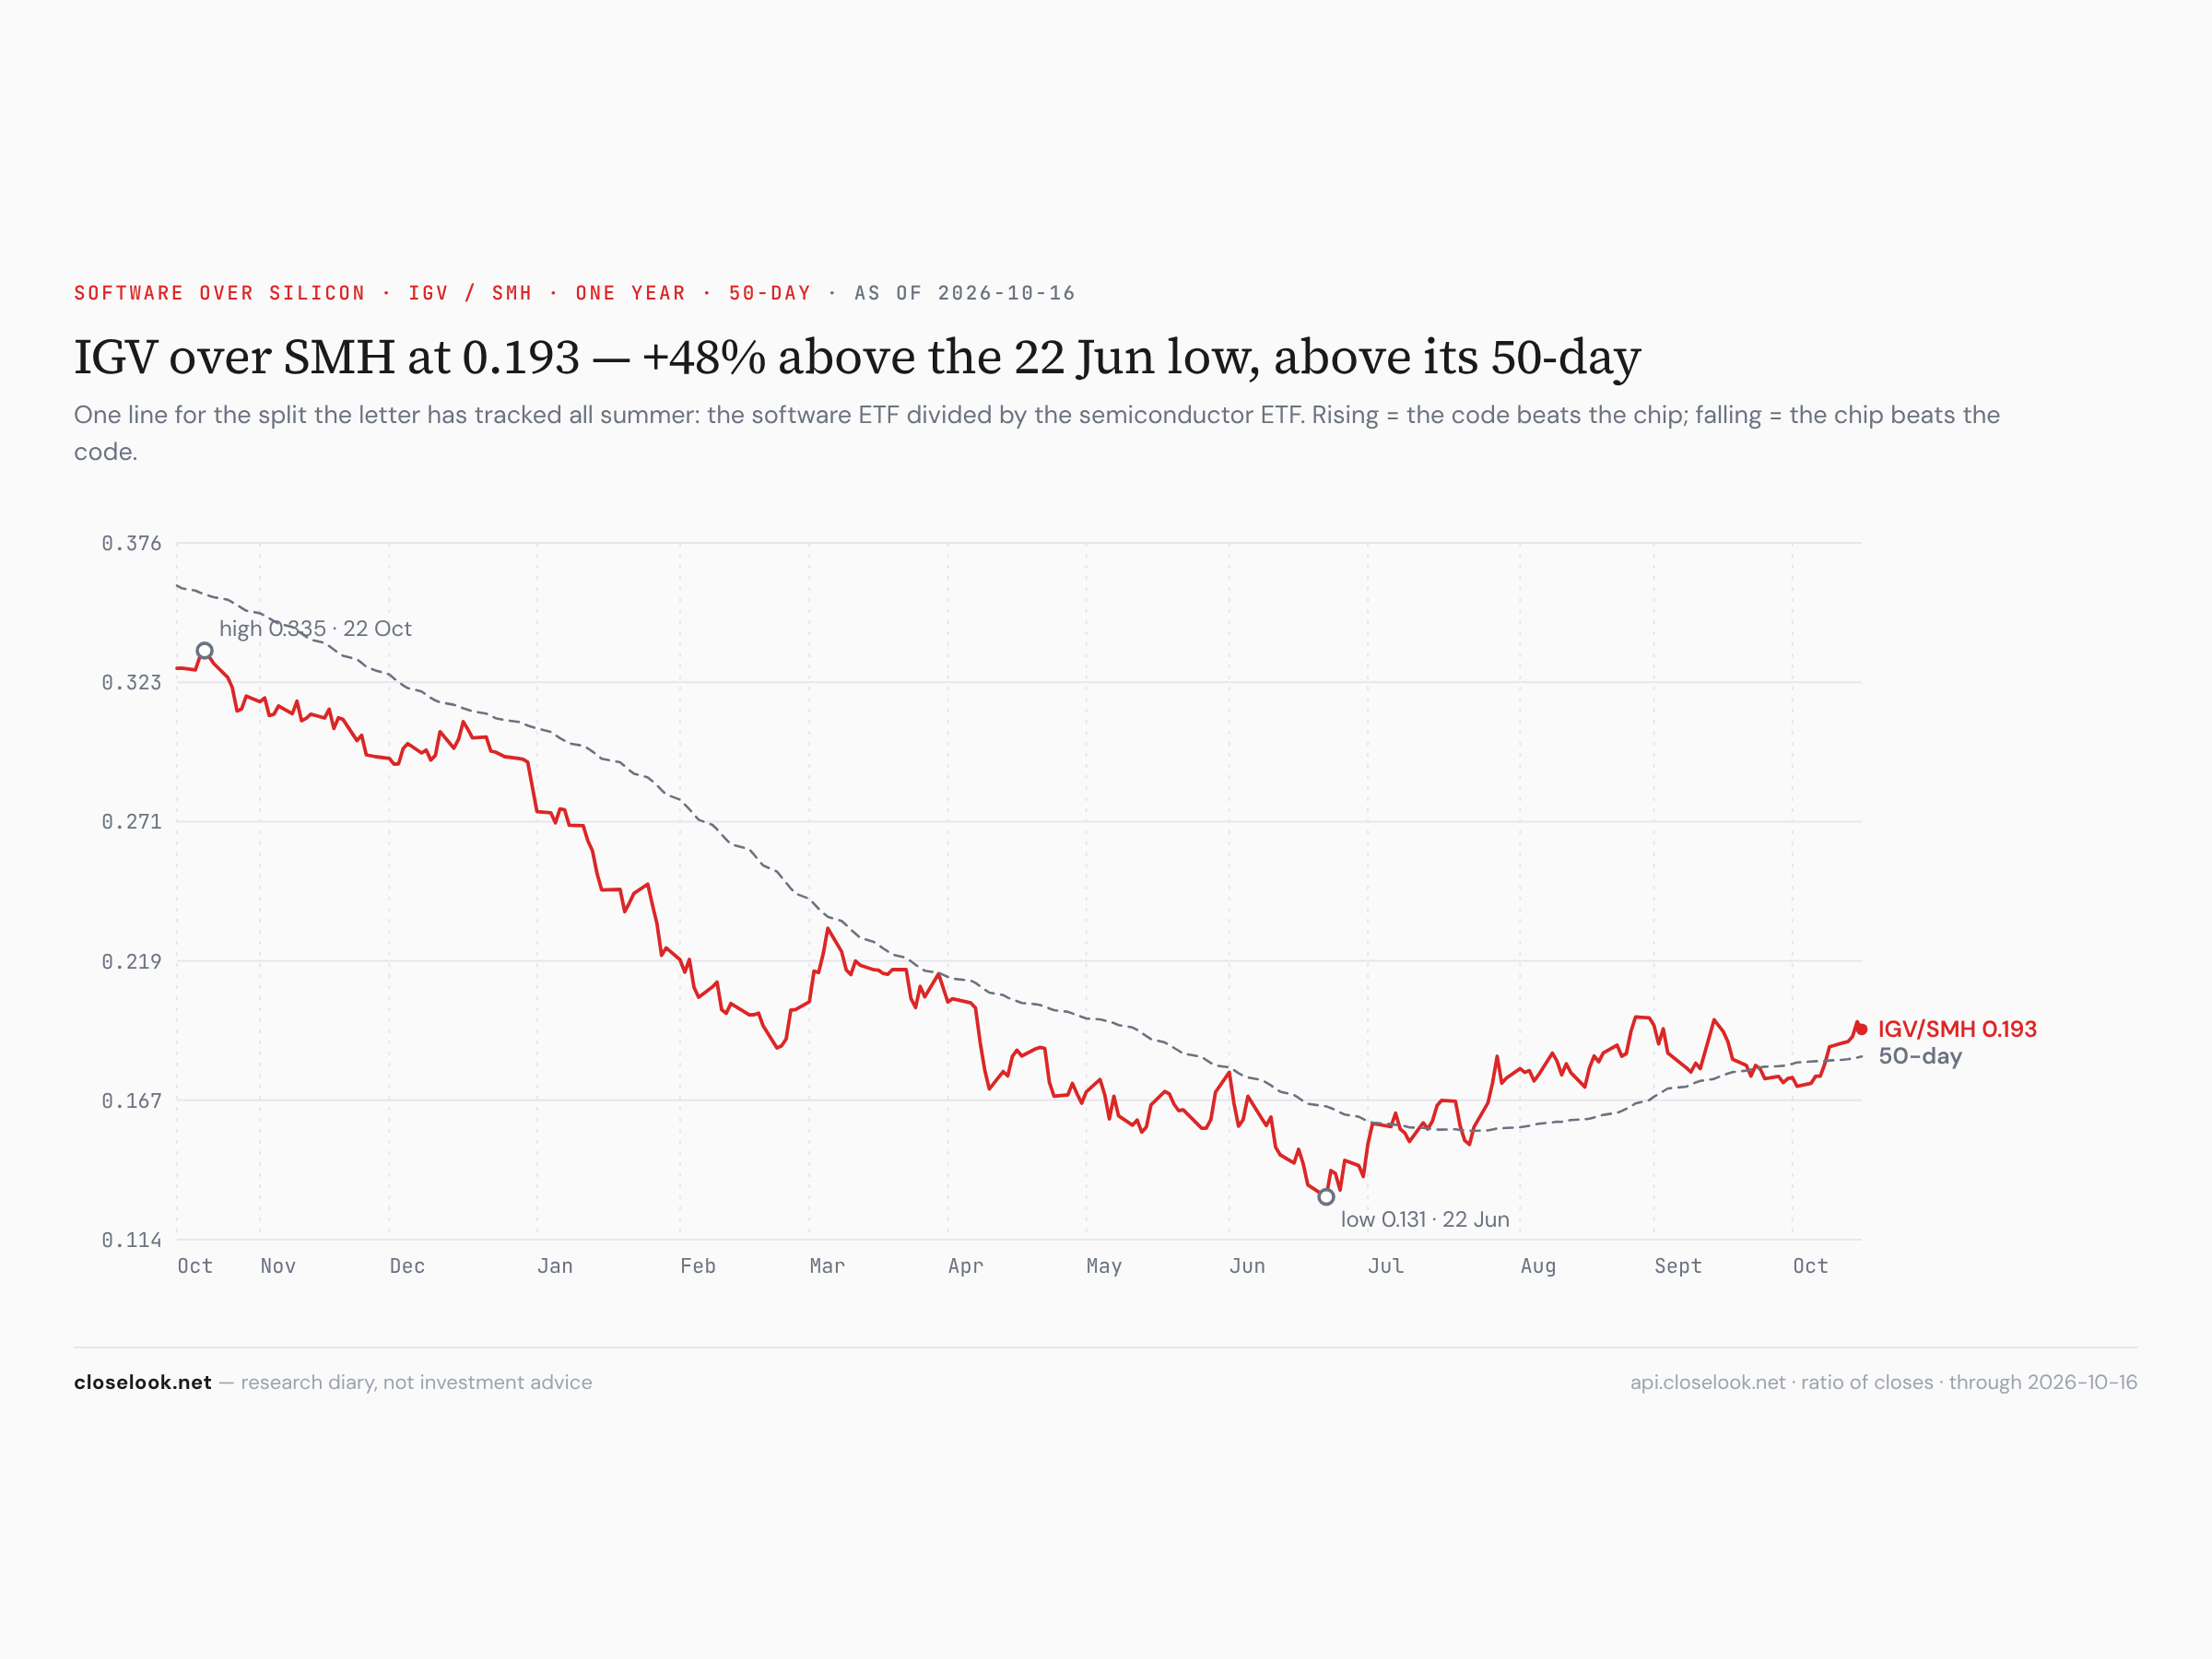
The names in one line each. On the way down: Applied Optoelectronics −31.1%, Aehr −28.4%, Coherent −25.5%, Lumentum −25.3%, Nebius −25.2%, CoreWeave −25.2%, Fabrinet −25.3%, HPE −25.0%, Credo −21.6%, Okta −19.3%, Applied Materials −19.3%, Palo Alto −18.3%, CrowdStrike −17.3%, Dell −17.6%, Snowflake −16.8%, Micron −14.6%, AMD −13.1%. Up: Intuit +7.4%, Eli Lilly +6.6%, Stryker +6.3%, Chevron +6.1%, Exxon +5.9%, Salesforce +5.1%, Veeva +4.8%, Amgen +4.3%, Apple +2.0%. The software names that rose were the out-of-favour ones — Intuit is still down 48% on the year; the ones that had led the year were sold.
The four indices: Dow, S&P 500, Nasdaq 100, Russell 2000
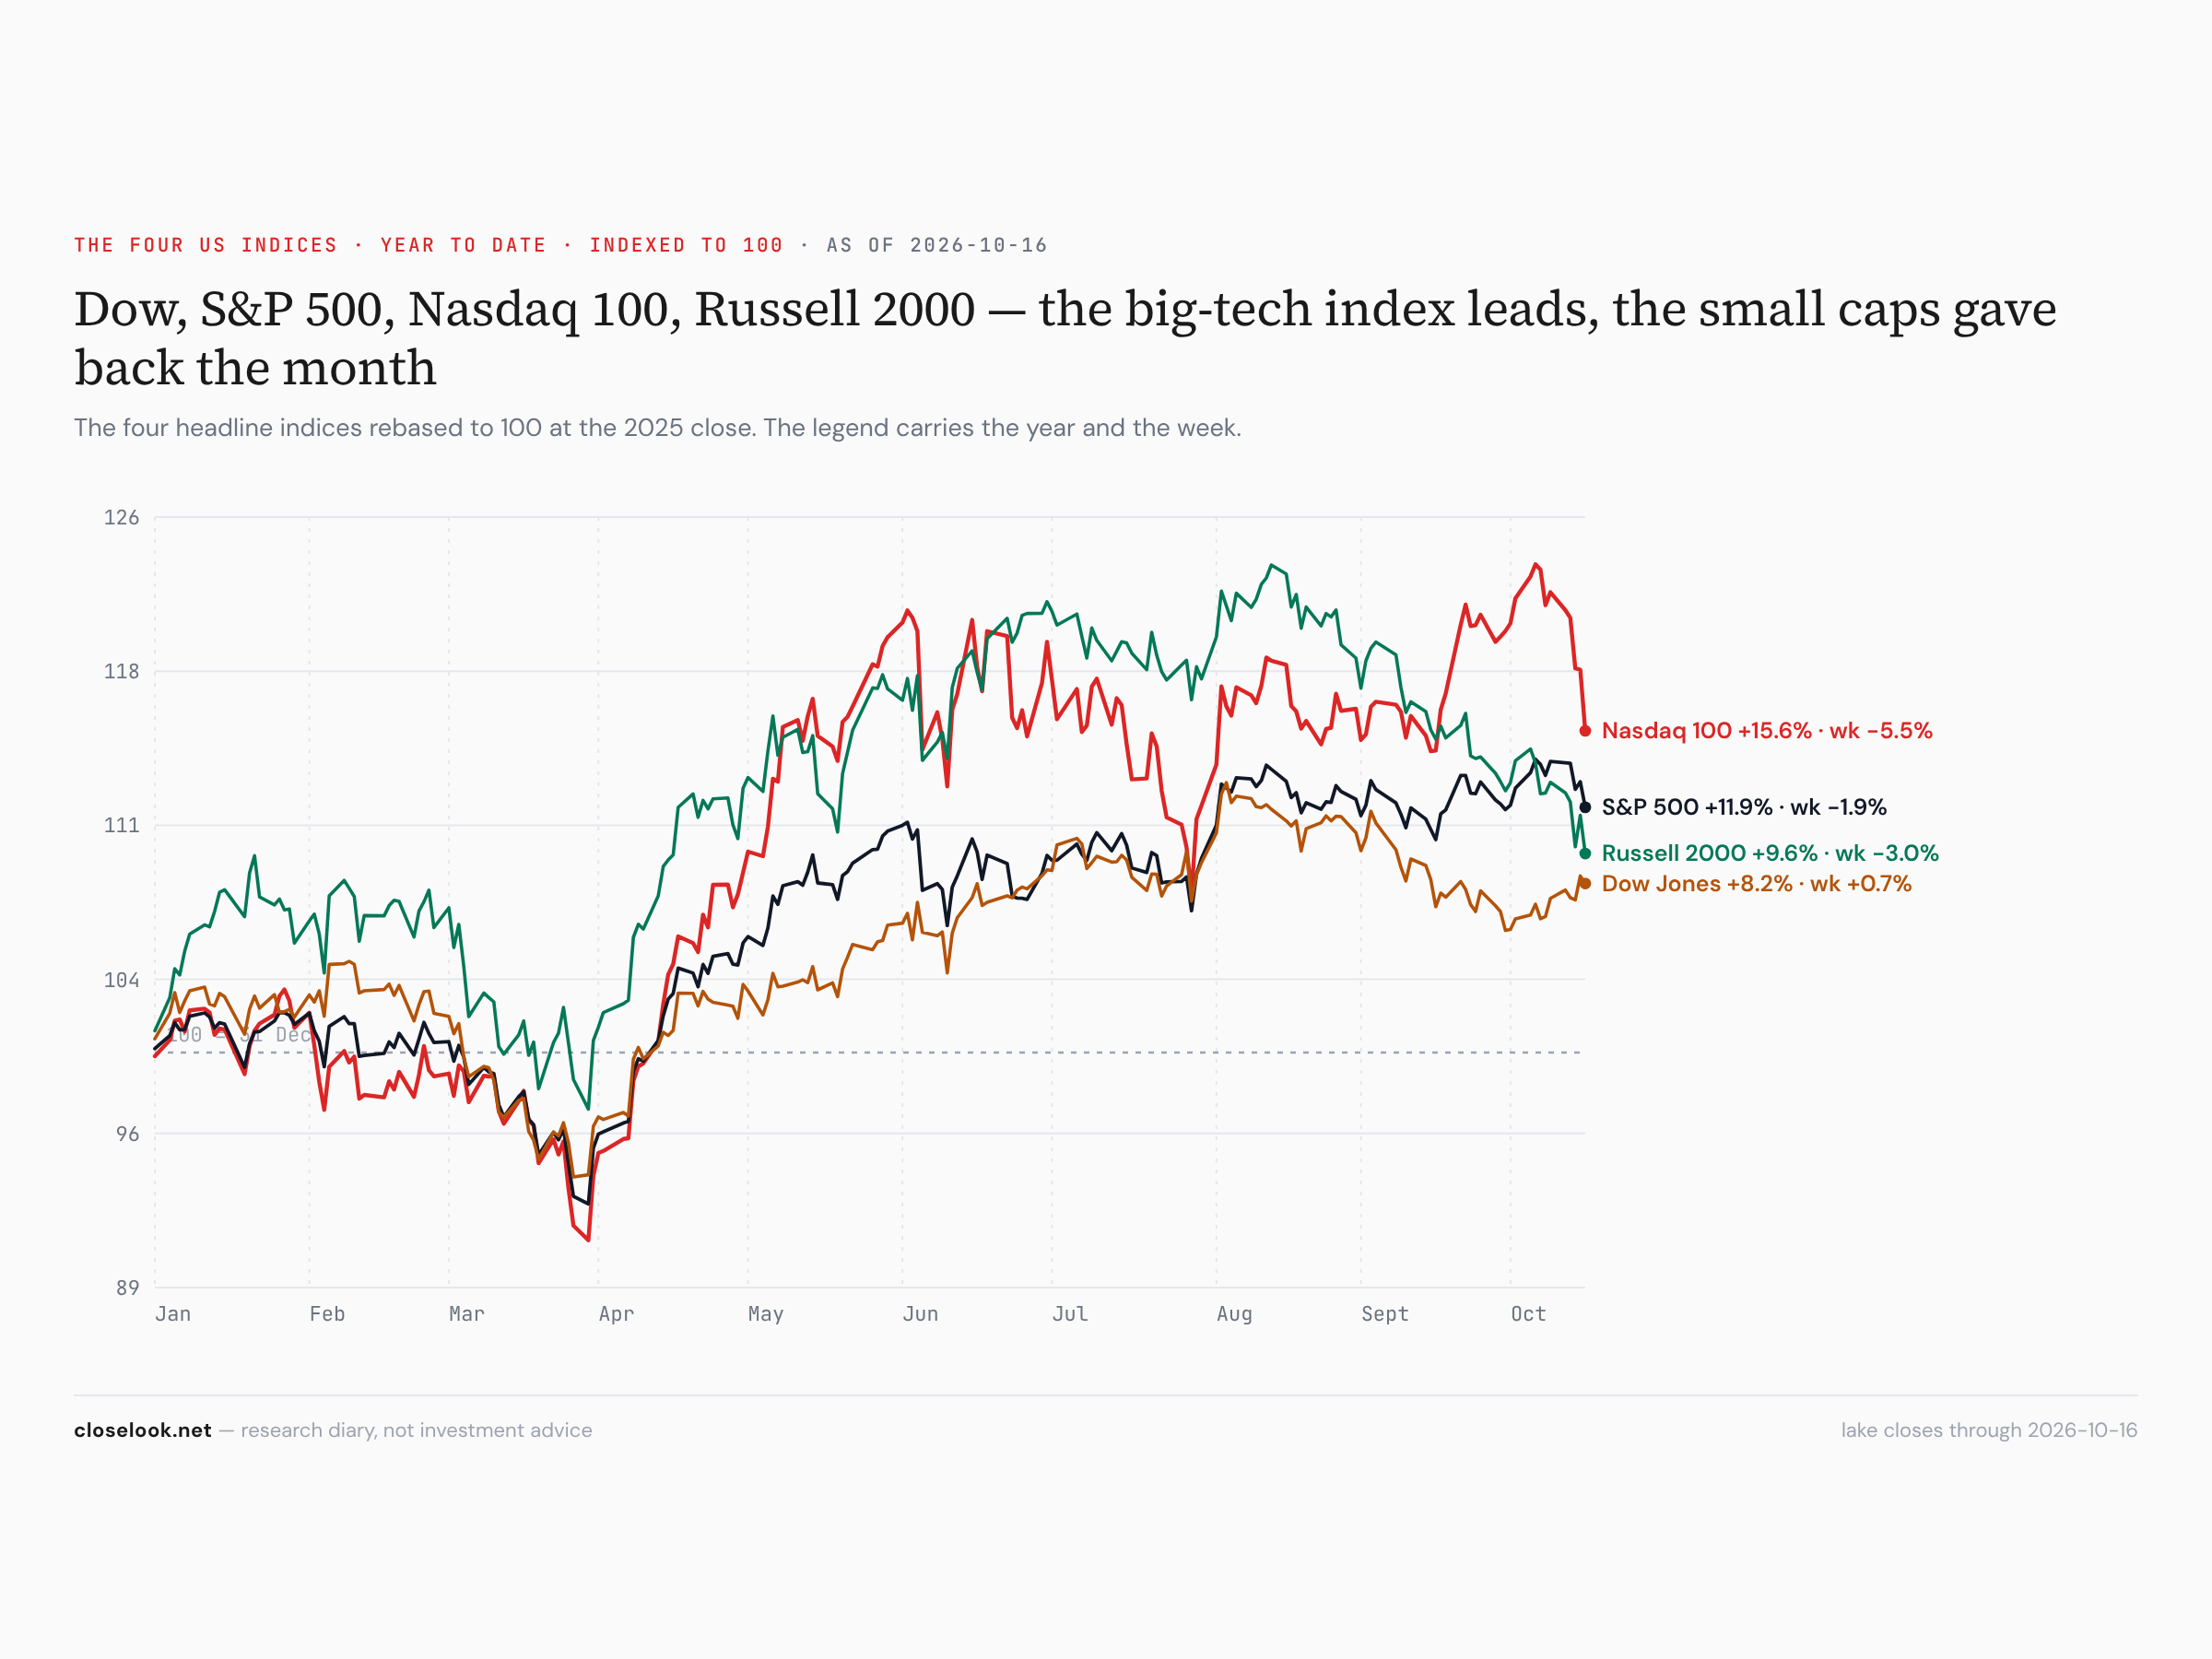
The S&P 500 −1.97%, the Nasdaq 100 −5.52%, the Russell 2000 −3.05%. The Dow held up best: it gained 1.1% on Thursday and was still green at midday on Friday while the Nasdaq fell, because it holds more banks, health care and consumer names and fewer chips. The S&P is 2.0% under its 6 October record, the Nasdaq 6.6% under its own. The Russell is 6.4% under its 50-day average.
The Treasury curve, one month to thirty years
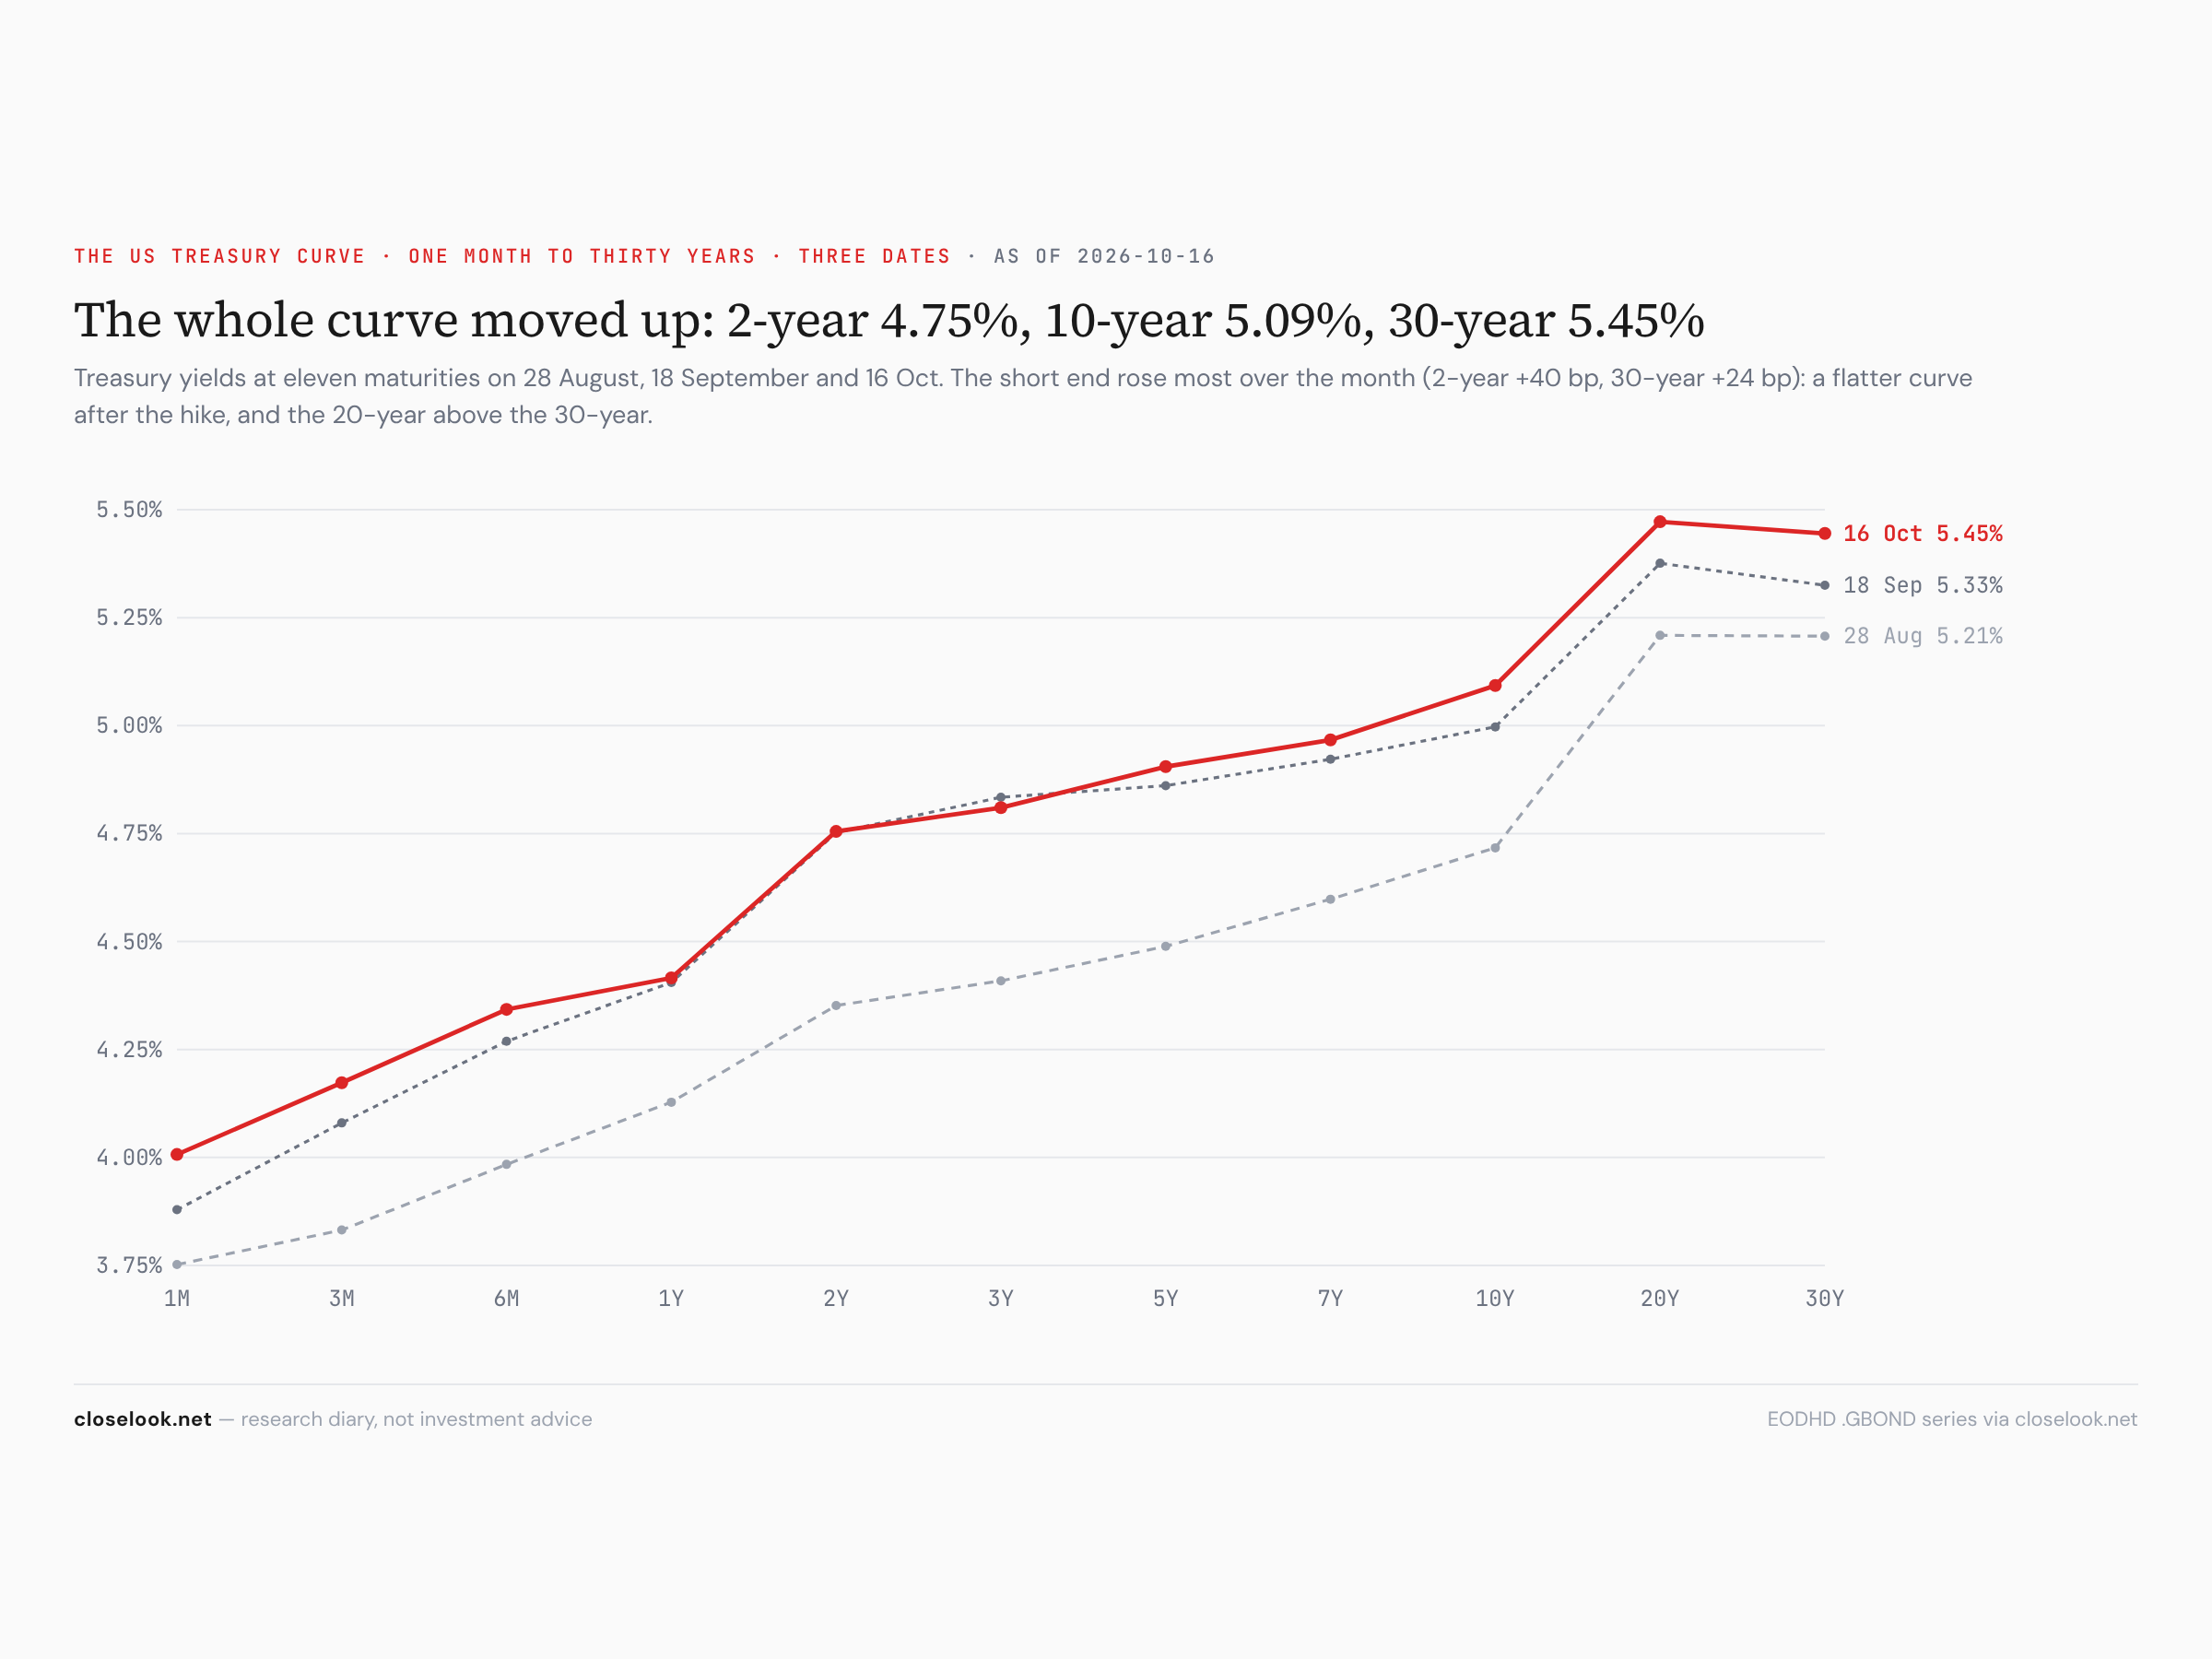
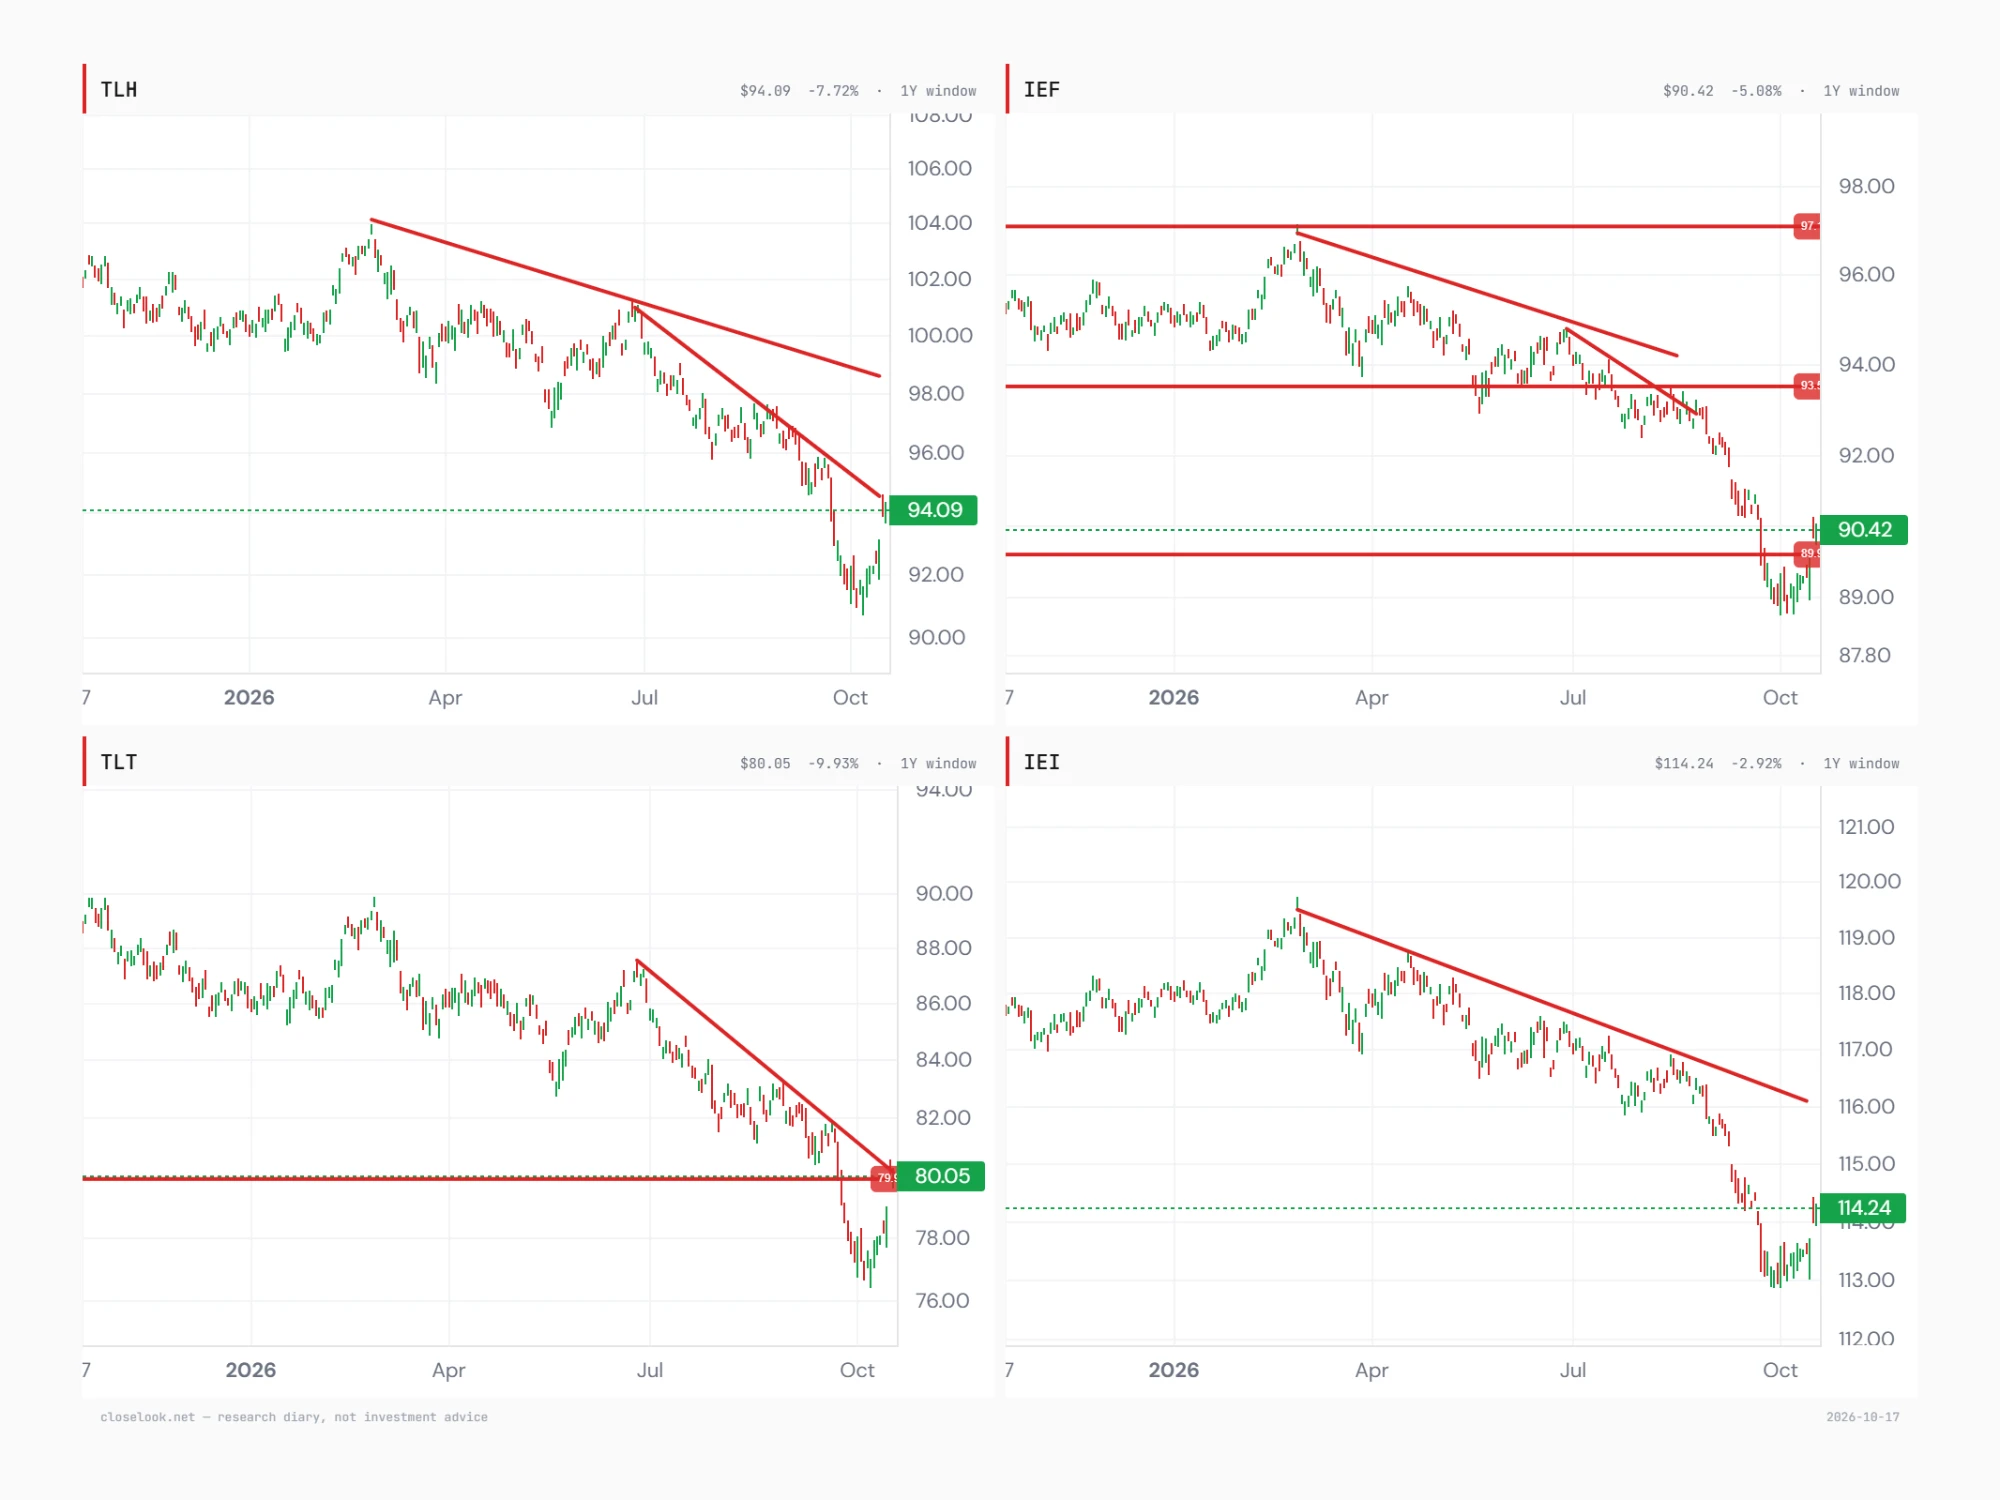
The ten-year yield fell from 5.24% to 5.10% on the week, the thirty-year to about 5.43%, the two-year to about 4.72%. It fell in a week of hot inflation numbers: consumer prices rose 3.7% on the year in September, core 2.6%, both above forecast (Wednesday); producer prices jumped 1.3% in the month (Thursday). The bond market looked past them — the ten-year touched 5.24% on Wednesday and fell to 5.10% on Thursday, as consumer spending outside food and energy stalled. The long-bond fund TLT rose 2.65% to 80.05, with a gap higher on Thursday on the heaviest volume of the month.
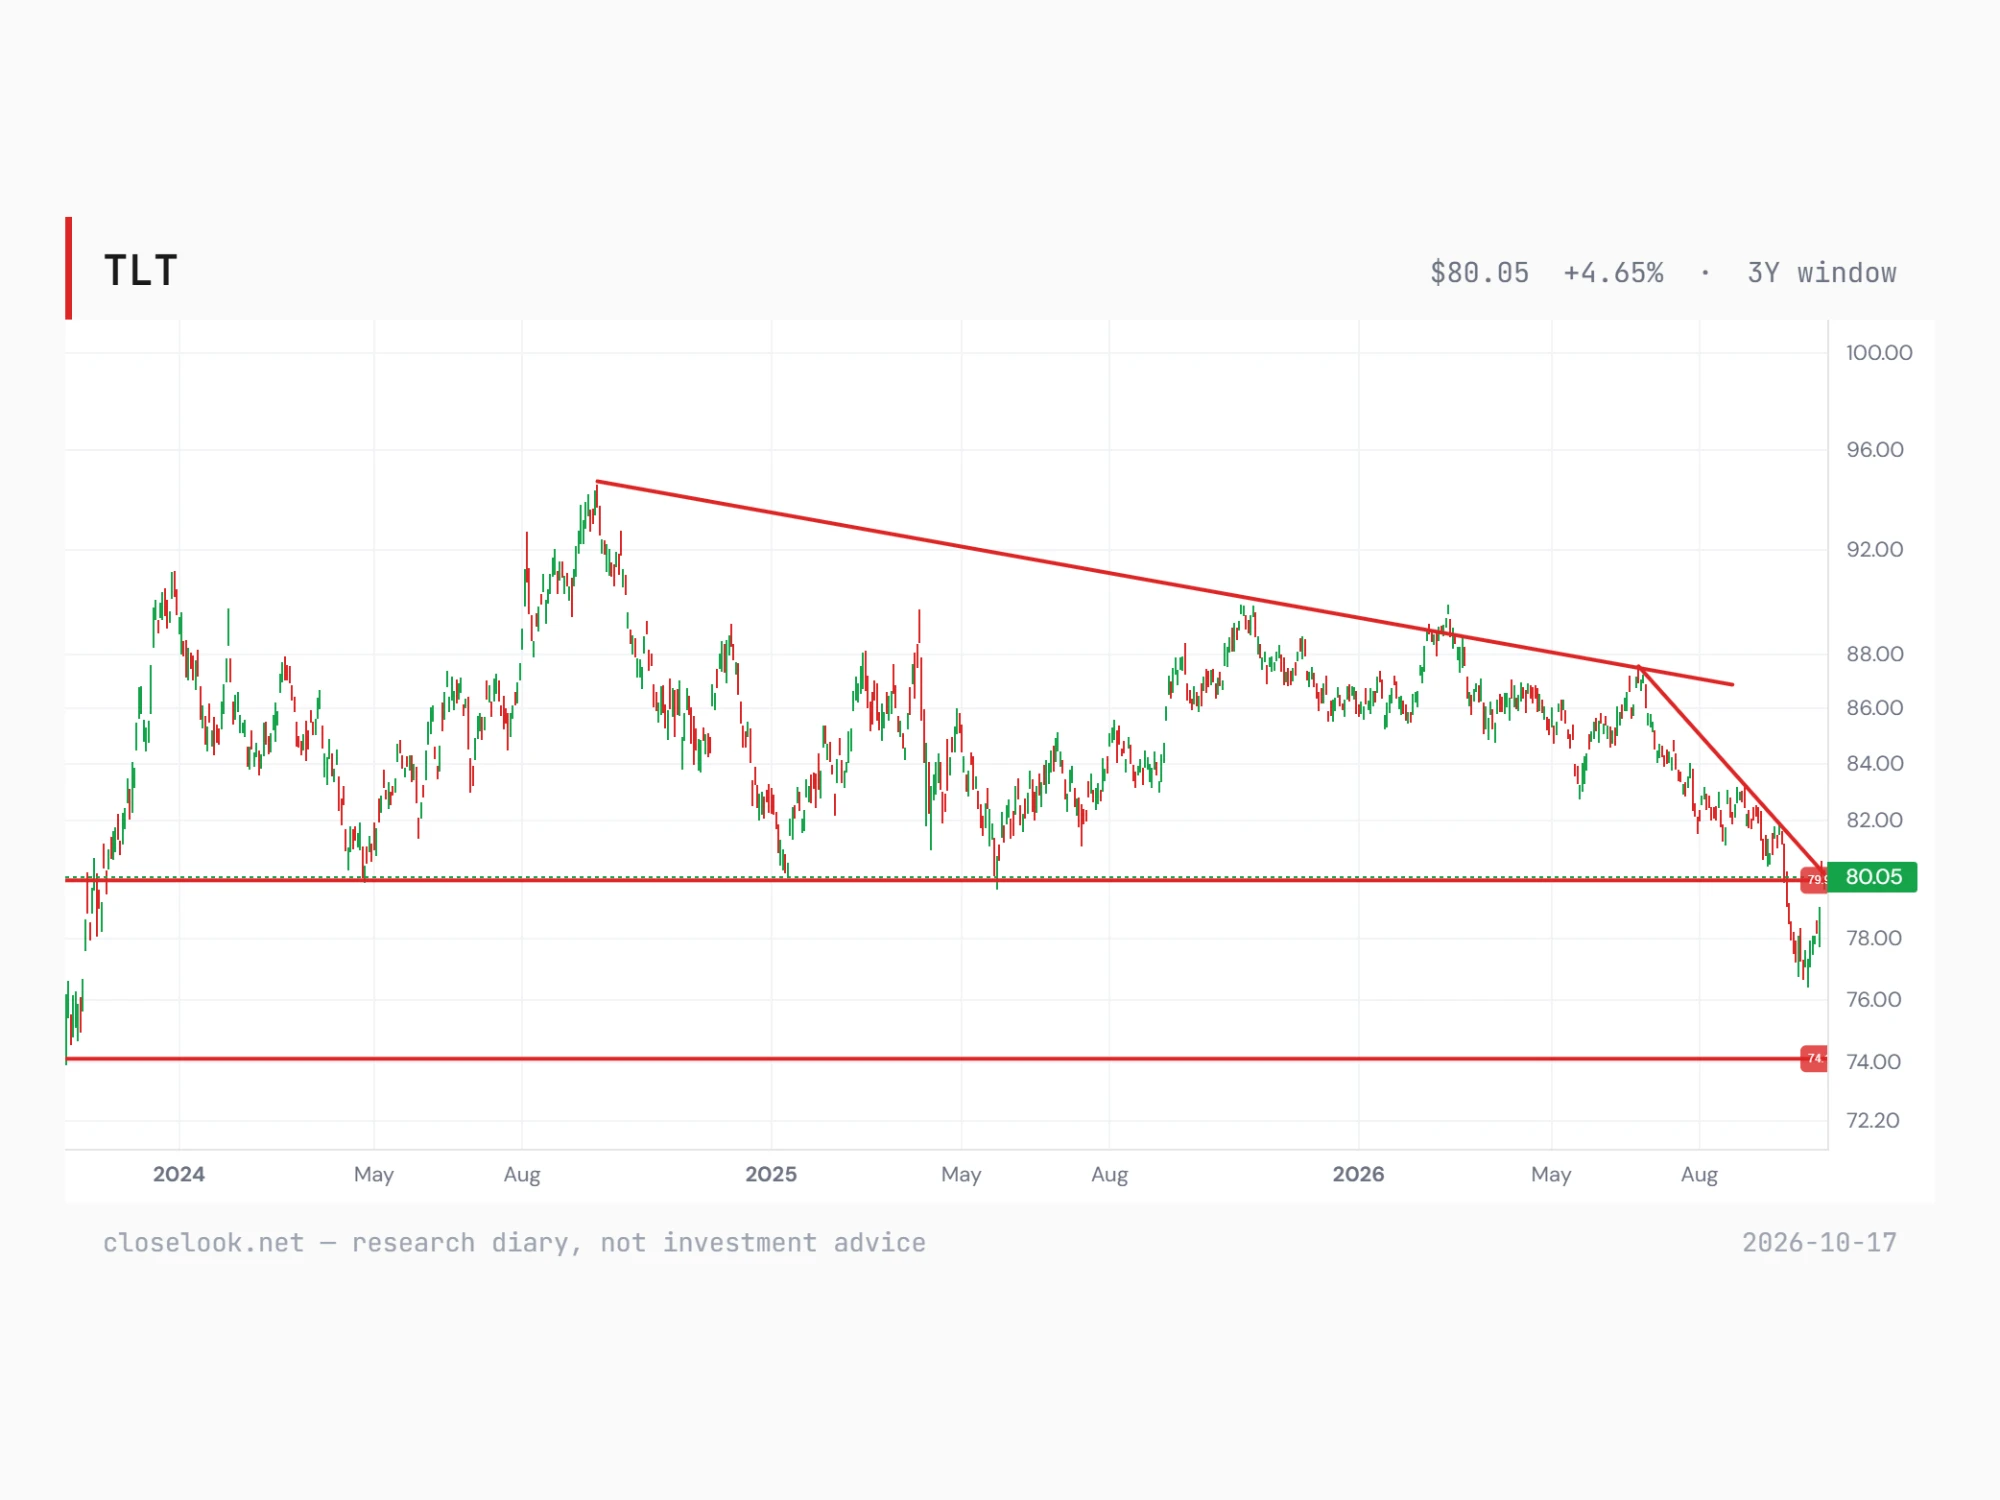
The editor's read of the bond chart: TLT may have made an initial breakaway gap. On Thursday the fund opened at 80.47 after closing at 78.89 the day before, and the day's low of 79.93 never came back to Wednesday's high of 79.01 — a gap of almost a dollar, on 86.7 million shares, the heaviest volume of the month. Friday traded down to 79.67 and closed at 80.05, so the gap is still open. That close sits on the two lines on his three-year chart: the falling line from the 29 June high (87.45) and the 79.9 floor the fund held in 2024 and 2025 and first closed under on 24 September. 74 is the line below. His point: a breakaway gap starts a move; if the move is real, a second gap higher — a running gap — may follow soon, and the next test is a close clearly above the falling line. All four Treasury funds gapped higher on Thursday and held it on Friday: TLH (10–20 years) at 94.09 on its own falling line, IEF (7–10 years) at 90.42 back above its 89.9 line with 93.5 next, IEI (3–7 years) at 114.24.
The dollar
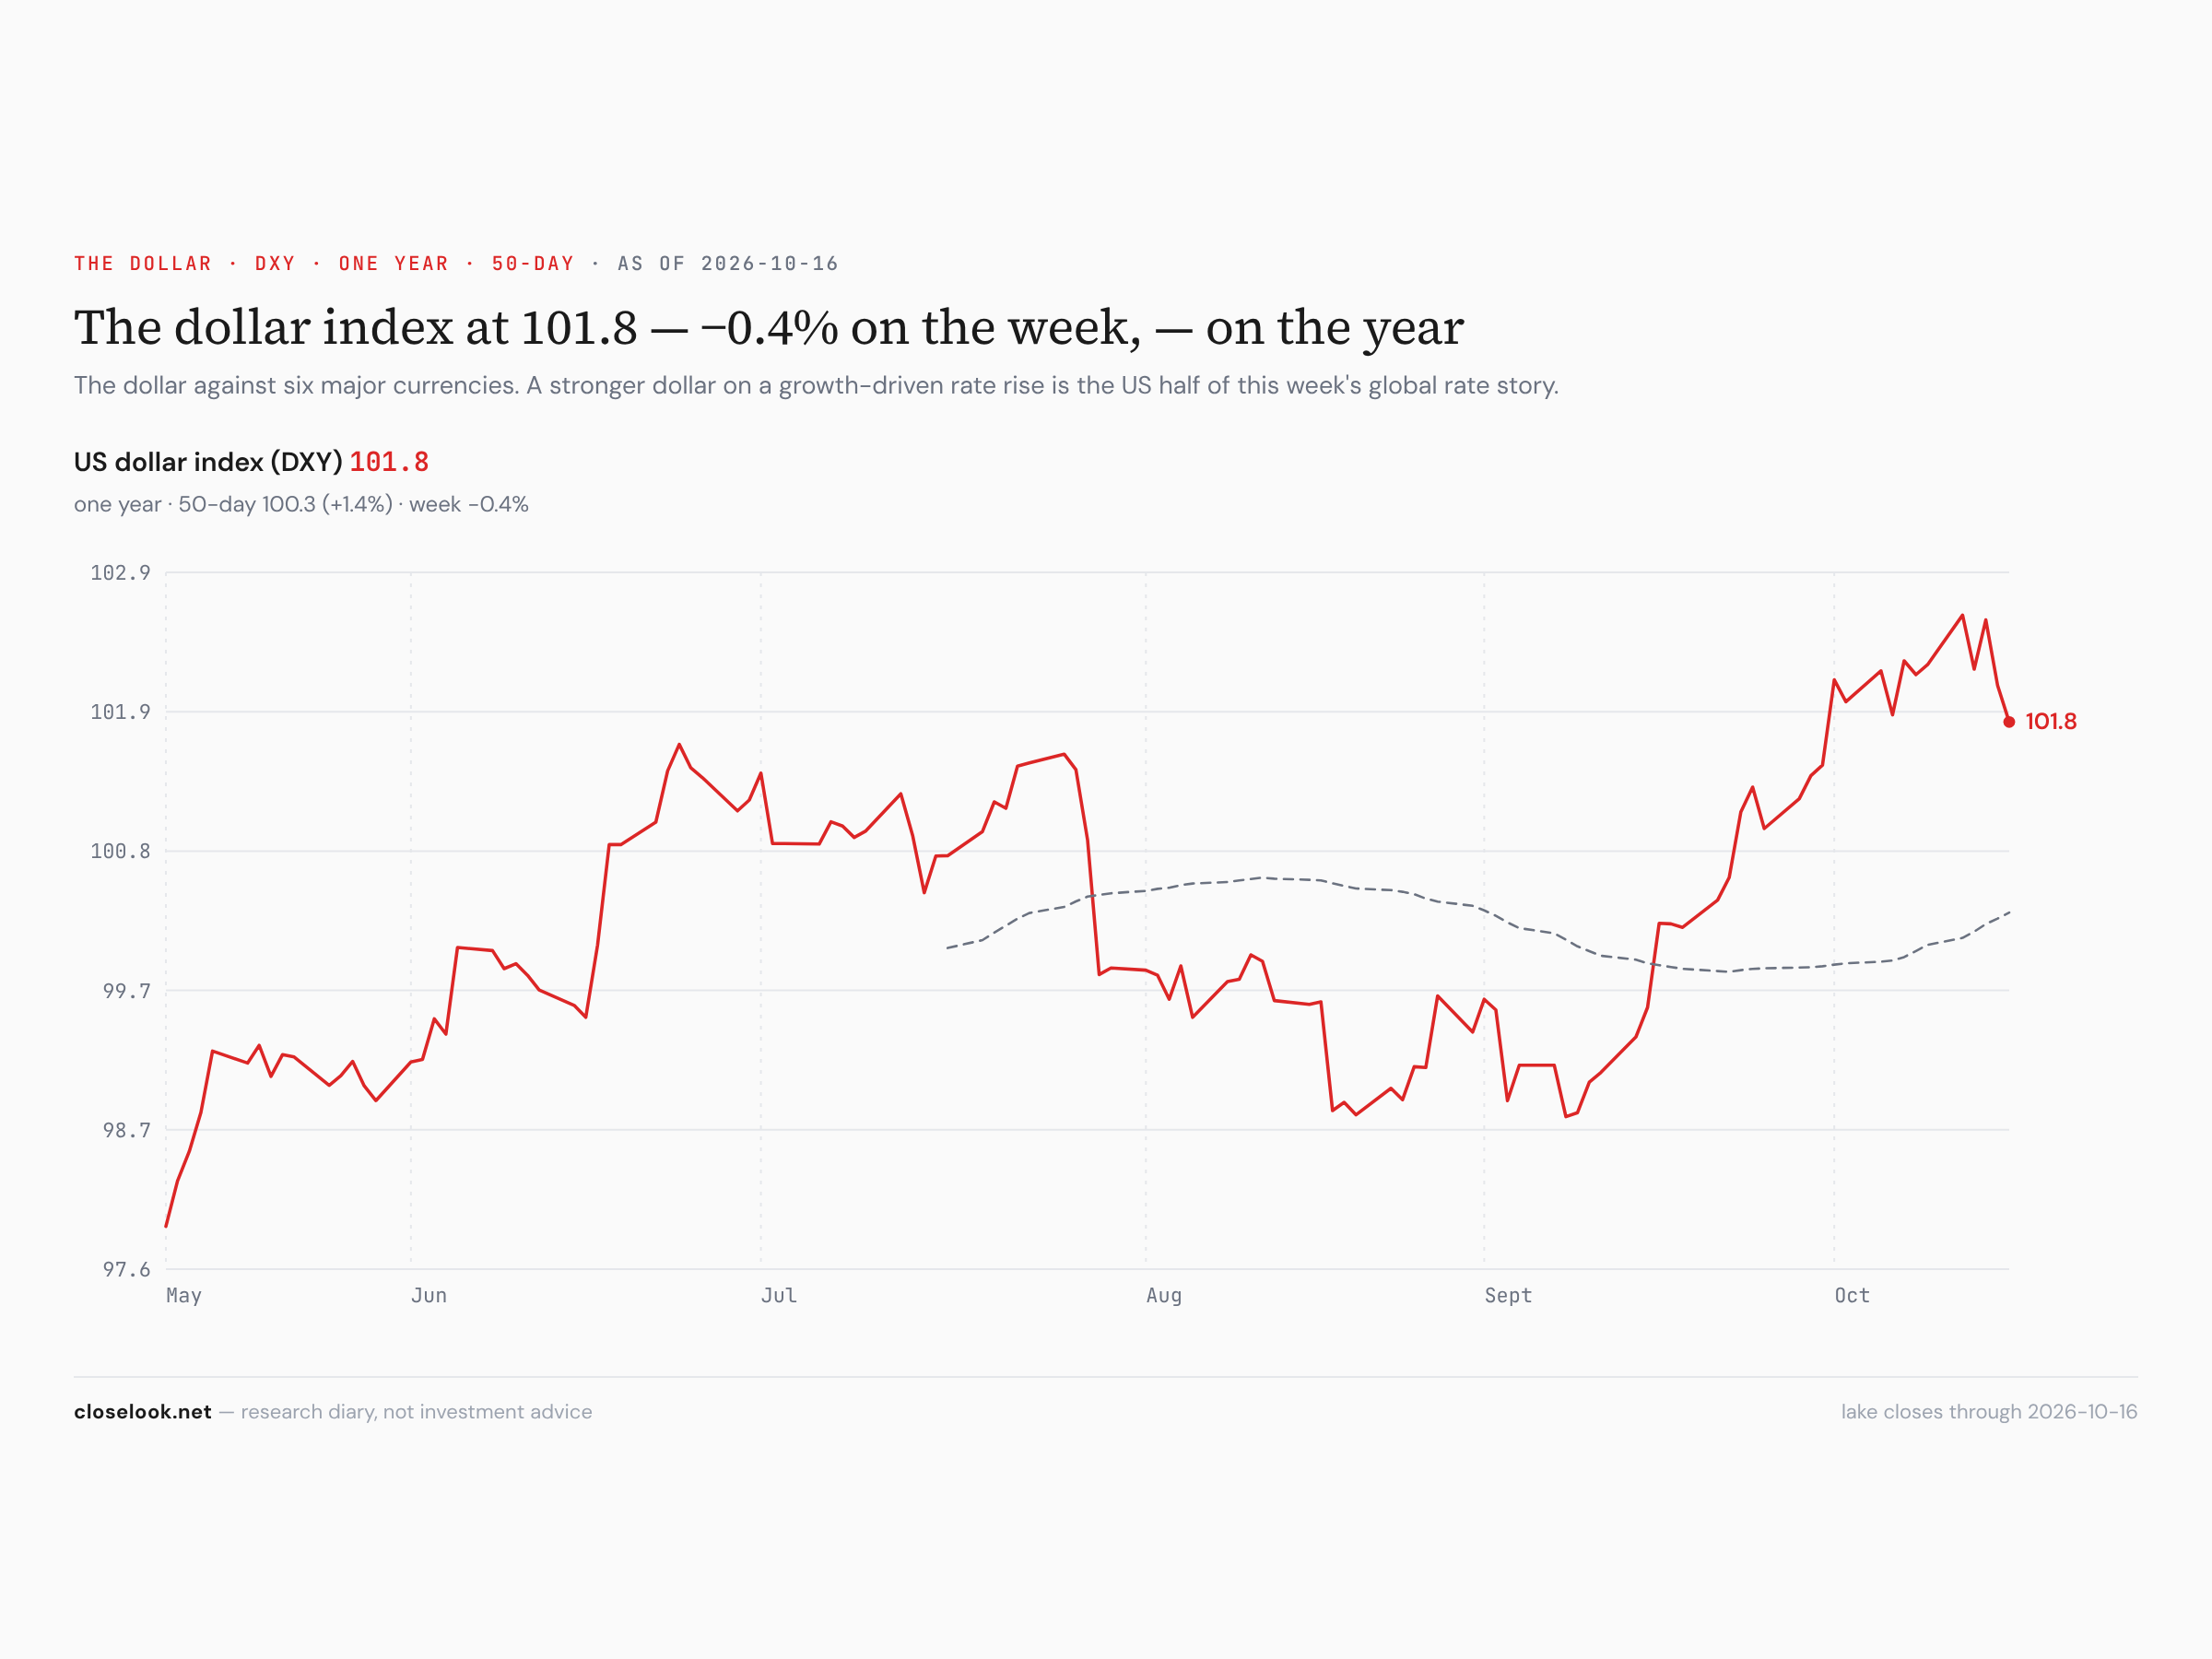
The dollar fund slipped 0.34% to 28.92 while the yields fell. A softer dollar and lower long yields in the same week is what a market pricing slower growth looks like.
2 · The State
The week, in order. Monday: Korea's market, back from two days off, fell 3.5% to catch up with the US chip selling; in New York memory and optics were sold again — Lumentum −7.7% and SanDisk −6.5% at midday — while Meta rose 3.8%. Tuesday: the Kospi broke its 18-month uptrend; J&J and Citi fell after beating, JPMorgan recovered after missing; the chip fund closed back under its 50-day. Wednesday: hot inflation, the ten-year at 5.24%, the chip fund −3.7% and 20% under its June high, software −2.4%, Oracle −7.5%, AMD −4.9%; health care +2.0% the only shelter. ASML reported a record quarter and said it is sold out into 2028. Thursday: TSMC beat but called itself "prudent" on 2027; the chip fund −2.0%, Dell −7.7%; software was bought, ServiceNow +5.4%; the ten-year fell to 5.10%; health care +2.5% led again. Friday: the whole complex sold — chips −2.1% for the eighth day, software −4.3%, CrowdStrike, Snowflake and Palo Alto −7% — while the Dow stayed green and the money stayed in staples, banks and utilities.
The mechanism, named: profit-taking in the winners, not a flight from stocks. A sell-everything week takes the equal-weight S&P down with the index; this one did not. The S&P fell 2%, the average stock rose. The money went from the places it had made the most this year — chips +86% on the year before the week, the AI builder index +103% — to the places it had made the least: staples, health care, energy. Two things pushed it. The AI supply chain got its first hard question about 2027: TSMC prudent, an earlier report that put OpenAI's revenue nearer 50 billion dollars than 70 billion. And a peak in rates with slower growth behind it — the ten-year off its 5.31% high of 5 October in a week of hot prices — favours companies that grow without a strong economy.
The channels, said plainly. The rising line from the 30 March low held every dip for six and a half months: in June, in July, in September. A break of it after the chips fell 25% from their June high is not a crash; it is the end of the easy part of the trend. What it changes is the stance — a dip that breaks the line is not bought the same way as a dip that holds it.
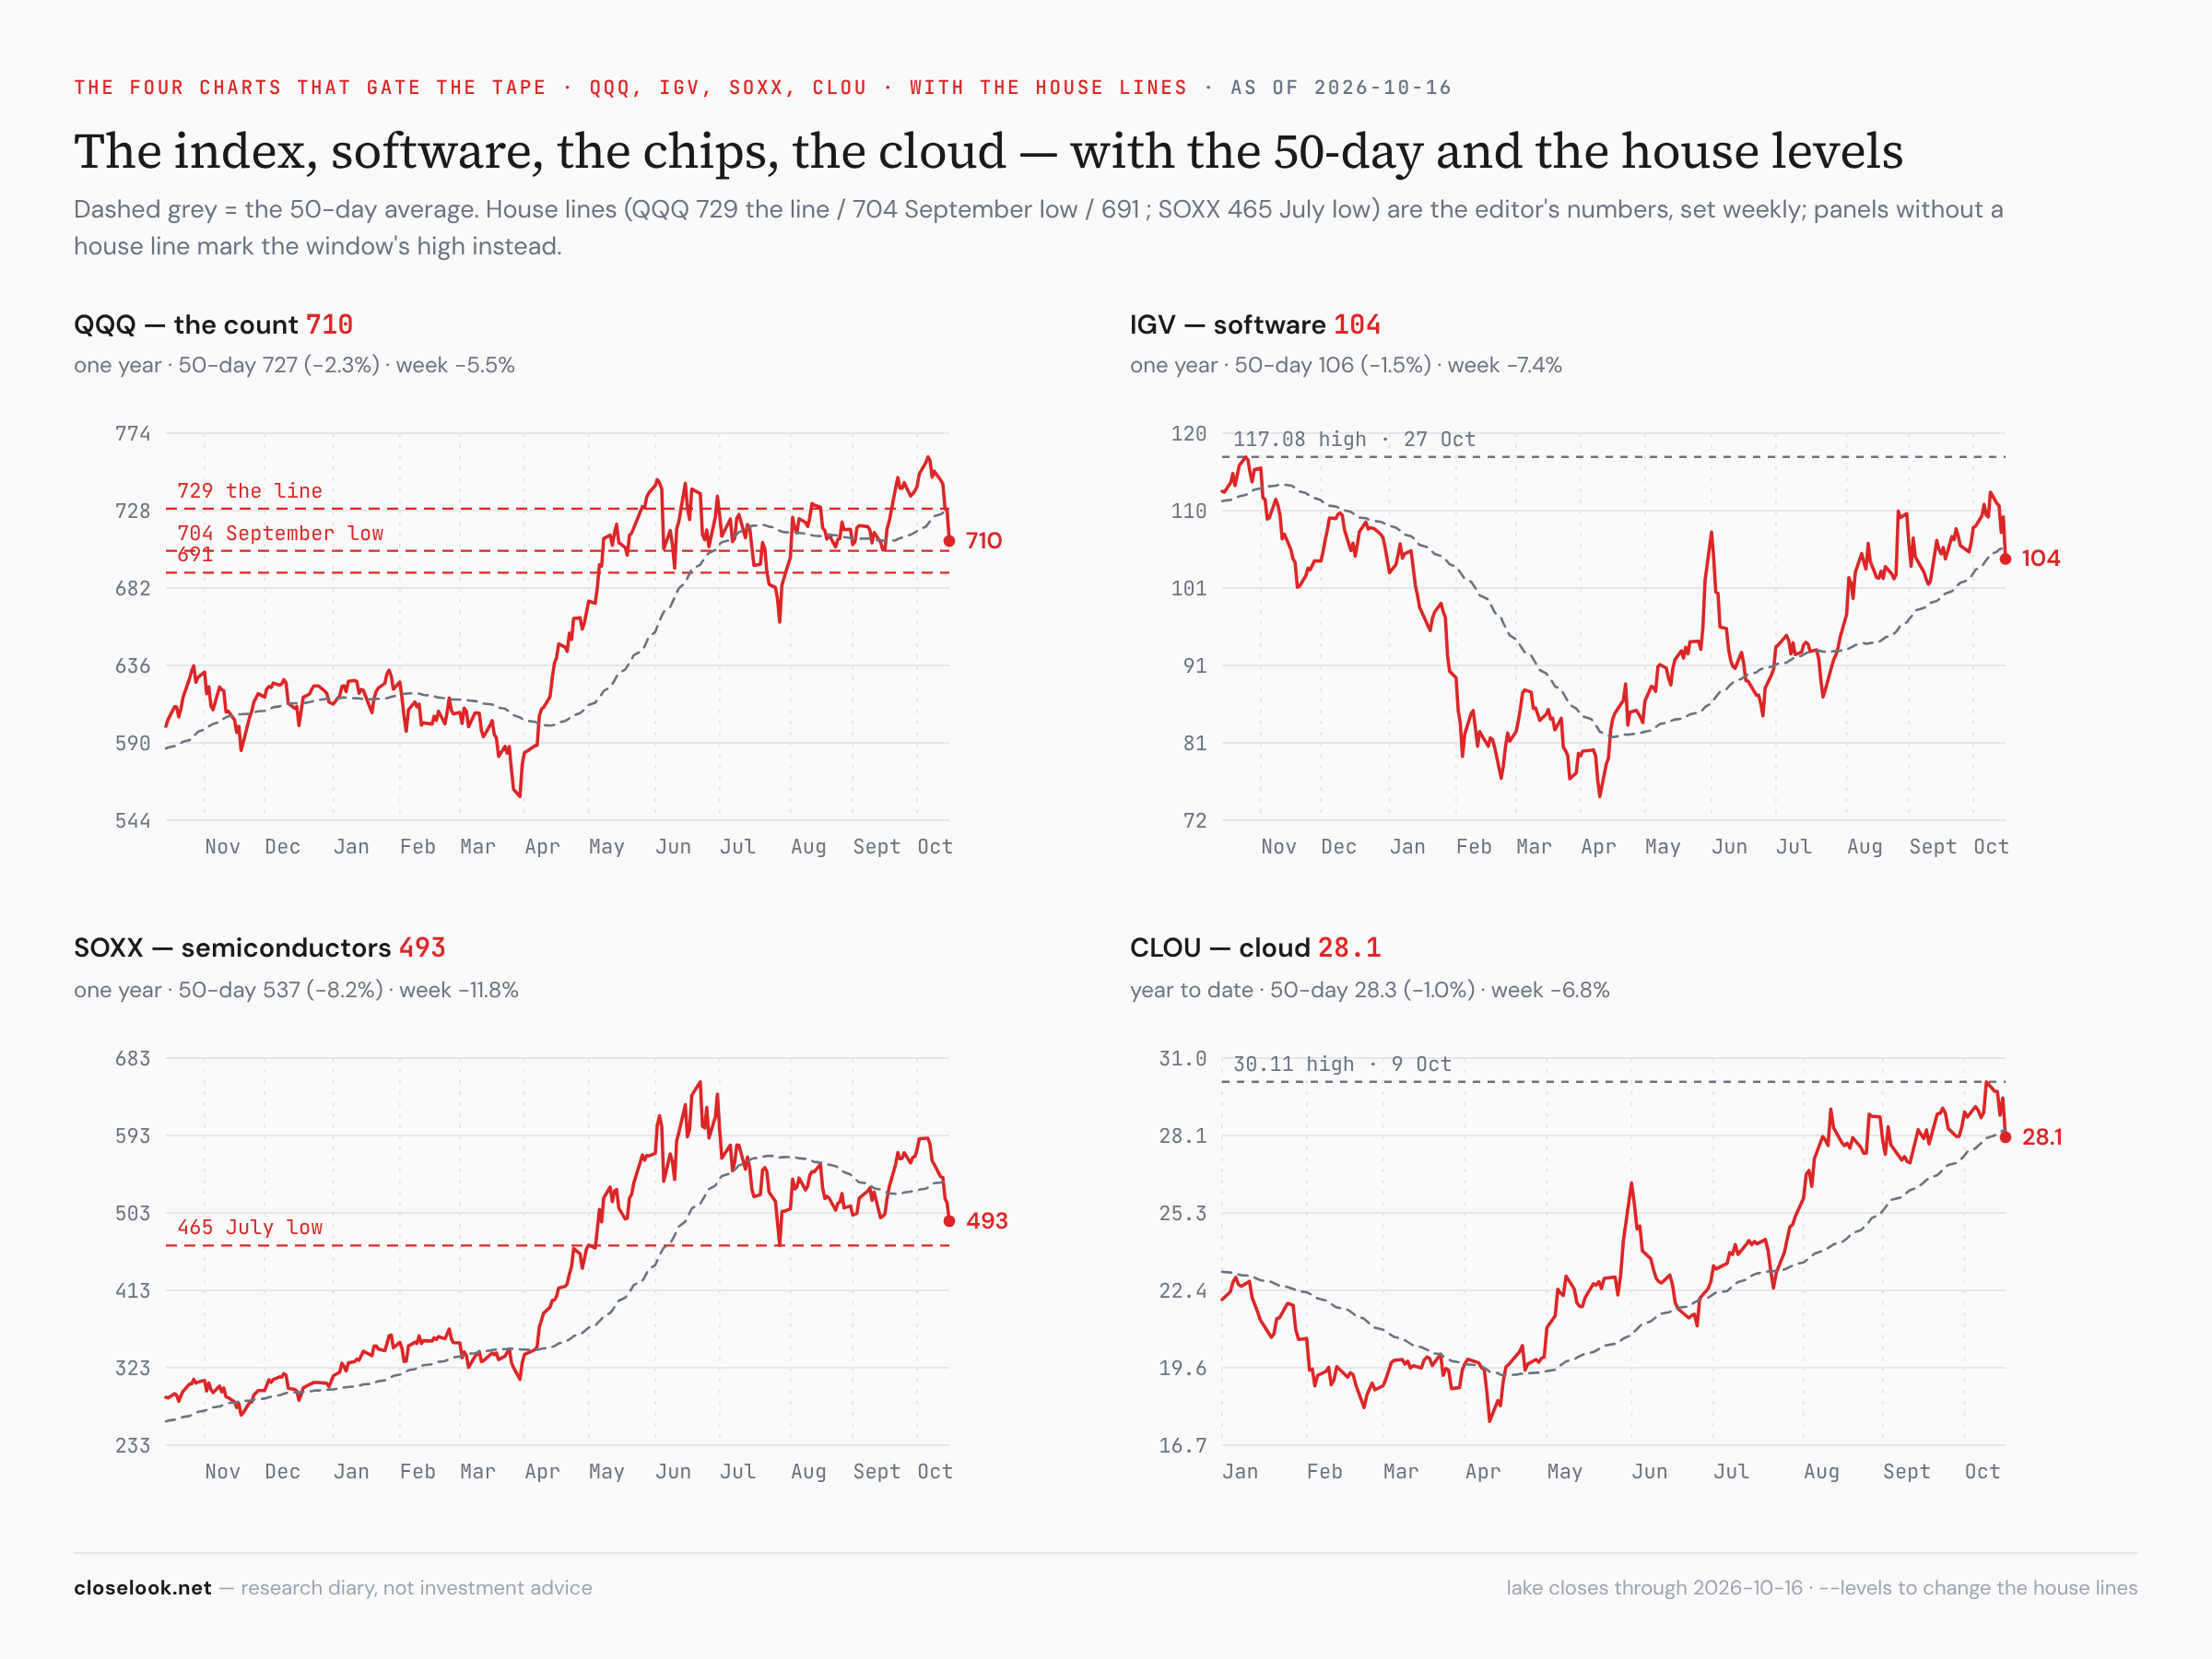
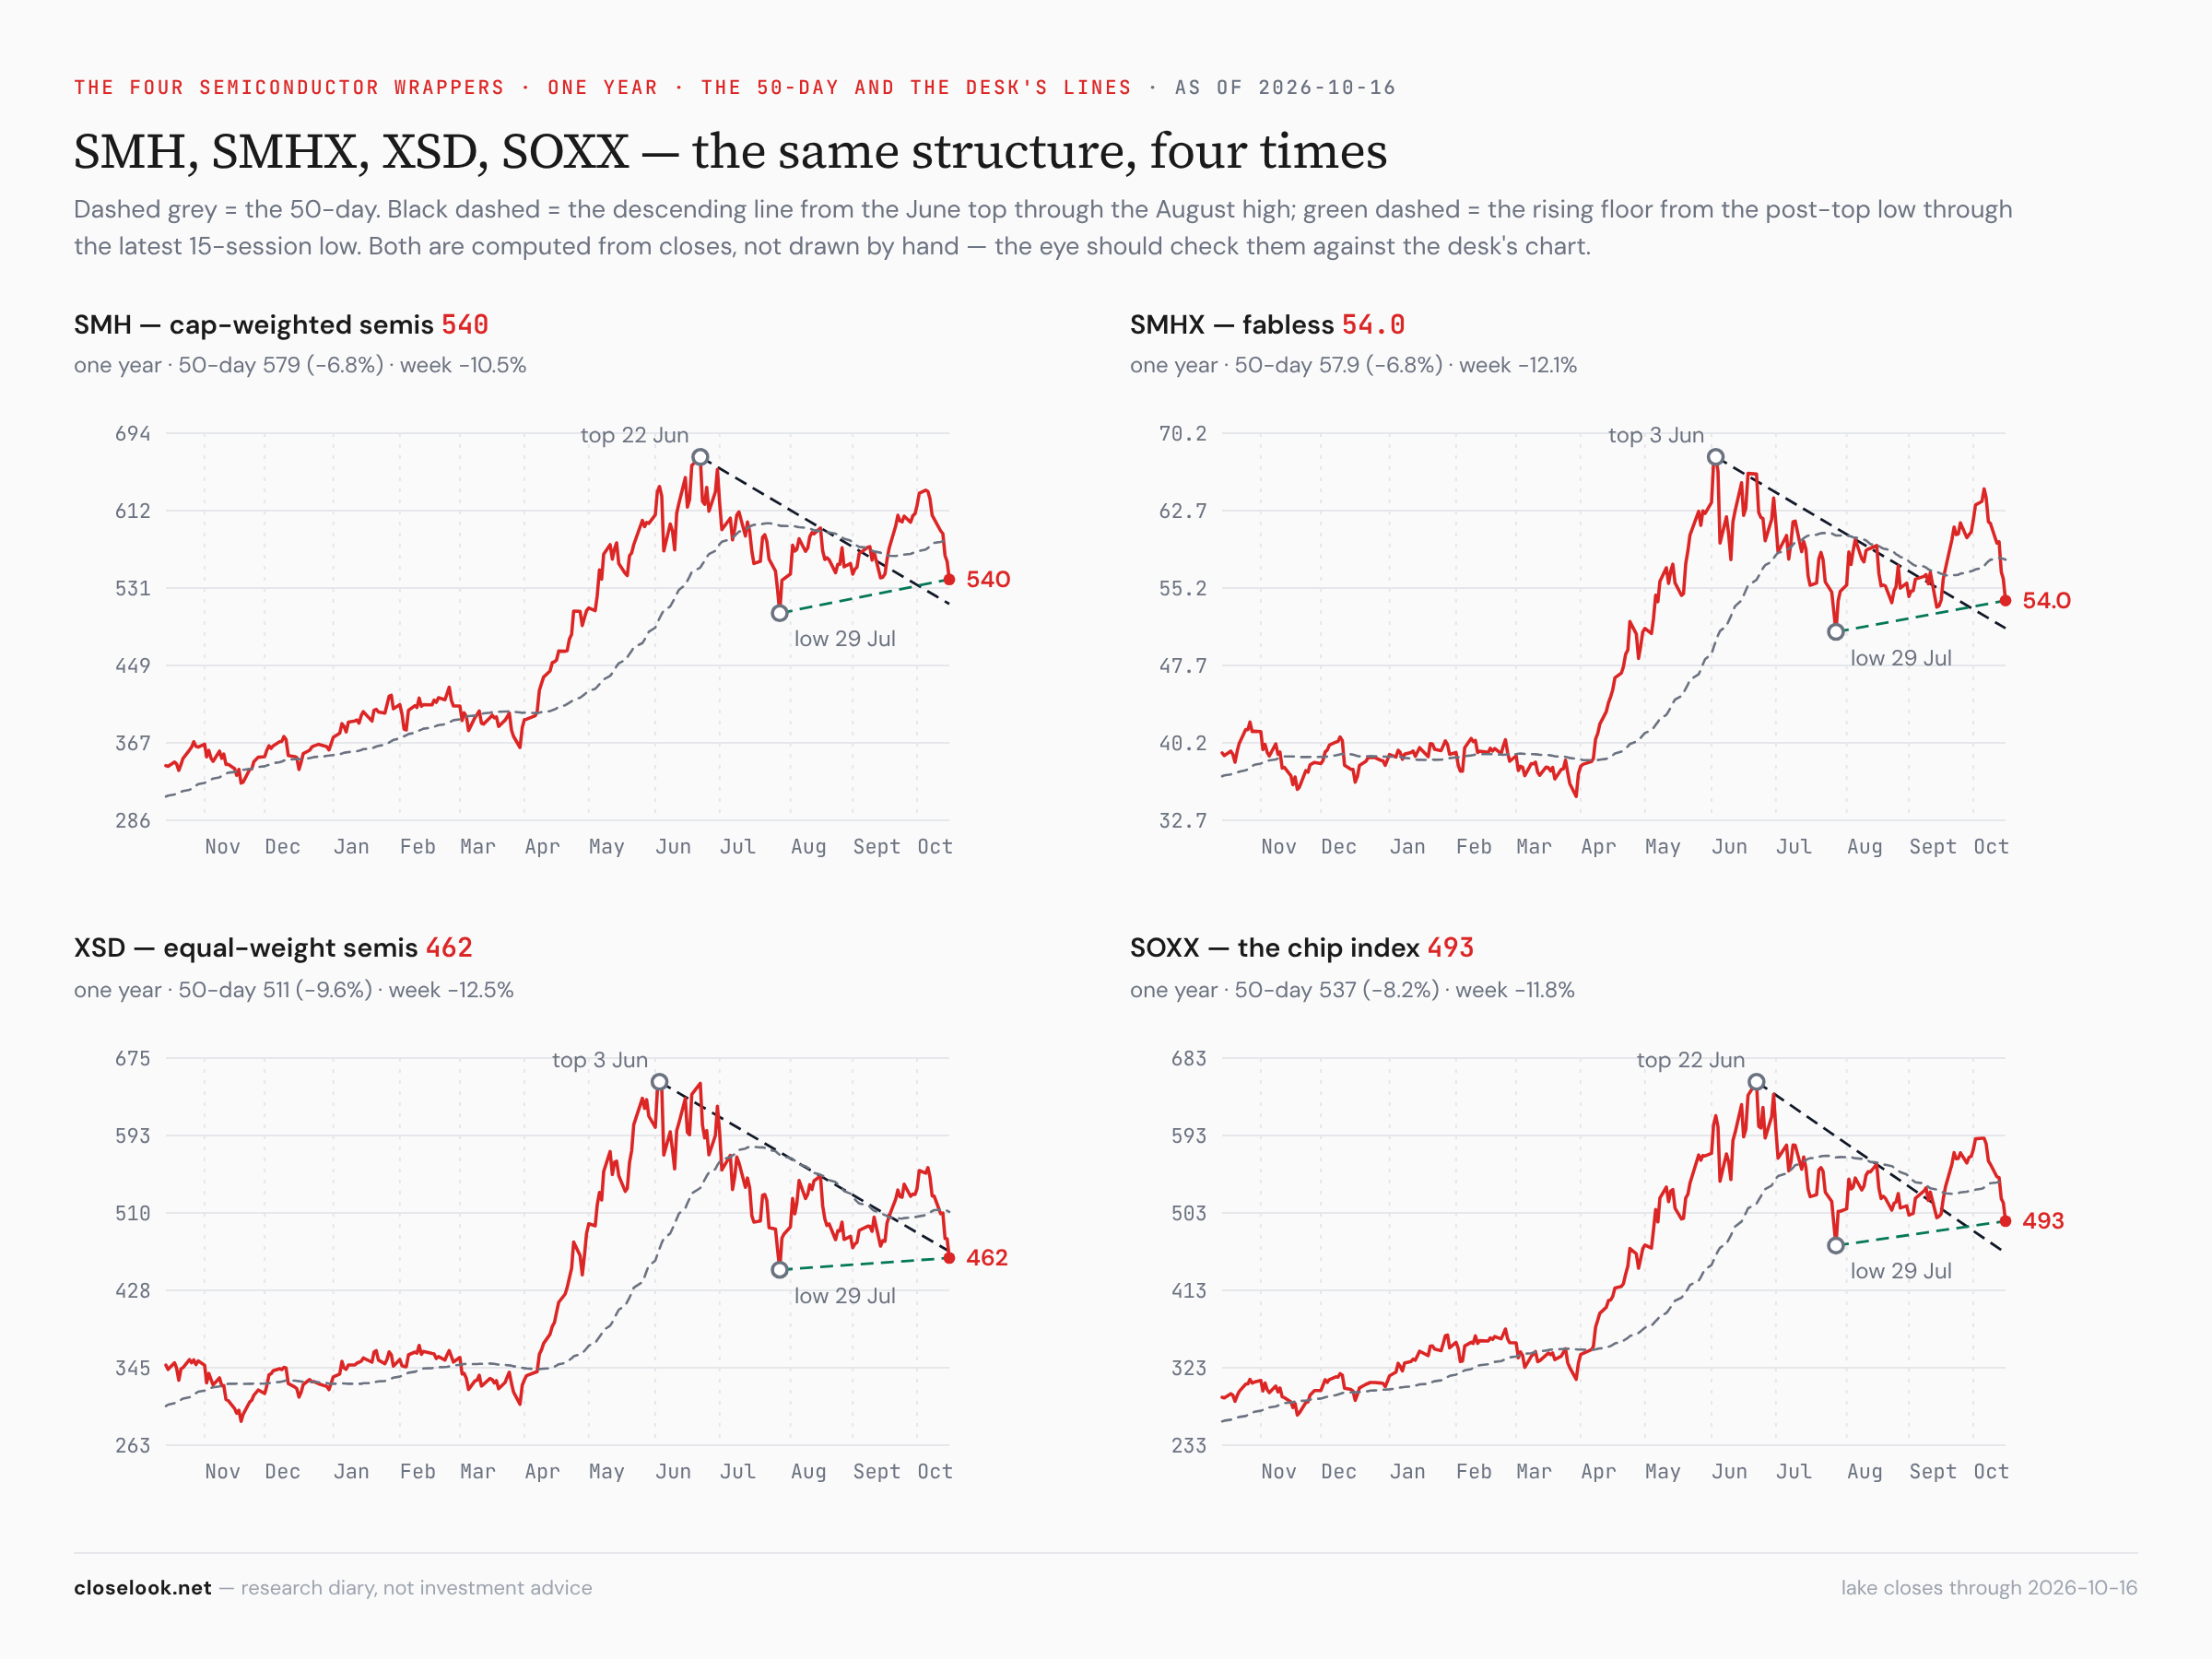
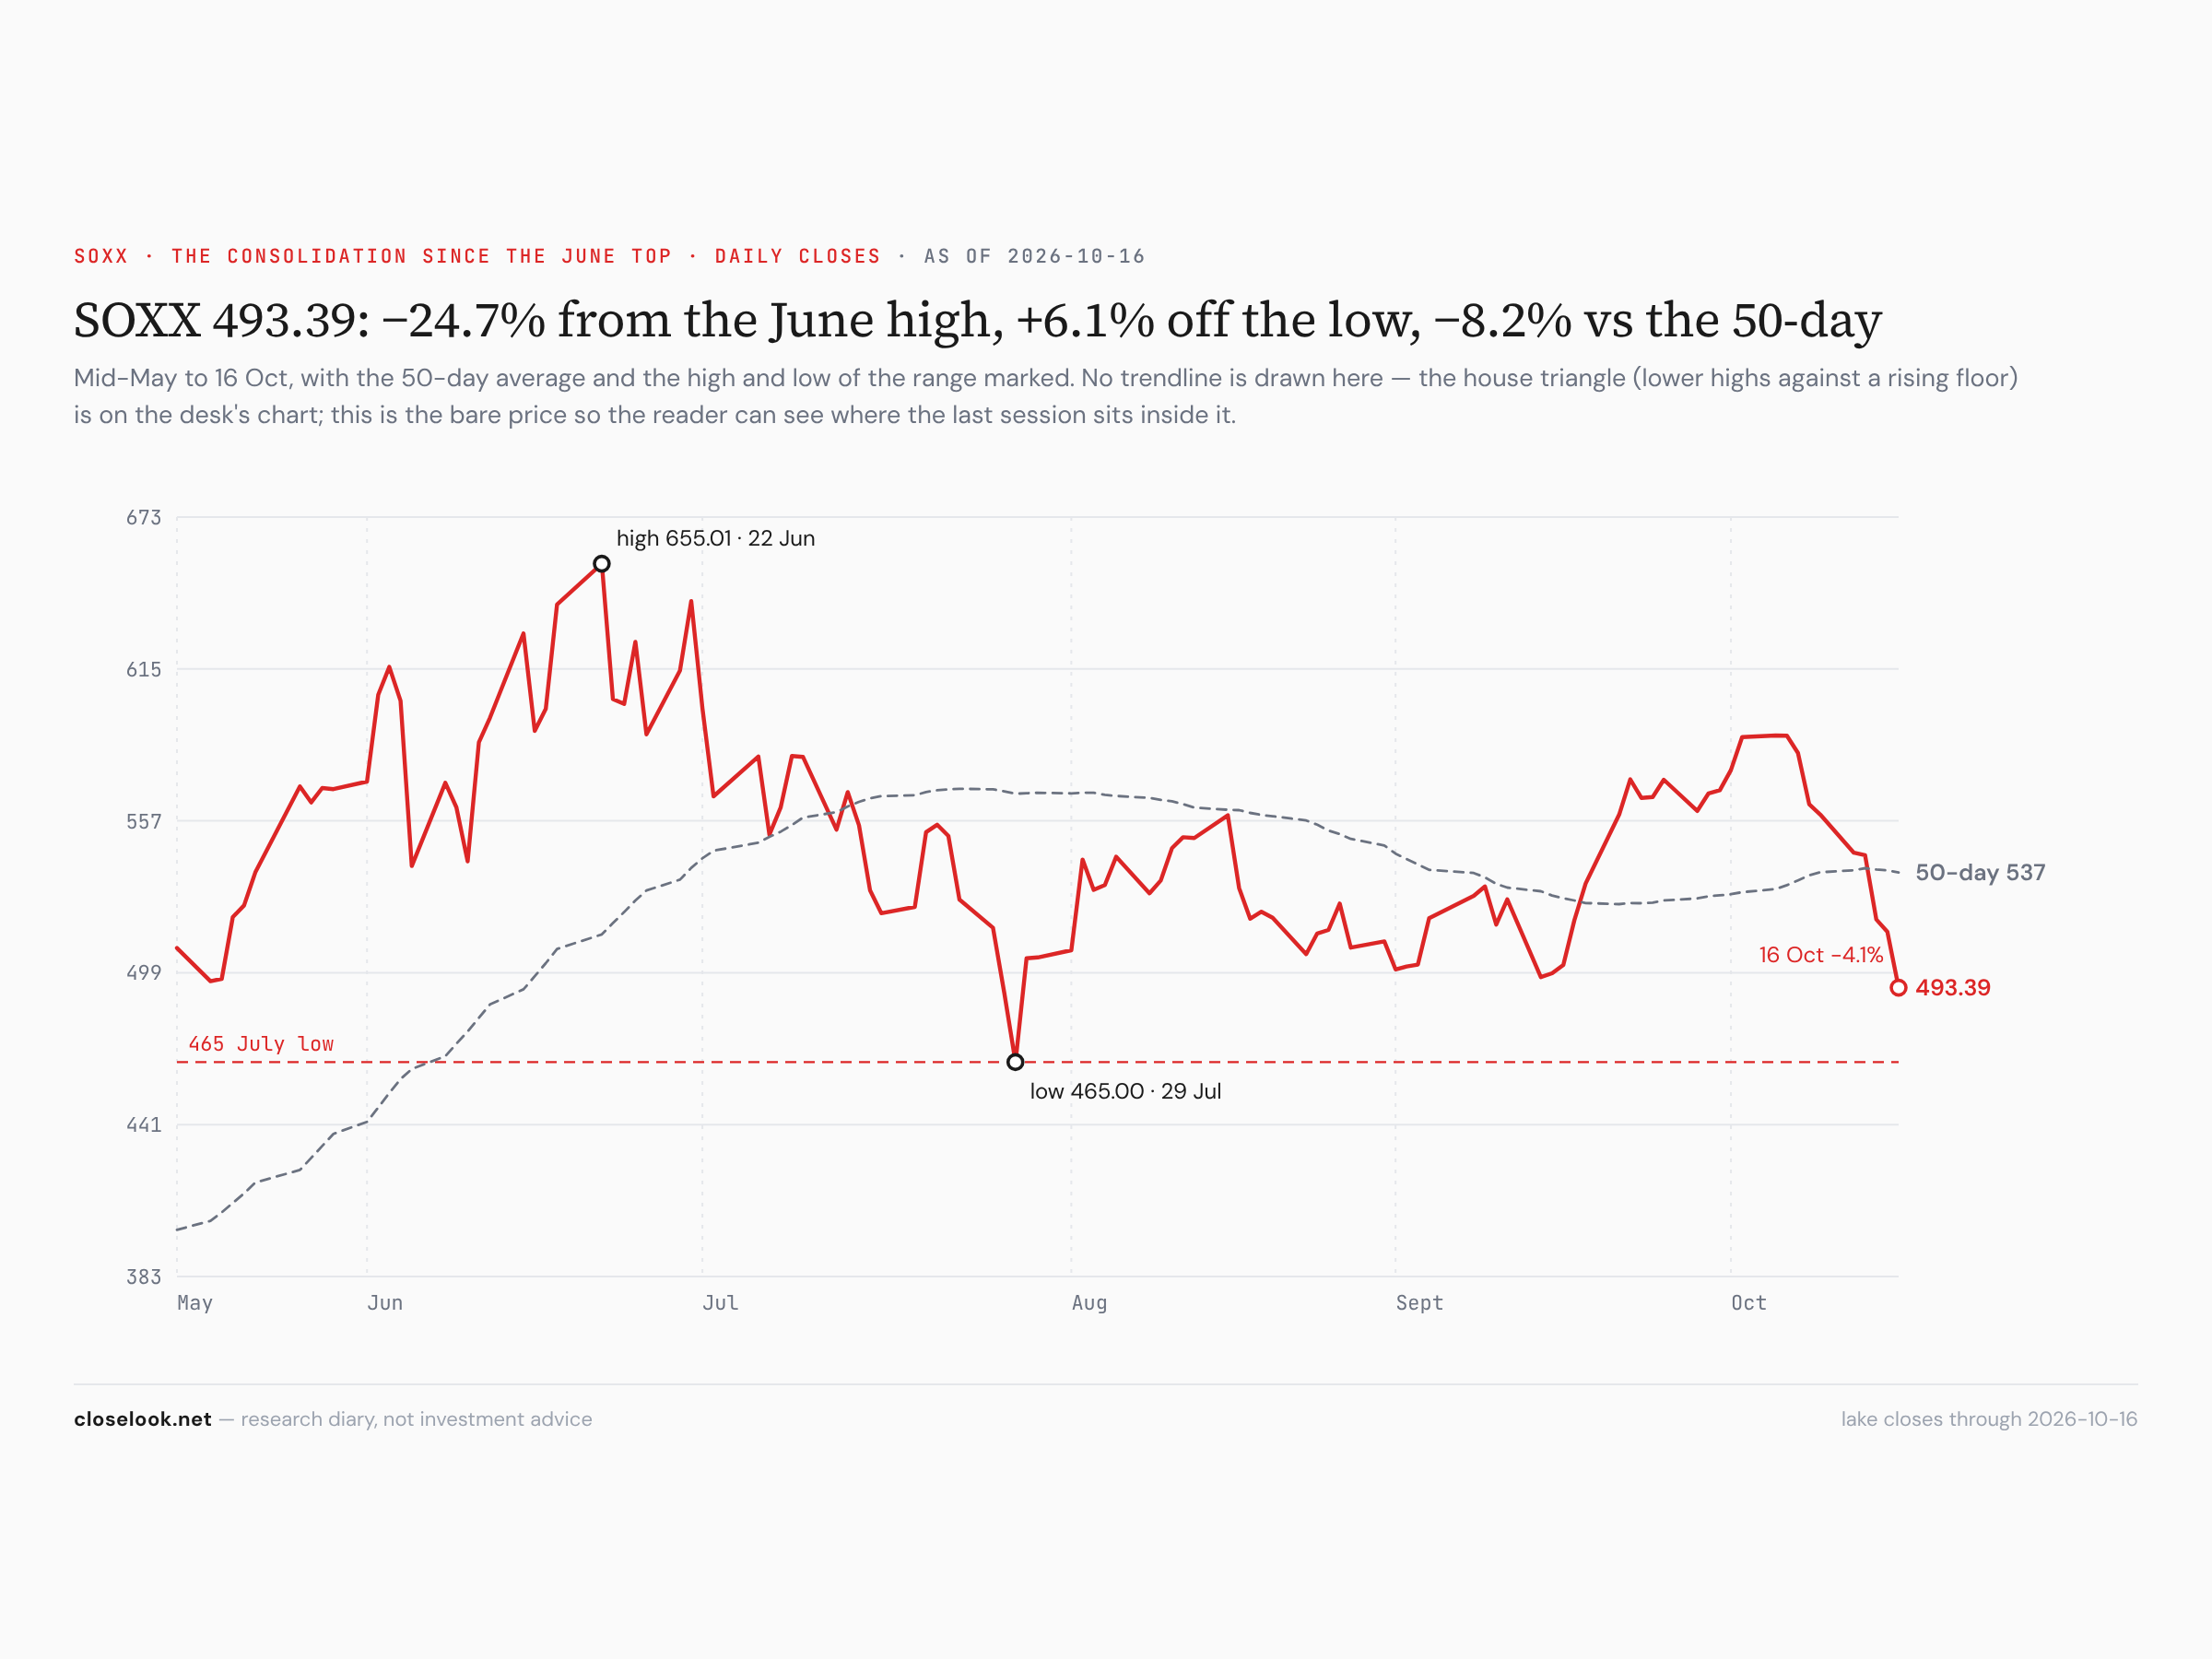
The chips — the second leg. SOXX 493.39: 24.7% under its 22 June high, 8.2% under its 50-day, 6.1% above the 465.00 July low. SMH 539.79, 19.3% under its June high; XSD 462.03, 28.7% under, back at its July level. The July low is the line the whole chip complex now trades against.
Software — from shelter to seller. IGV 104.34 — 7.4% under last Friday's 112.67, which was its best close of 2026; 1.5% under its 50-day. CLOU 28.07, 6.8% under its 30.11 high of last Friday. CIBR 98.82, 10.2% lower on the week. A week ago software was making highs while the chips fell. This week it fell with them.
3 · The Outlook
The three-index read — capex and opex both sold, applications flat. Capex (Rubin Build-Out) −13.45%, 26.8% under its June high, +76.4% on the year. Opex (Agentic Ecosystem) −14.16%, from a record a week ago — not one of its 34 names rose. Applications (Agentic Winners 40) −0.50%, after −2.0% on Friday. The builders and the companies that run AI fell together; the applications held most of the week and gave a little back at the end. HALO — growth with no AI thesis — fell 0.5%.
The regime gauges. The Money Temperature board read 47, down from 57 — cooler, with the Nasdaq gauge at 36 and long bonds at 62; by its own construction not a signal. The momentum/low-vol pair turned below its trend. Structural inflation reads "contained", its direction flat — the headline numbers ran hot, the structural measure did not move.
4 · What May Lie Ahead
The fourth quarter — still positive for the US, now led by different sectors. This letter's frame for the rest of 2026 stays: the strongest stretch of the calendar, expected to be positive to year-end. What changed this week is who leads it. Last year's fourth quarter is the precedent: tech peaked on 29 October 2025 and fell 10.5% by 20 November, software 13.9%, and health care was the best sector of the quarter at +11.2% — while the S&P still finished it up 2.4%. A positive quarter for the index can hold a month of selling in its winners.
The stance — buy dips, but not the first one under a broken line. Two weeks ago this letter set the stance as buying dips, not chasing. The tech channel break changes the timing, not the stance: a dip under the March line is a dip that needs a base first. The base, if it comes, shows as a close back above 729 on QQQ — or a low that holds at one of the lines below.
The levels, updated. QQQ 709.80 — 729 the broken line, now overhead; 704 the September-low area, 691, 674 and 660 below; the 50-day at 726.77. SPY 763.25 — 779.09 the record close above; 768.50 the 50-day, lost. The equal-weight S&P 214.09 — 215.84 the 50-day, 0.8% above. SOXX 493.39 — 465.00 the July low. IGV 104.34 — 100 the spring line. QQXT 98.95 — 95.56 the year's low; 100.45 above. XLP 87.62 — 90.01 the February high close. XLV 176.71 — 177.19 Thursday's one-year high close. TLT 80.05 — Thursday's gap the line to hold.
The week's calendar. Monday: ASML's window closes. Tuesday: TSMC's. Wednesday 21 October, after the close: Tesla, Meta, IBM and SAP — the first big-tech reports into the selling. Meta's and Tesla's dates are confirmed by the companies.
The print record
The banks were paid — two of them. UnitedHealth +6.3% — paid, from 377.76 to 401.43 after a beat on both lines, in the week health care led. Wells Fargo +3.9% — paid, 70 cents over its line as banks were bought in the rotation out of tech. JPMorgan +2.5%, Johnson & Johnson +2.8%, Goldman Sachs −1.2%, Citigroup −0.2% — all flat: JPMorgan missed and recovered, Goldman's wide beat drew nothing, J&J closed 51 cents under its paid line. PepsiCo −0.8% — flat (Tuesday). Delta −6.7% — sold (Wednesday).
Two windows open. ASML reported a record quarter on Wednesday; the window runs from Wednesday's 1,650.00 — paid at 1,699.50, sold under 1,600.50 — and Friday's 1,641.52 sits inside it. It is scored on Monday's close. TSMC beat on both lines on Thursday; the window runs from Thursday's 422.25 — paid at 434.92, sold under 409.58 — and Friday's 412.61 is three dollars above the sold line. It is scored on Tuesday.
5 · The AI Build-Out Portfolio
AI Buildout — 36 positions · unrealized +18.0% · benchmark Nasdaq-100 · snapshot Oct 23, 2026
| # | Symbol | Name | Weight | Unreal. |
|---|---|---|---|---|
| 1 | US Dollar | — | 15.8% | +0.0% |
| 2 | TOELY | — | 13.9% | +459.4% |
| 3 | NET | — | 4.1% | +66.3% |
| 4 | CIBR | — | 3.6% | +19.3% |
| 5 | NVDA | — | 3.6% | +15.7% |
| 6 | DDOG | — | 3.4% | +115.4% |
| 7 | NTRA | — | 3.4% | +95.8% |
| 8 | PLTR | — | 3.3% | +37.3% |
| 9 | ATEYY | — | 3.3% | +10.4% |
| 10 | RBRK | — | 3.3% | +136.0% |
| 11 | TSM | — | 3.2% | +14.9% |
| 12 | IOT | — | 3.0% | +64.4% |
| 13 | SIEGY | — | 3.0% | -8.5% |
| 14 | BB | — | 3.0% | -12.5% |
| 15 | SNOW | — | 2.7% | +78.5% |
+ 21 more positions · full per-position cost basis & P&L is C+ subscriber-only.
What we did this week: nothing. No buys and no sells; Saturday's Pulse has the ledger of the one book that traded.
The book, marked — down about thirteen percent. The equity lines closed Friday at about $525,800 — about −13.4%, or about −$81,100 on the week, by the engine mark with one correction: the portfolio tracker still quotes the Tokyo Electron ADR at a pre-split price. Priced from Tokyo — 10,630 yen, half a share per ADR, 157.94 yen to the dollar — the ADR is worth about 33.65 dollars and the line about $16,900, down about 14% on the week. Net liquidation by the same mark is about $666,500, a headline return of about +33% on the $500,000 deposited.
What charged it — everything. Not one of the thirty-five lines rose. DigitalOcean −26.8% (−$5,420, the book's worst), Advantest −19.9% (−$4,920), Cloudflare −17.9% (−$4,850), Nebius −25.2% (−$4,170), Coherent −25.5% (−$3,990), Datadog −15.7% (−$3,460), SK Hynix −19.3% (−$3,250), Snowflake −16.8% (−$3,100), Tokyo Electron about −14% (about −$2,840), SanDisk −17.9% (−$2,830). The smallest losses were the least AI-heavy lines: Siemens −1.8%, Natera −1.8%, Alphabet −3.2%, Samsara −4.8%.
What we plan to do — nothing on Monday. The plan says add on weakness and act on the close. The broken channel says wait for the close that shows the weakness has a floor. ASML's and TSMC's windows, and Wednesday's reports, are the first closes worth reading.
The four tradable books, open for inspection. Alongside the reference portfolios on this site, the four Closelooknet-companion wikifolios — the tactical book, the AI-cycle thesis book, the ETF core, and the non-tech growth compounder — publish their own ledgers on the wikifolio platform, every transaction visible trade by trade, via Trade the Look. A research diary made investable for its author; not a recommendation.
6 · What May Go Wrong
One: profit-taking becomes de-risking. This week the money moved inside the market. If the equal-weight S&P follows the index down — a weekly close under its 50-day, 215.84, now 0.8% above — the rotation has turned into selling.
Two: the big-tech reports confirm the doubt. Meta, Tesla, IBM and SAP report on Wednesday into a broken channel. Good numbers sold, as Goldman's were this week, would say the market is reducing exposure whatever the quarter shows.
Three: the September low gives way. A QQQ close under 704 takes out the last floor before 691 and the July area at 660–674 — and the July low on the chips, 465.00 on SOXX, would go with it.
Four: hot inflation wins after all. The bond market ignored this week's price data. If the ten-year goes back above 5.31%, the defensive bid loses its rate support and the staples and utilities that rose on it give some back.
Five: the rotation goes too far too fast. Staples are at their best close since March after one week of +5%. Defensive rallies that start on a single week of panic in the leaders can reverse as quickly when the leaders bounce.
7 · Knowledge Corner
What a trend channel is, and what a break of it means. A channel is the simplest way to draw a trend: take two lows of a rising market and connect them with a straight line. As long as each new dip stops on or above that line, the trend is intact — buyers step in earlier each time, at higher prices. The Nasdaq 100 fund has done that since 30 March: its dips in June, July and September all stopped on or near one rising line. A close below the line means the buyers did not step in at the usual place this time. It does not mean the trend is over. Often a market falls through the line, finds a floor at an old low, and moves sideways for weeks before the next leg — and the old line, once broken, tends to act as a ceiling on the way back up. What a break changes is the reading of dips: inside the channel, each dip is likely a chance; under it, a dip needs a floor before it is one. That is why this letter now names the floors — 704, 691, 674, 660 on QQQ — instead of the line.
8 · Final Words
The selling started in the chips and spread. By Friday it had reached software, the hyperscalers and Nvidia — everything that had won the year. The chip fund fell 11.8%, software 7.4%, the Nasdaq 100 fund 5.5%, and it closed under the rising line that had held since the 30 March low.
And seven of eleven sectors rose. Staples gained 5% to their best close since March, health care made a one-year high on Thursday, energy rose almost 5%. The equal-weight S&P rose. The Nasdaq without its tech stocks rose. The ten-year yield fell to 5.10% in a week of hot inflation numbers.
That is broad profit-taking in the winners, not a market in flight. The money stayed; it changed seats.
Price is the only truth. This week it said: the tech trend broke, and the defensive growers took the lead. 729 overhead and 704 underneath on the Nasdaq fund, 465 on the chips, the equal-weight S&P against its 50-day — and Meta, Tesla, IBM and SAP on Wednesday — will say whether this is a pause in the year's trend or a new one.