Daily Pulse · · 10:00 CET · 5 min read · market · MU
In this edition
Pattern alerts
- MU hbm-memory-double-bottom-july-and-october-lows-plus-7-percent-off-the-second BULLISH
- COHR high-speed-interconnects-double-bottom-second-low-2-9-percent-above-july BULLISH
- CDNS eda-and-chip-ip-flat-on-the-month-while-rubin-lost-13-percent BULLISH
- MSFT capex-guidance-tonight-is-rubin-revenue NEUTRAL
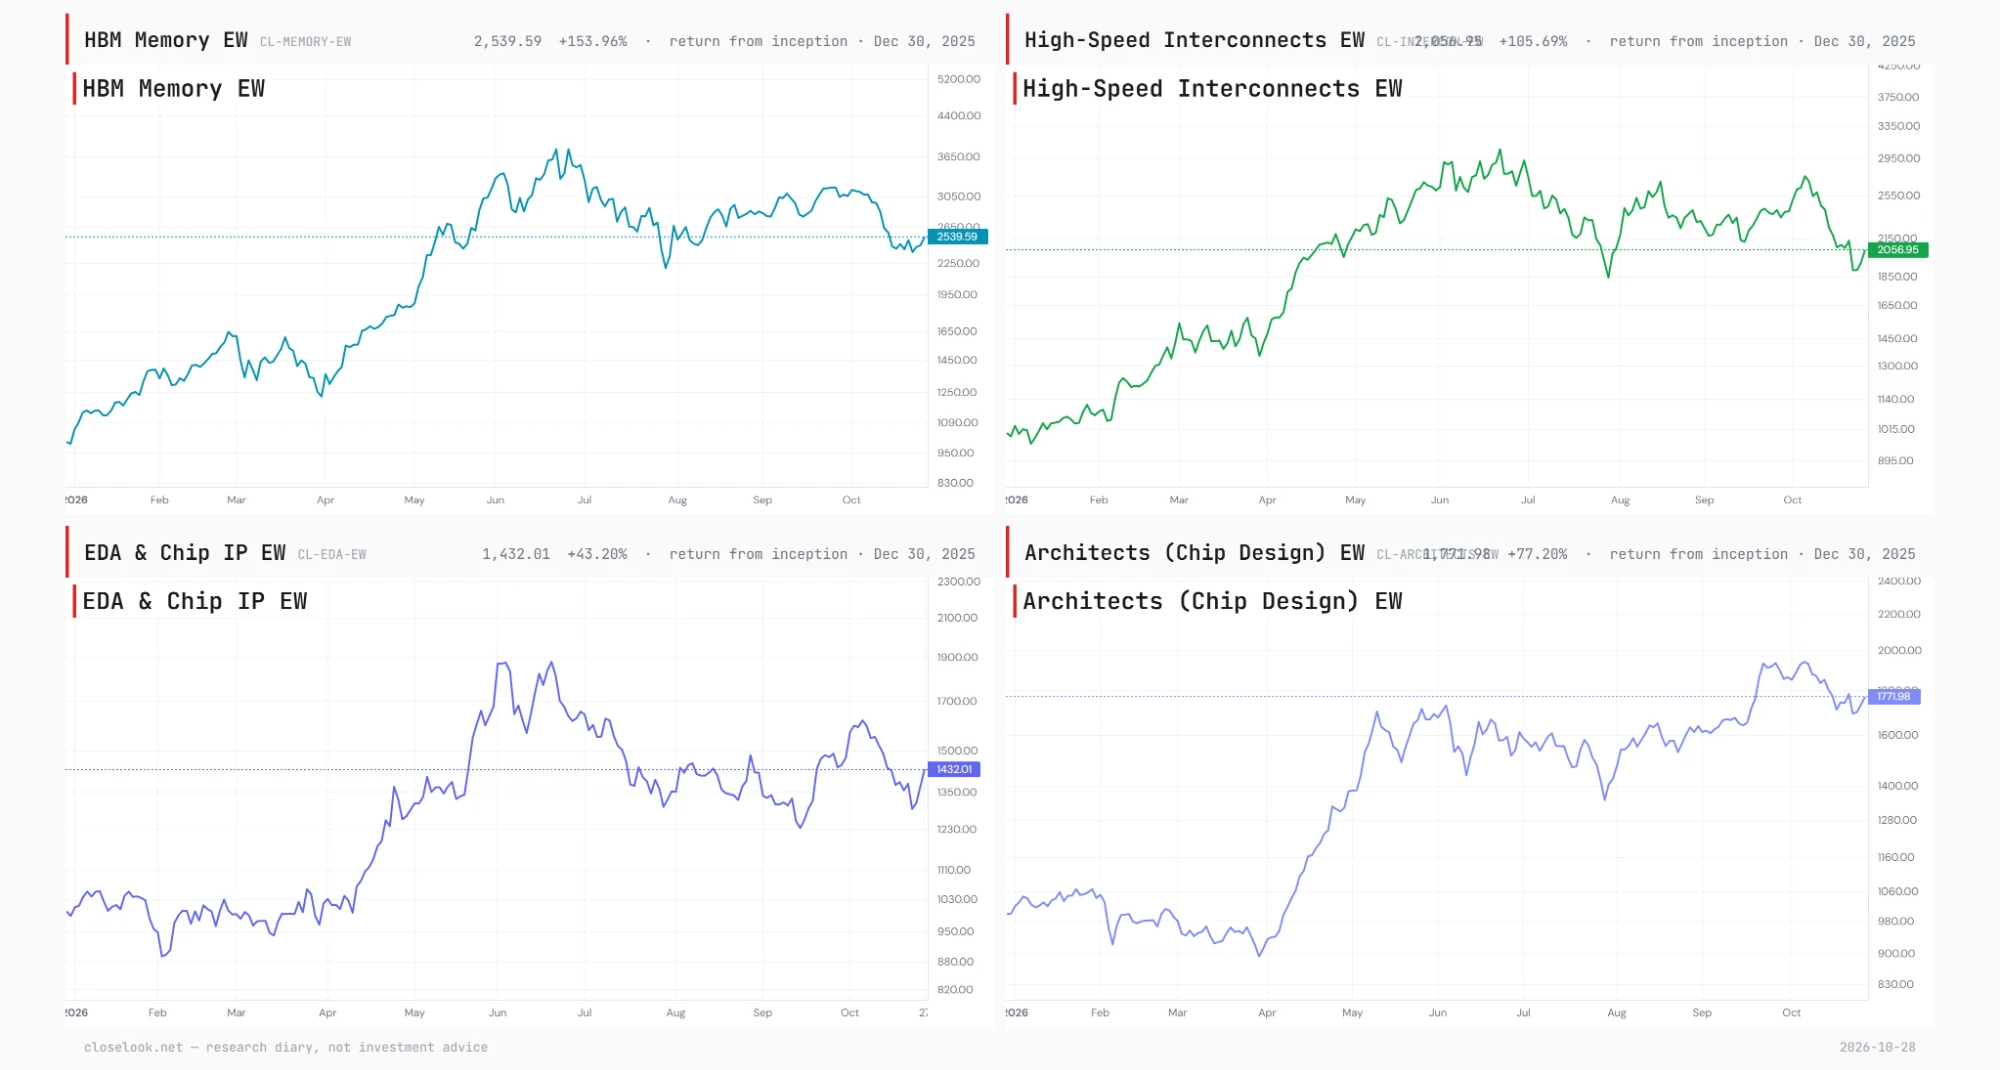
The AI build-out has had a brutal month. Inside our Rubin Build-Out index, an equal-weight basket of the 130 companies that design, make, package and power AI hardware, two of the sectors hit hardest have just drawn the most classic recovery shape on the chart: a double bottom. Two other sectors went through the same selloff with their relative strength intact.
Memory and interconnects — the same low, twice
A double bottom is two lows at roughly the same price, with a rally between them. It means buyers stepped in at the same level twice. When the second low holds at or above the first, the selling has met a floor it couldn't break.
HBM Memory, the high-bandwidth memory makers SK hynix, Samsung Electronics and Micron, made its first low at 2,203.96 on 29 July. It then rallied to 3,177.52 by 25 September. The October selloff took it down to 2,370.52 on 22 October, 7.6% above the July low, and it has climbed 7.1% since, to 2,539.59. That's still 32.9% under June's peak, which is why the month looks so bad (−16.56%). But the floor held.
High-Speed Interconnects, the optical and networking hardware that links AI chips together, drew the same shape more tightly. The first low was 1,845.04 on 29 July and the rally peaked at 2,750.56 on 6 October. The second low came on 22 and 23 October: two closes at 1,898.87 and 1,898.81, just 2.9% above July. Since then the sector has added 8.3%, including Tuesday's +5.1%, with Coherent, Lumentum and Fabrinet rallying alongside this week's supplier reports.
Overnight, memory got the strongest possible confirmation from the fundamentals. SK hynix reported a record quarter with an operating margin near 80% and a plan to return about 100 trillion won to shareholders. It rose 10.9% in Seoul, Samsung 9.0%. Those moves feed into tonight's index calculation.
C — free account
The free C account unlocks the full Daily Pulse — every section of this read.
One tap with Google or one email — no password, no card. You are signed in until you sign out, on this browser, from then on.
Join the Look — freeAlready joined on this browser? The full edition shows automatically — if it doesn't, sign in again here. Looking for the archive, portfolios and realtime? That is C+.
One more block on our desk — tomorrow's levels and what we're watching into the next session. Join the Look — it’s free.