Source page — copy text into Substack/LinkedIn, upload the visuals. noindex · not public
Closelook@Global Stock Markets · Weekly Edition
Global Markets — Brazil Falls 24%, Chips Crack on Friday, Europe and Health Care Hold
The week the money was raised, region by region. Brazil's fund fell 23.8 percent after the runoff, almost all of it on Monday. The chips rallied into Wednesday and gave it all back on Friday, when the chip index fell 8 percent and Korea and Taiwan followed. Europe rose 1.7 percent, Switzerland closed at a record, India rose for the week, and health care climbed in three of four regions. The US ten-year closed the week at 4.93 percent — the first weekly close under 5 percent since the 5.31 percent peak of 5 October. Gold closed under its July low, at its lowest close of the past year, and silver at its lowest of 2026. The world ex-US index held its summer-low support for a second week.
Closelooknet is a reader-supported publication — to receive new posts and support the work, become a free or paid subscriber.
1 · This Week's Action
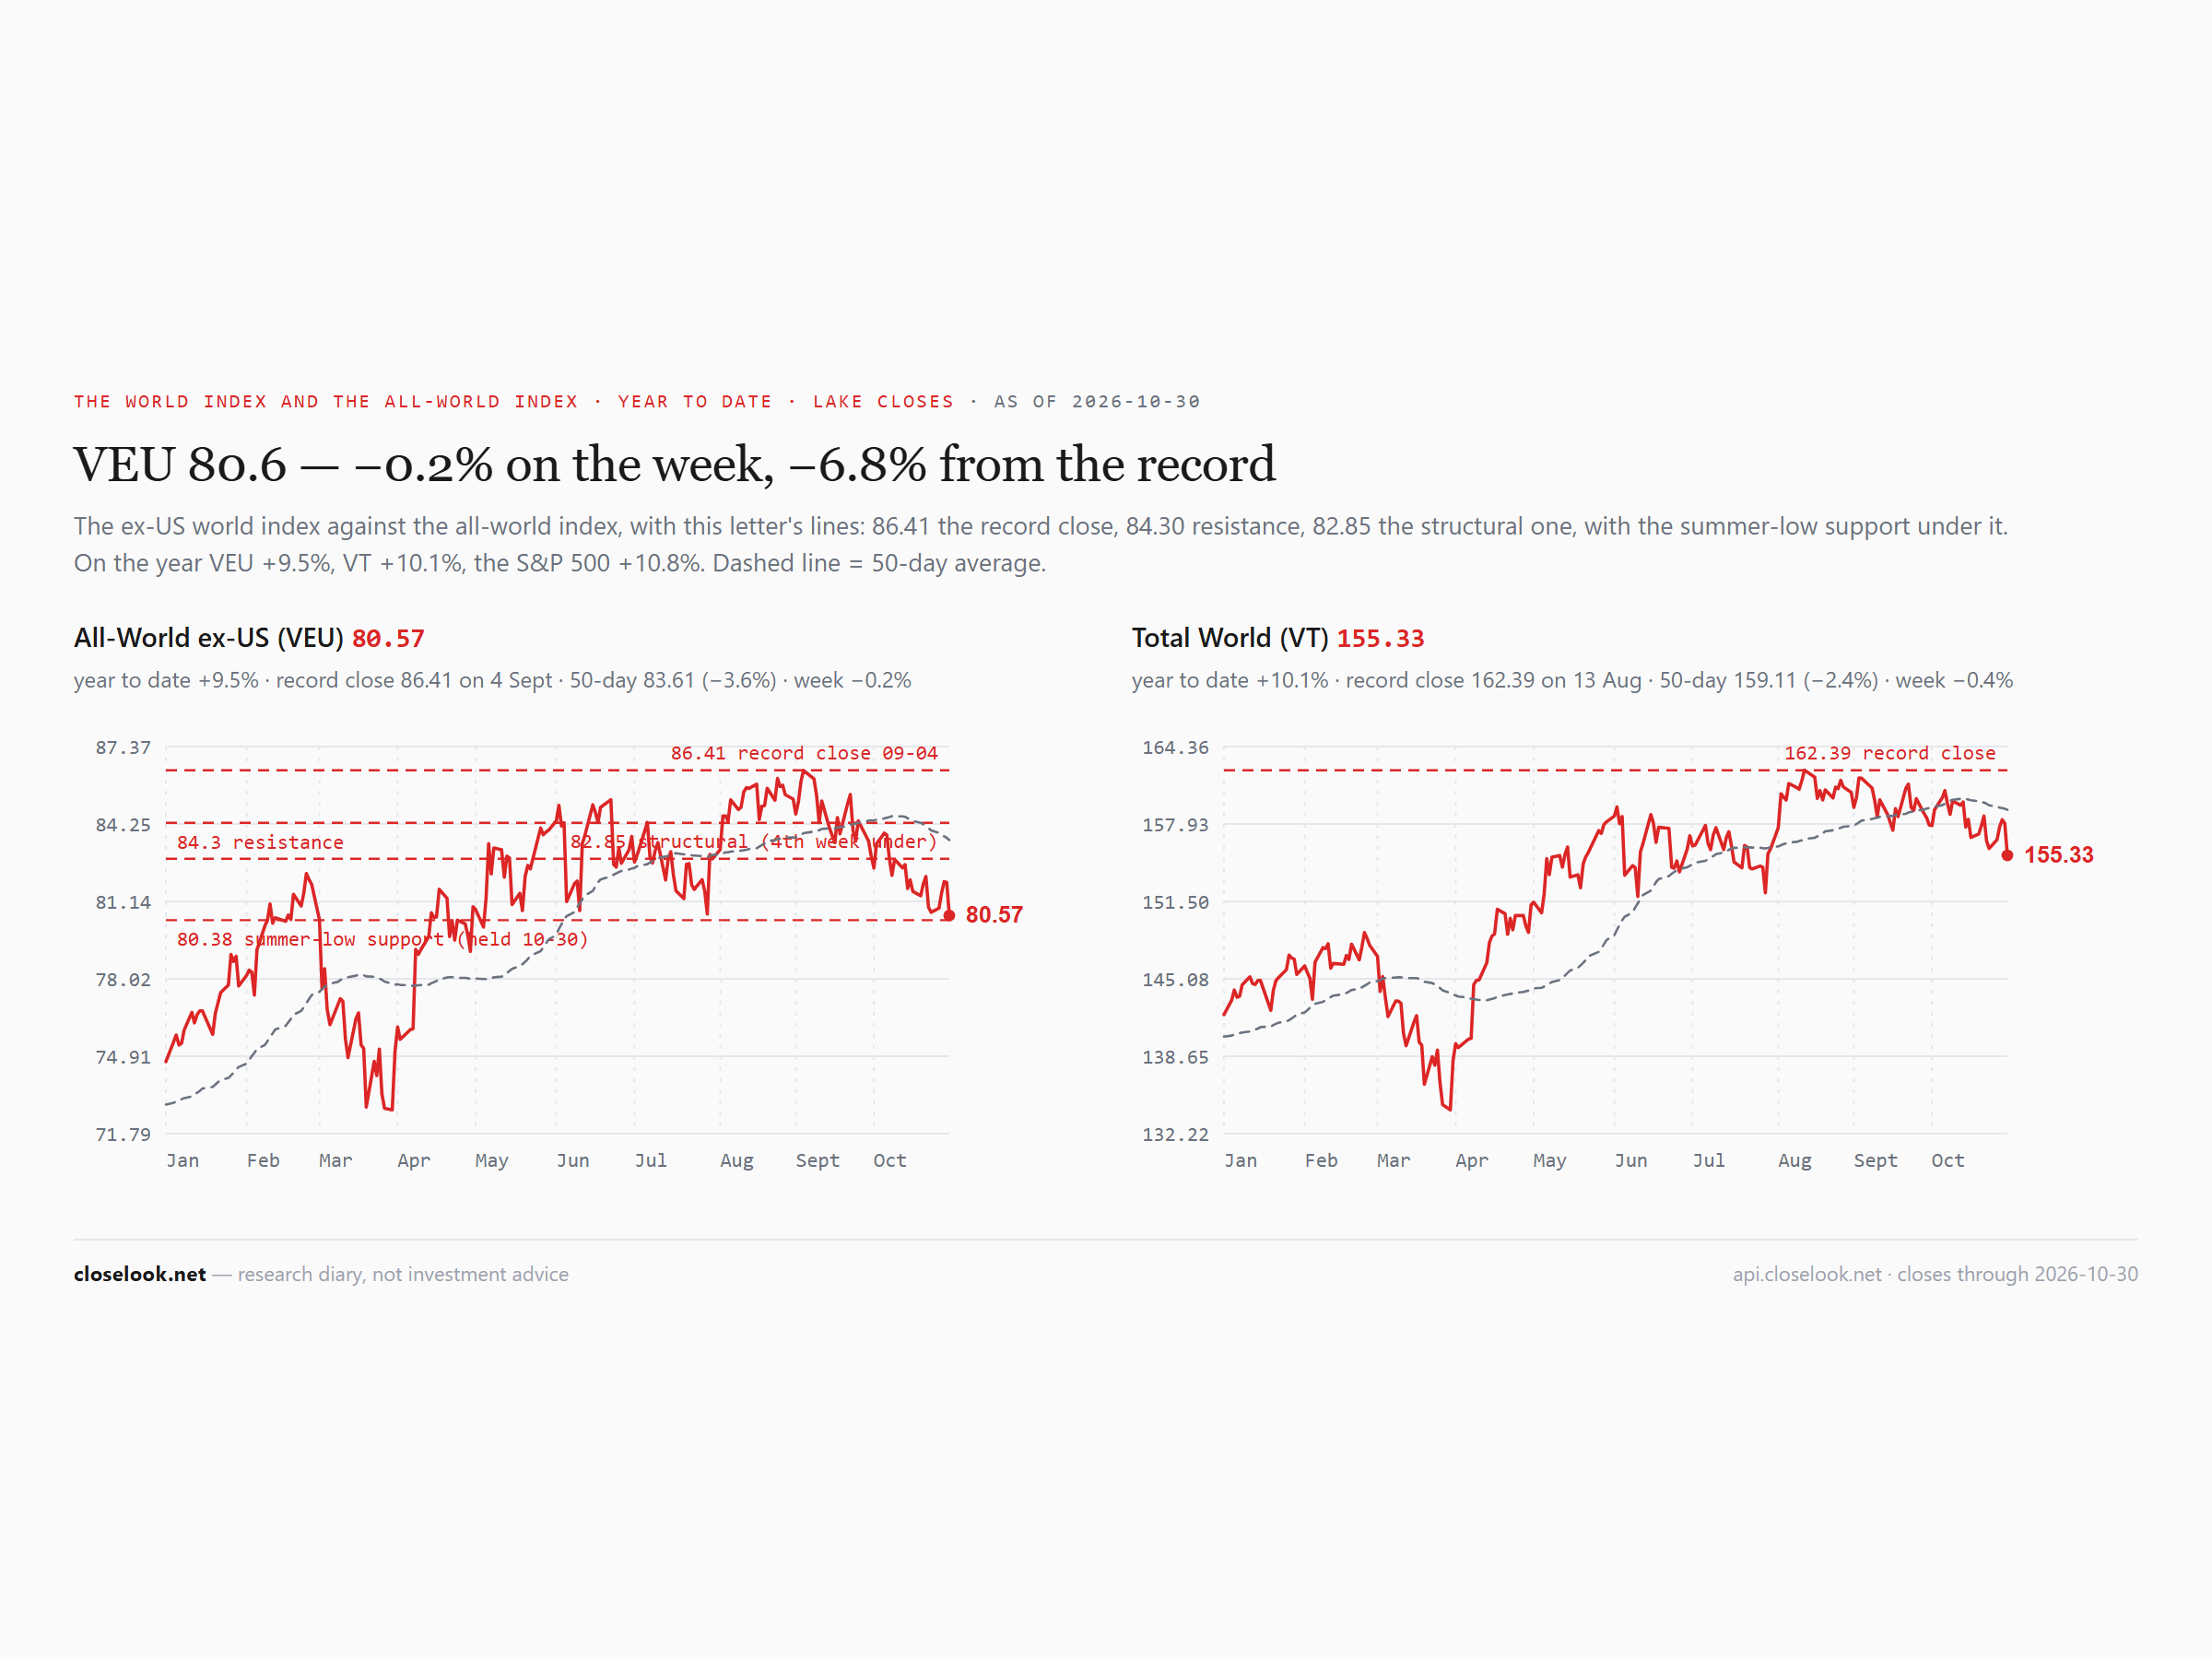
The global view. The ex-US world index closed the week at 80.57, down 0.16% — a fourth weekly close under 82.85, and a second week on the summer-low support near 80.3. The path: Monday 80.86, Tuesday 81.47, Wednesday 81.93, Thursday 81.90, Friday 80.57, with an intraday low of 80.06. The index sits 6.8% under its September 4 record of 86.41 and 10.7% above its spring low of 72.75.
The all-world index fell 0.37% to 155.33, a second week under the range it held from August, 156.82 to 162.39. The S&P 500 fund fell 0.56% to 755.72, 3.0% under its October 6 record; the Nasdaq 100 fund fell 1.97% to 690.49, 9.1% under its own. Most of it came on Friday, when the all-world index fell 1.7% in one session.
America still leads the year — by less. The S&P 500 fund is +10.8% for 2026, the all-world index +10.1%, the world ex-US +9.5%. A week ago America led the world ex-US by 1.7 points; this week by 1.3. The house cointegration monitor still lists the VEU/SPY pair as breaking, the spread 1.8 standard deviations below its mean, from 2.2.
The week, in one line: investors raised cash — but region by region, not everywhere at once. On Monday the money left Brazil. On Friday it left the chips, and with them Korea and Taiwan. In between, Europe rose, India rose, health care rose in three of four regions, and the US ten-year yield closed the week under 5 percent for the first time since the peak. Nineteen of thirty-five regional funds rose. The best-to-worst spread was 27.4 points — from 11.2 a week ago, and almost all of it was one country.
Brazil: the runoff, and the unwind. Lula won Brazil's runoff on Sunday, 52 to 48. A Tokyo-listed Bovespa fund fell nearly 15% in Asian trade before Brazil opened. On Monday the Brazil fund EWZ fell 19.8%; the Latin America 40 fund fell 11.2%. By Friday EWZ was down 23.8% on the week at 32.46, and ILF down 14.8% at 32.13. In local terms the Bovespa fell 18.1% on the week and the real lost about 8.5% against the dollar. The fund had risen into the runoff — its record close of the year, 43.54, came on 9 October, after the first round. One week took back all of it and more.
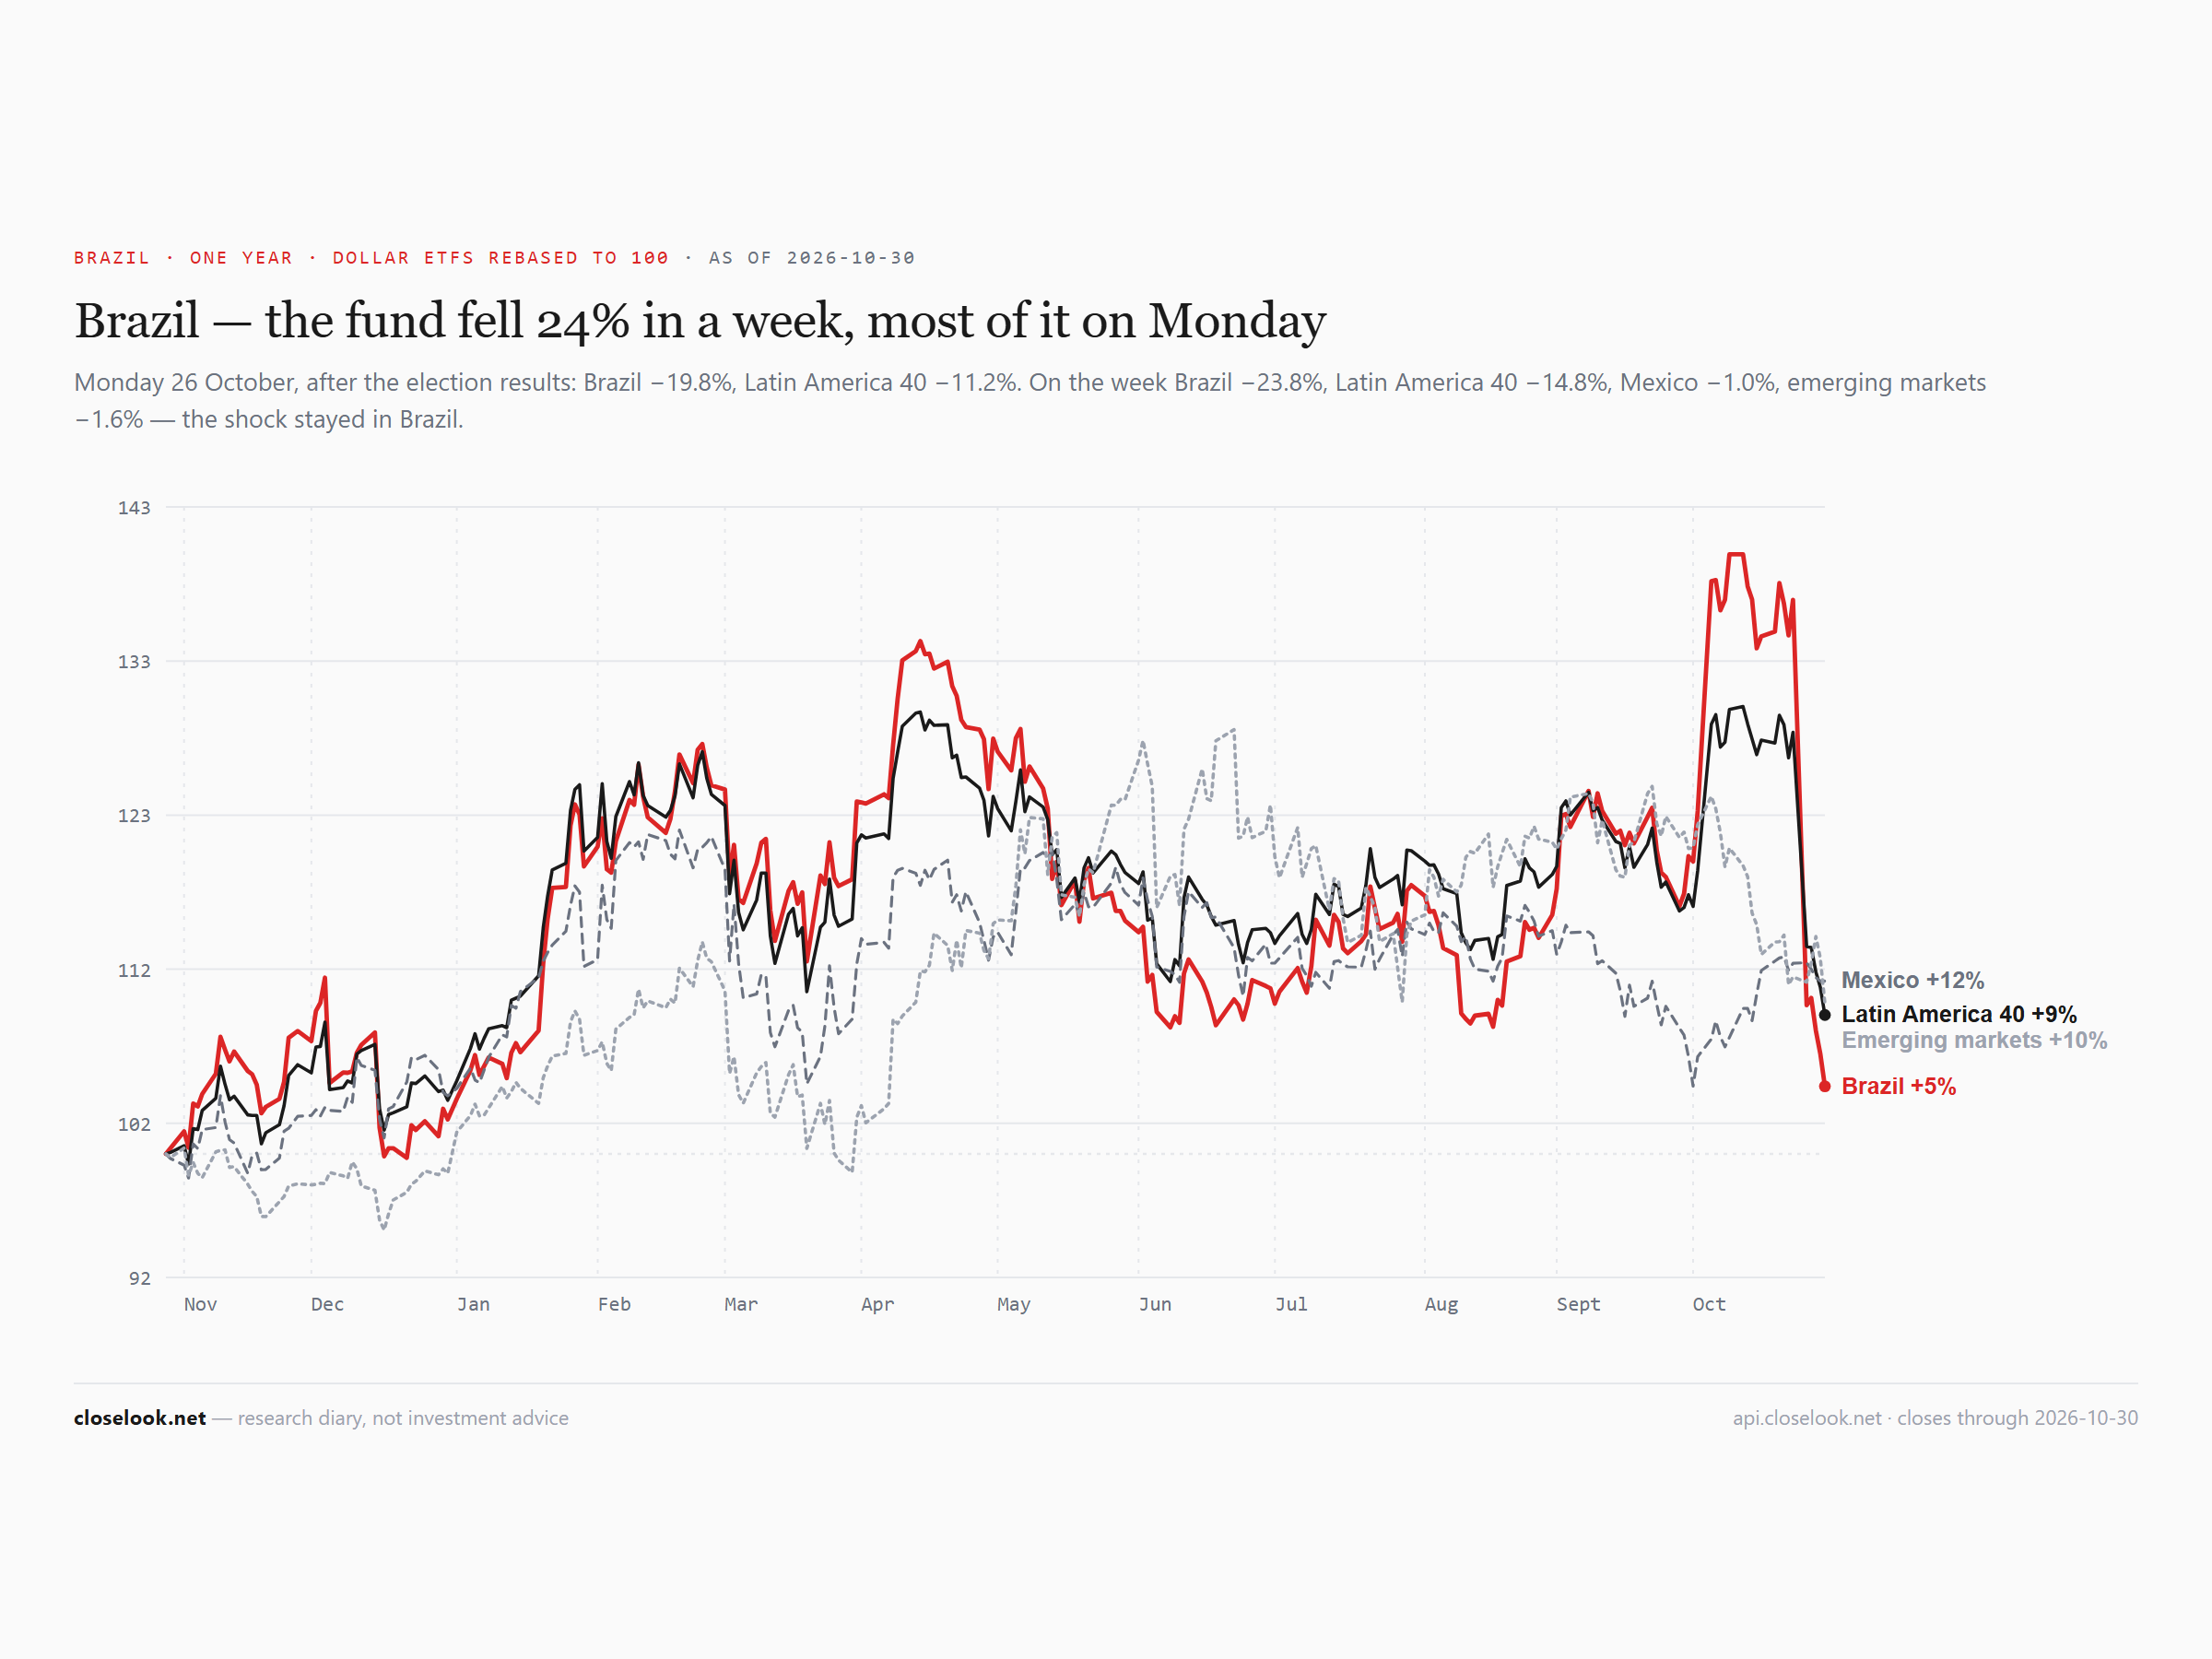
The shock stayed in Brazil. Mexico fell 1.0%, the emerging-markets fund 1.6%, Argentina 9.1%. Indonesia fell 6.0% for its own reasons. A shock that stays inside one country is a repricing of that country. One that spreads is a problem for the asset class. This one, so far, did not spread.
The chips: up three days, down one. The chip index rose from 10,779 to 11,684 on Wednesday, on SK hynix's record quarter and a Kospi that rose 6.6% through 6,000 on the same day. Thursday turned on the US mega-cap reports: Alphabet fell about 13% and ServiceNow about 27% in the day after their numbers. On Friday, after Intel's 30% fall on its outlook, the chip index fell 7.2% in one session to 10,689 — a week that ended 0.8% lower after being 8.4% higher. The chip majors fund SMH ended at 522.49, 21.9% under its June record.
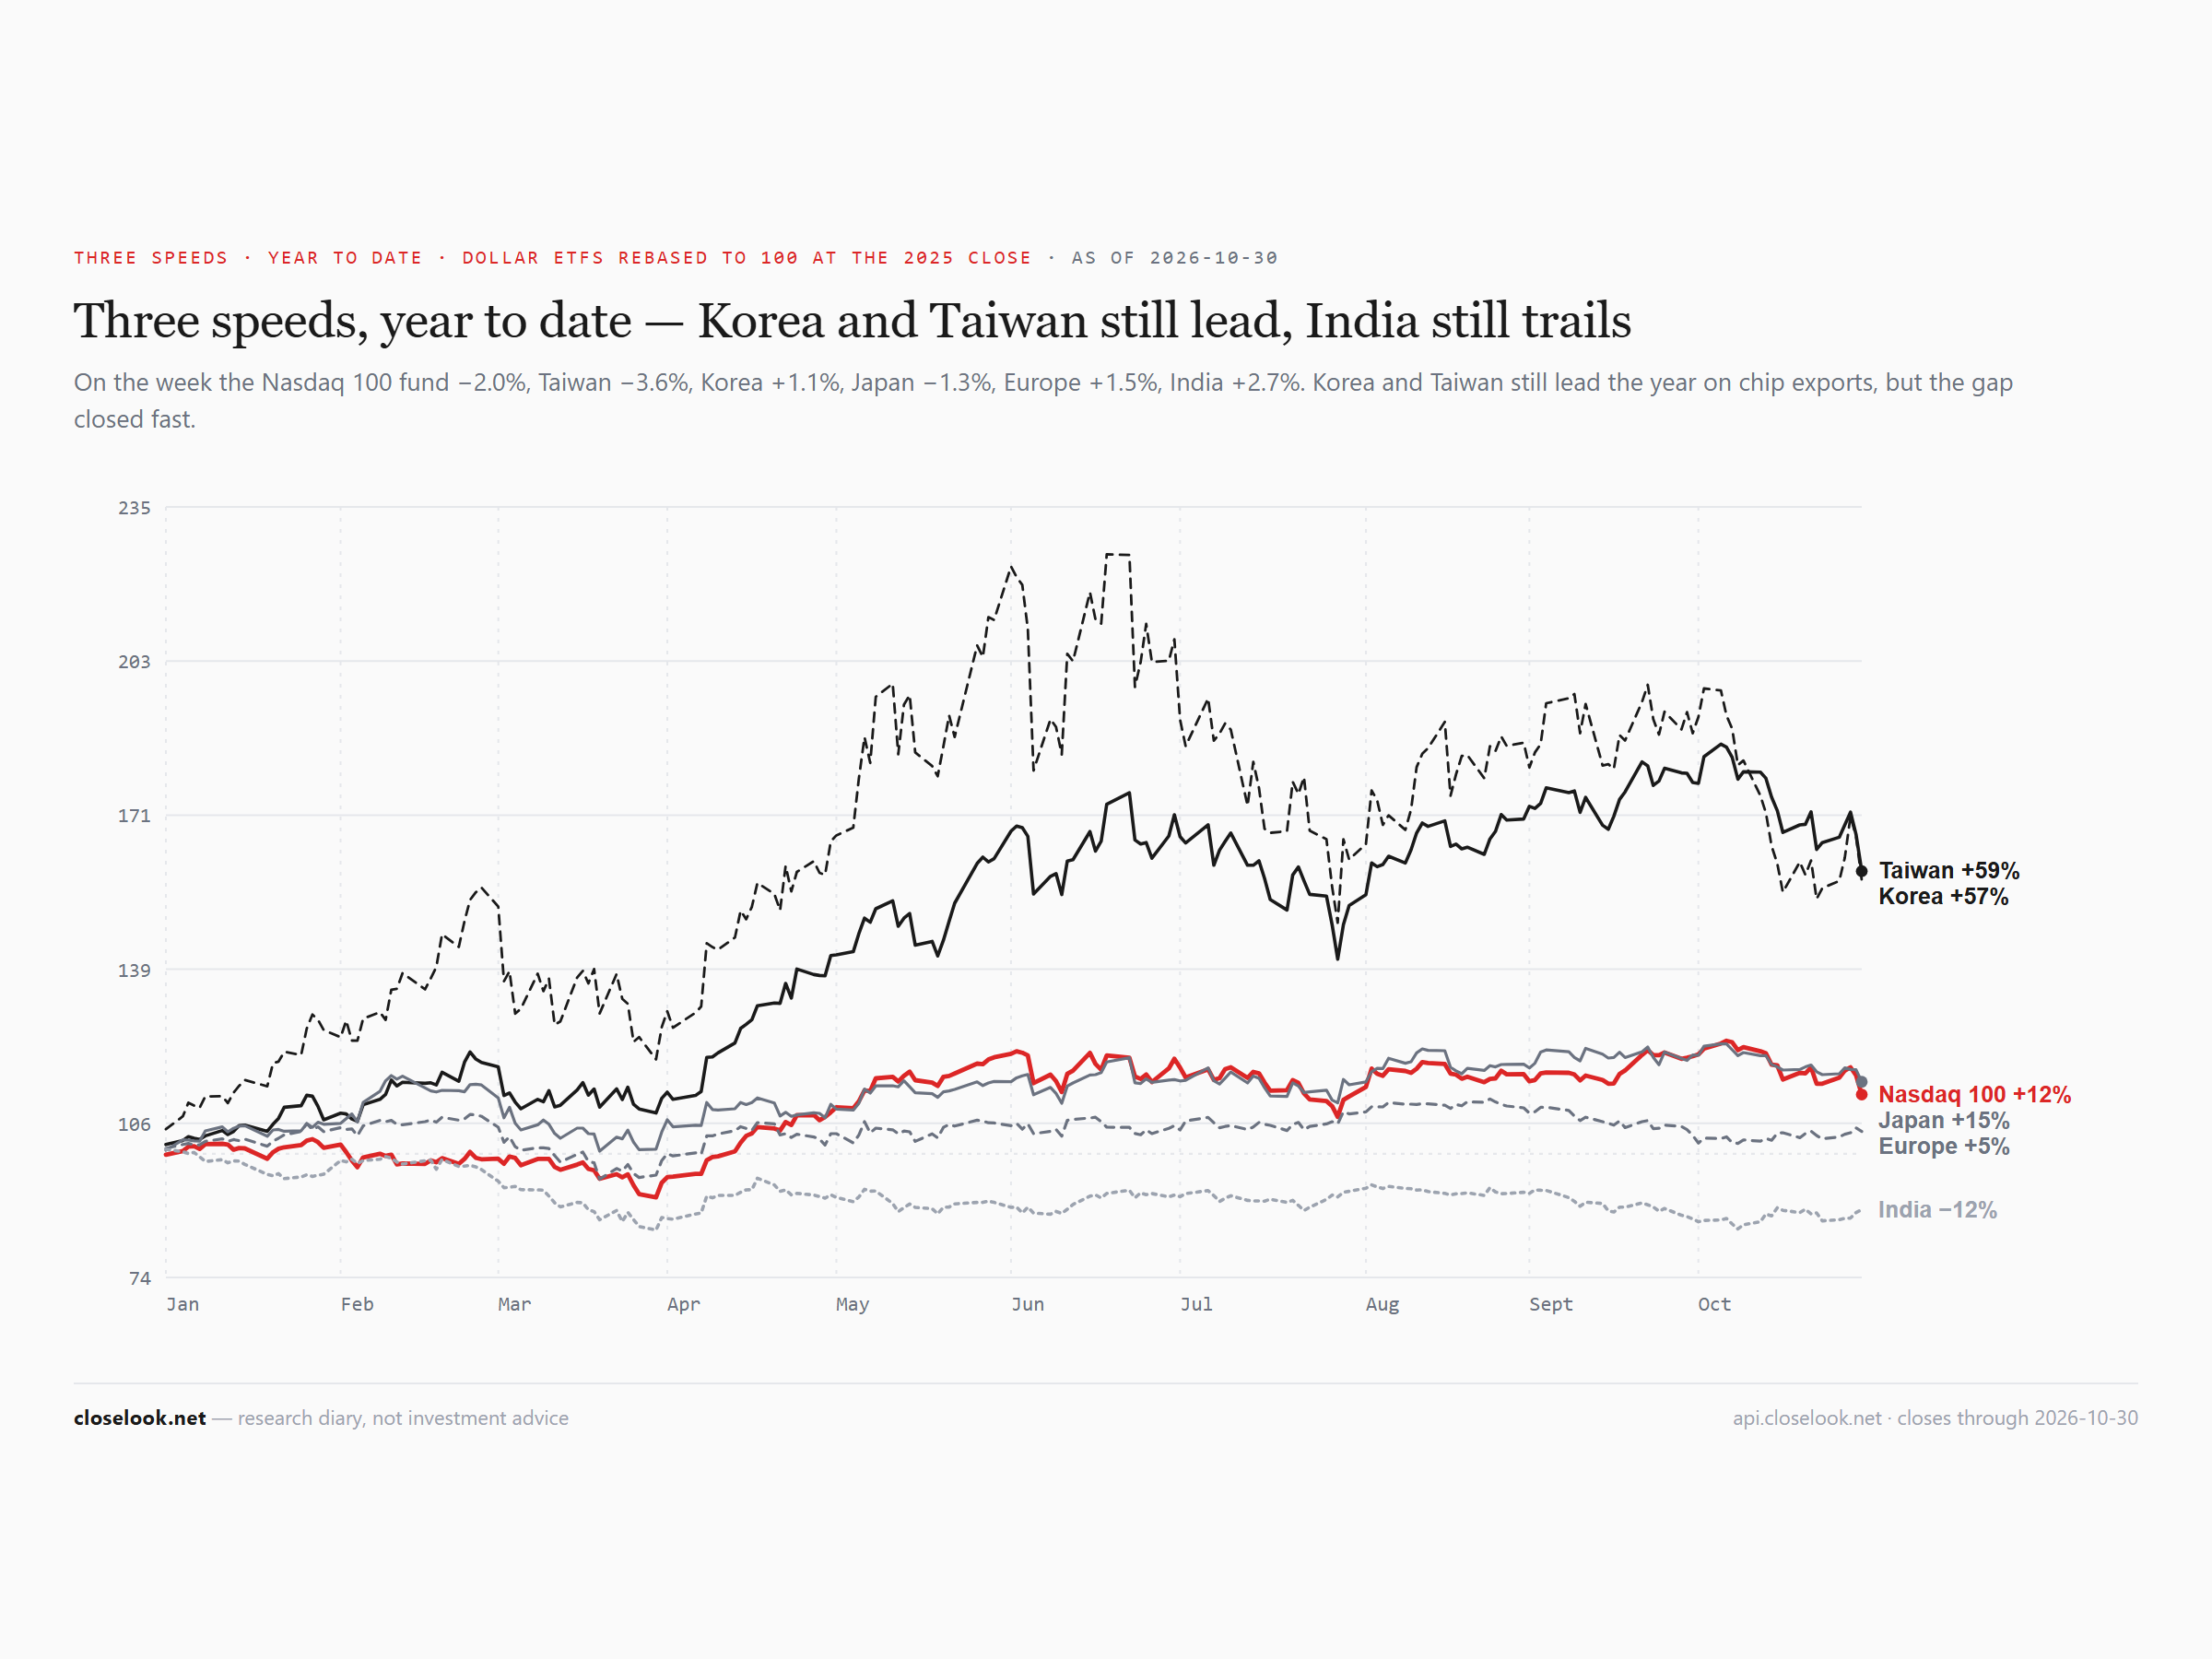
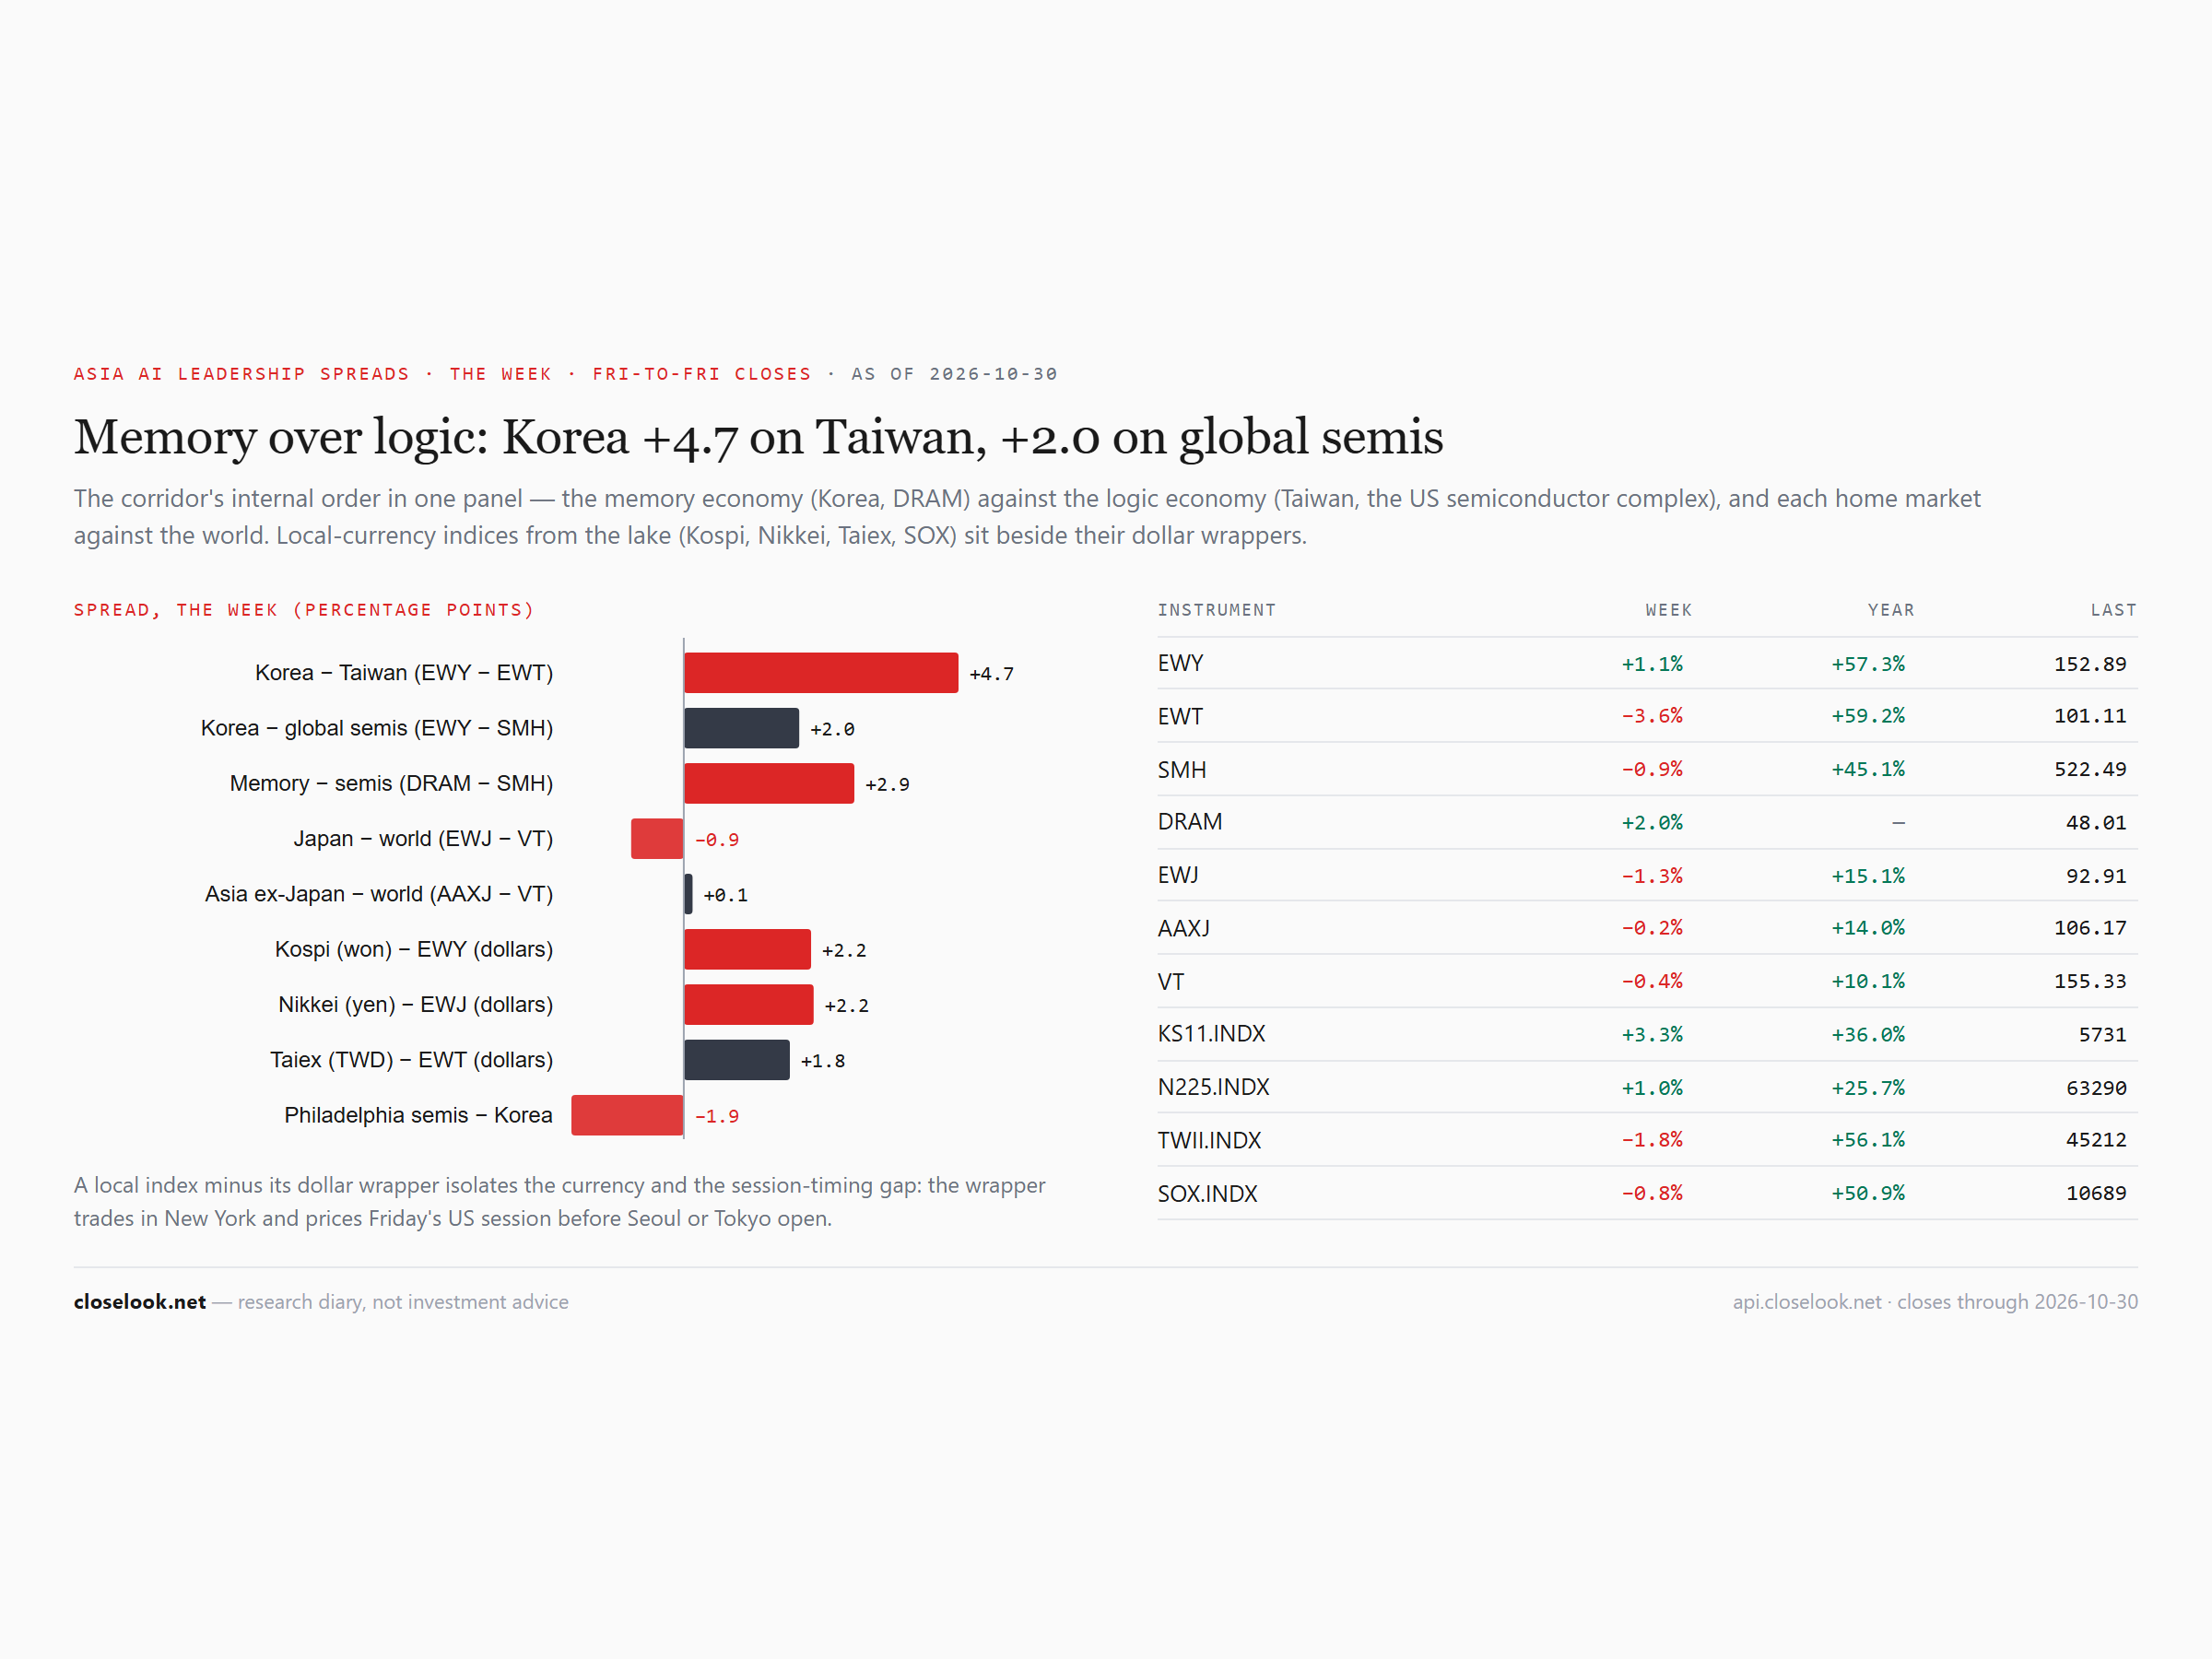
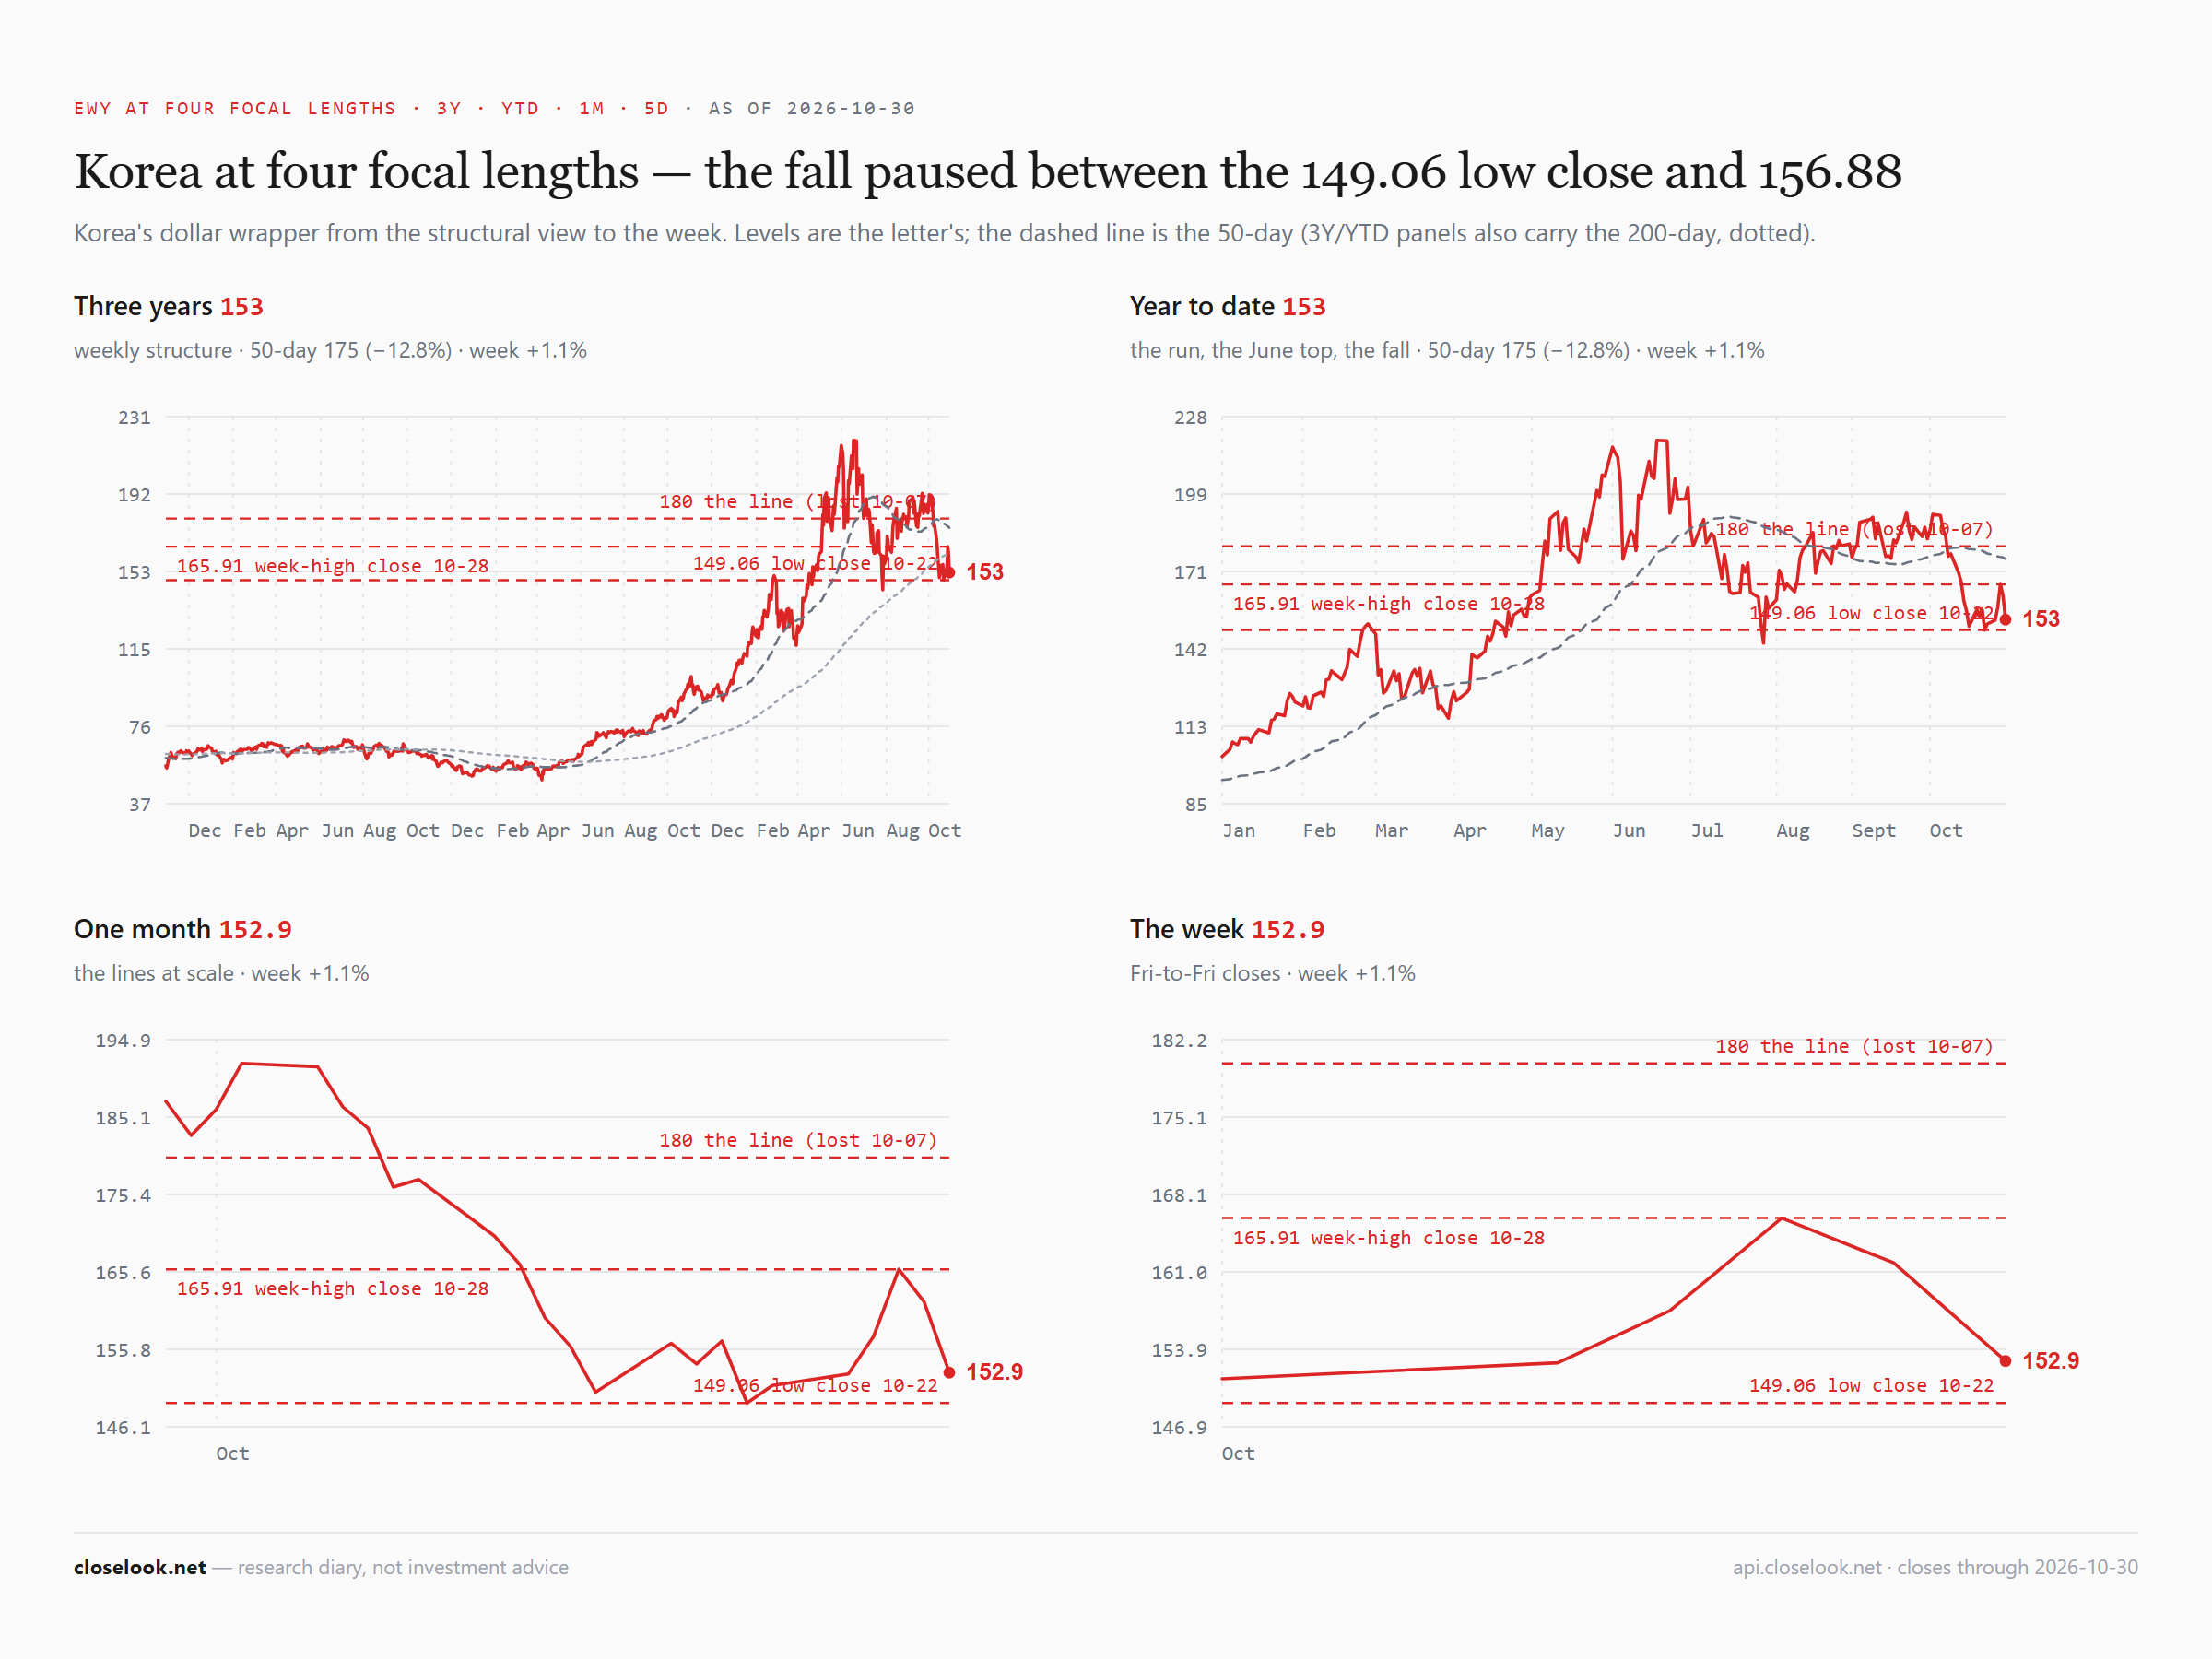
Asia took the Friday leg. Korea: the Kospi closed the week +3.3% at 5,731, but the dollar fund EWY fell 5.5% on Friday alone, from a week-high close of 165.91. Taiwan: the fund EWT −3.6% to 101.11, 14.3% under its October 5 record; the Taiex −1.8%. Japan: the Nikkei +1.0% to 63,290, the TOPIX flat, the dollar fund −1.3% — the Bank of Japan held at 1.25% on Thursday and more than doubled the pace of its ETF sales. Hong Kong +0.9%, China's large caps +2.4%, the A-shares −2.3%. India: the Nifty +2.0% to 23,053, the Sensex +1.8%, the dollar fund +2.7%.
The regional board — nineteen green of thirty-five. The top: Hong Kong +3.64%, India +2.71%, China large caps +2.38%, Germany +2.30%, Norway +2.17%, France +2.10%, Switzerland +2.09%, Austria +2.09%, Australia +1.44%, Korea +1.08%. The bottom: Brazil −23.78%, Argentina −9.07%, Indonesia −6.04%, Taiwan −3.61%, Thailand −3.40%, emerging markets (VWO) −2.34%, the A-shares −2.28%, Spain −2.02%.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| EWH | iShares MSCI Hong Kong | 22.52 | +3.64% | +1.85% | -3.35% | -5.06% | +5.98% |
| INDA | iShares MSCI India | 47.72 | +2.71% | +2.23% | -3.98% | -3.44% | -11.71% |
| FXI | iShares China Large-Cap | 33.08 | +2.38% | -2.76% | -9.42% | -10.08% | -13.61% |
| EWG | iShares MSCI Germany | 41.88 | +2.30% | +1.38% | -2.33% | -0.90% | -1.46% |
| ENOR | iShares MSCI Norway | 37.64 | +2.17% | +7.51% | +9.13% | +0.51% | +30.79% |
| EWQ | iShares MSCI France | 42.24 | +2.10% | -0.85% | -9.10% | -6.82% | -6.11% |
| EWL | iShares MSCI Switzerland | 64.37 | +2.09% | +8.83% | +0.70% | +4.89% | +7.35% |
| EWO | iShares MSCI Austria | 39.54 | +2.09% | -7.10% | -6.99% | +1.31% | +11.47% |
| EWA | iShares MSCI Australia | 29.54 | +1.44% | +4.34% | -0.94% | +0.17% | +12.79% |
| EWY | iShares MSCI South Korea | 152.89 | +1.08% | -16.35% | -5.16% | -4.90% | +57.26% |
| EWN | iShares MSCI Netherlands | 64.33 | +0.88% | -5.05% | -4.63% | +2.58% | +12.80% |
| FEZ | EURO STOXX 50 | 65.03 | +0.73% | -3.39% | -6.70% | -1.42% | +0.99% |
| EWM | iShares MSCI Malaysia | 26.87 | +0.71% | -1.86% | -4.92% | -8.51% | -1.79% |
| EFG | iShares MSCI EAFE Growth | 118.55 | +0.68% | -1.07% | -3.11% | -0.46% | +4.06% |
| EWU | iShares MSCI United Kingdom | 47.83 | +0.65% | +2.79% | -1.75% | +1.44% | +8.75% |
| VEA | Vanguard FTSE Developed Market | 69.44 | +0.56% | -1.66% | -2.32% | +0.93% | +11.16% |
| IMTM | iShares MSCI Intl Momentum Fac | 50.96 | +0.55% | -3.17% | -2.51% | -1.85% | +6.23% |
| EFV | iShares MSCI EAFE Value | 79.26 | +0.53% | +0.15% | -2.52% | +2.15% | +10.99% |
| EFAV | iShares MSCI EAFE Min Vol Fact | 96.25 | +0.29% | +5.63% | +2.44% | +4.92% | +11.59% |
| VEU | Vanguard FTSE All-World ex-US | 80.57 | -0.16% | -2.89% | -2.96% | -0.43% | +9.53% |
| EPOL | iShares MSCI Poland | 43.4 | -0.23% | -2.08% | +1.50% | +13.08% | +23.33% |
| VT | Vanguard Total World Stock | 155.33 | -0.37% | -1.60% | -0.08% | +2.73% | +10.12% |
| ENZL | iShares MSCI New Zealand | 44.81 | -0.79% | -0.61% | -5.19% | +0.42% | -1.03% |
| VSS | Vanguard FTSE All-World ex-US | 148.05 | -0.87% | -4.64% | -1.80% | -6.35% | +3.29% |
| EWW | iShares MSCI Mexico | 74.47 | -1.05% | +4.75% | -3.42% | -2.58% | +7.41% |
| EWJ | iShares MSCI Japan | 92.91 | -1.26% | -4.67% | -0.41% | +4.28% | +15.07% |
| ASEA | Global X - FTSE Southeast Asia | 19.84 | -1.53% | -5.33% | -6.58% | +1.55% | +8.26% |
| EWP | iShares MSCI Spain | 56.33 | -2.02% | -4.85% | -8.32% | -0.60% | +4.49% |
| ASHR | Xtrackers Harvest CSI 300 Chin | 30.04 | -2.28% | -8.05% | -12.34% | -14.95% | -8.55% |
| VWO | Vanguard FTSE Emerging Markets | 55.51 | -2.34% | -6.41% | -4.61% | -5.80% | +3.26% |
| THD | iShares MSCI Thailand | 68.46 | -3.40% | -2.91% | -5.10% | -3.18% | +14.73% |
| EWT | iShares MSCI Taiwan | 101.11 | -3.61% | -10.44% | +7.56% | +12.49% | +59.15% |
| EIDO | iShares MSCI Indonesia | 9.96 | -6.04% | -15.09% | -19.48% | -33.29% | -46.74% |
| ARGT | Global X - MSCI Argentina | 79.18 | -9.07% | -8.12% | -17.65% | -13.09% | -13.38% |
| EWZ | iShares MSCI Brazil | 32.46 | -23.78% | -12.86% | -11.14% | -18.24% | +2.17% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The cross-asset backdrop — the bonds held, everything that glitters fell. Three green of twelve: the belly +0.78%, the long bond +0.61% to 81.84, the dollar +0.14%. The red: silver −8.46% — to its lowest close of 2026, 44.60 — the bitcoin fund −5.66%, gold −2.95% to 355.78 — its lowest close of the past year — the Nasdaq top-30 fund −2.39%, the Nasdaq 100 −1.97%, copper miners −1.55%, the US top-20 fund −0.87%, the S&P −0.56% and oil −0.41%. Oil gave back a little of last week's high; the Brent fund rose 0.56% to 71.39, a new record close. The volatility index closed at 19.42, after a week that ran from 16.21 to 23.93.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| IEF | iShares 7-10 Year Treasury Bon | 91.76 | +0.78% | +2.74% | -1.56% | -3.39% | -4.58% |
| TLT | iShares 20+ Year Treasury Bond | 81.84 | +0.61% | +5.22% | -1.16% | -4.41% | -6.10% |
| UUP | Invesco DB US Dollar Index Bul | 29 | +0.14% | +0.80% | +3.06% | +5.99% | +7.29% |
| USO | United States Oil LP | 168.83 | -0.41% | +15.91% | +32.44% | +14.78% | +144.12% |
| SPY | S&P 500 | 755.72 | -0.56% | -0.91% | +1.89% | +5.16% | +10.82% |
| TOPT | iShares Top 20 U.S. Stocks | 34.03 | -0.87% | -2.49% | +4.90% | +6.05% | +8.97% |
| COPX | Global X - Copper Miners | 71.96 | -1.55% | -15.04% | -9.48% | -9.61% | +0.24% |
| QQQ | Invesco QQQ | 690.49 | -1.97% | -6.66% | +1.02% | +3.41% | +12.40% |
| QTOP | iShares Nasdaq Top 30 Stocks | 35.87 | -2.39% | -8.56% | +0.90% | +1.96% | +12.23% |
| GLD | Gold Shares | 355.78 | -2.95% | -6.58% | -5.67% | -16.02% | -10.23% |
| IBIT | iShares Bitcoin | 43.36 | -5.66% | -8.41% | +18.15% | +0.09% | -12.67% |
| SLV | iShares Silver | 44.6 | -8.46% | -18.18% | -16.64% | -33.09% | -30.77% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The tech ETFs — five of twenty-one green, and software at the bottom. Last week's leaders became this week's losers: cloud (CLOU) −7.56%, software (IGV) −5.70%, digital transformation −5.60%, the internet fund −5.31%, cybersecurity −4.80%, the AI fund AIQ −3.45%. The green was small and physical: defence technology +3.05%, uranium and nuclear +1.52%, the internet of things +1.26%, the smart grid +1.12%, data centres +0.55%. The chip funds ended almost flat on the week — XSD −0.36%, the fabless fund −0.78%, SMH −0.89% — because Monday to Wednesday paid for Friday.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| SHLD | Global X - Defense Tech | 63.78 | +3.05% | +6.16% | +1.61% | -6.49% | -1.56% |
| NLR | VanEck Uranium and Nuclear | 91.75 | +1.52% | -11.32% | -15.33% | -37.14% | -26.13% |
| SNSR | Global X - Internet of Things | 46.54 | +1.26% | -4.70% | +1.56% | +4.38% | +25.93% |
| GRID | First NASDAQ Clean Edge Smart | 164.51 | +1.12% | -7.11% | -6.87% | -13.86% | +7.51% |
| DTCR | Global X - Data Center & Digit | 25.57 | +0.55% | -5.78% | -7.66% | -11.34% | +21.18% |
| XSD | S&P Semiconductor | 452.1 | -0.36% | -14.64% | -6.41% | -7.37% | +40.58% |
| SMHX | VanEck Fabless Semiconductor | 51.75 | -0.78% | -14.63% | -4.05% | +1.60% | +36.06% |
| SMH | VanEck Semiconductor | 522.49 | -0.89% | -14.21% | -3.05% | +3.11% | +45.08% |
| WTAI | WisdomTree Artificial Intellig | 36.28 | -0.96% | -16.96% | -4.58% | +1.97% | +24.50% |
| LIT | Global X - Lithium & Battery T | 59.81 | -1.43% | -12.58% | -14.32% | -32.22% | -7.79% |
| ARKK | ARK Innovation | 80.75 | -1.51% | -9.37% | +10.77% | +6.47% | +4.98% |
| QTUM | Defiance Quantum | 133.83 | -1.74% | -11.73% | -4.62% | -0.15% | +22.04% |
| FINX | Global X - FinTech | 23.89 | -2.31% | -1.54% | -8.06% | -5.40% | -18.84% |
| BOTZ | Global X - Robotics & Artifici | 32.22 | -2.42% | -8.54% | -7.68% | -16.20% | -11.07% |
| ESPO | VanEck Video Gaming and eSport | 96.19 | -2.93% | -0.33% | -1.10% | +4.35% | -7.16% |
| AIQ | Global X - Artificial Intellig | 60.14 | -3.45% | -7.70% | +2.47% | +7.62% | +18.25% |
| CIBR | First Nasdaq Cybersecurity | 101.03 | -4.80% | -2.00% | +12.23% | +49.79% | +41.40% |
| FDN | First Dow Jones Internet Index | 266.23 | -5.31% | -7.70% | -0.60% | +1.06% | -1.10% |
| DAPP | VanEck Digital Transformation | 14.17 | -5.60% | -25.26% | -22.36% | -24.63% | -14.28% |
| IGV | iShares Expanded Tech-Software | 104.29 | -5.70% | -2.06% | +11.77% | +24.29% | -1.32% |
| CLOU | Global X - Cloud Computing | 28.02 | -7.56% | -1.55% | +12.76% | +40.31% | +23.87% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
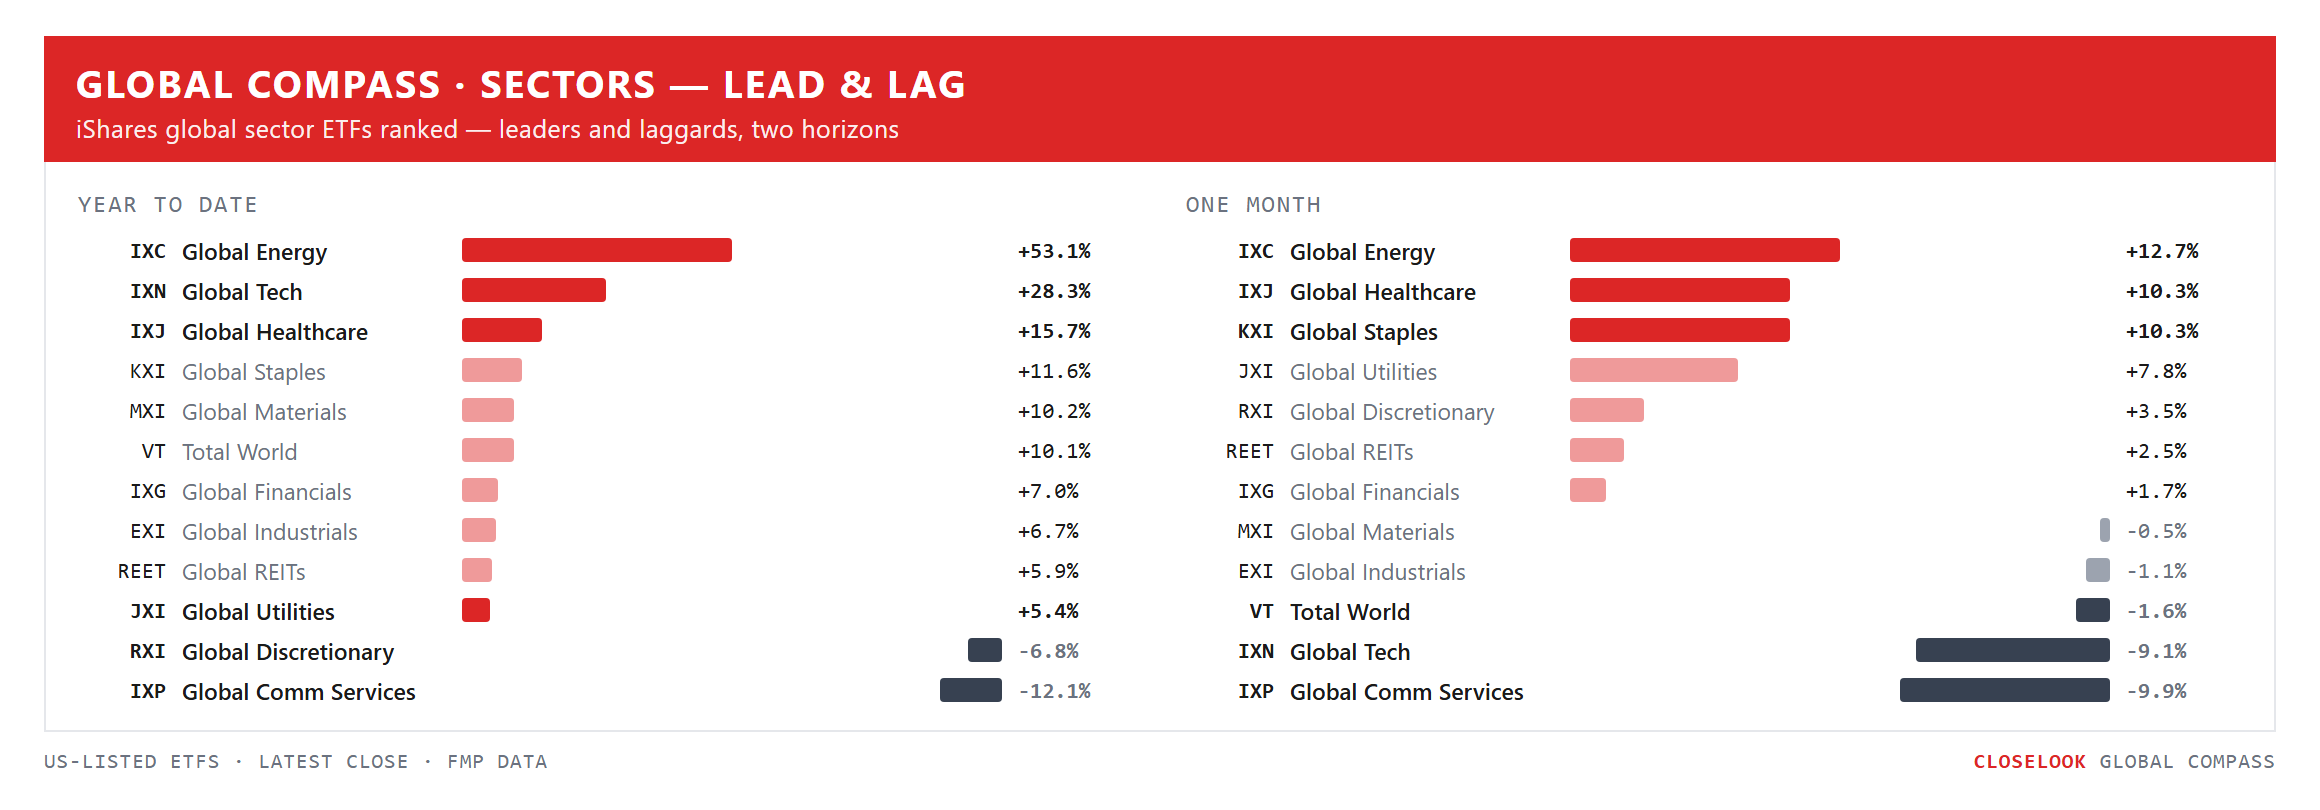
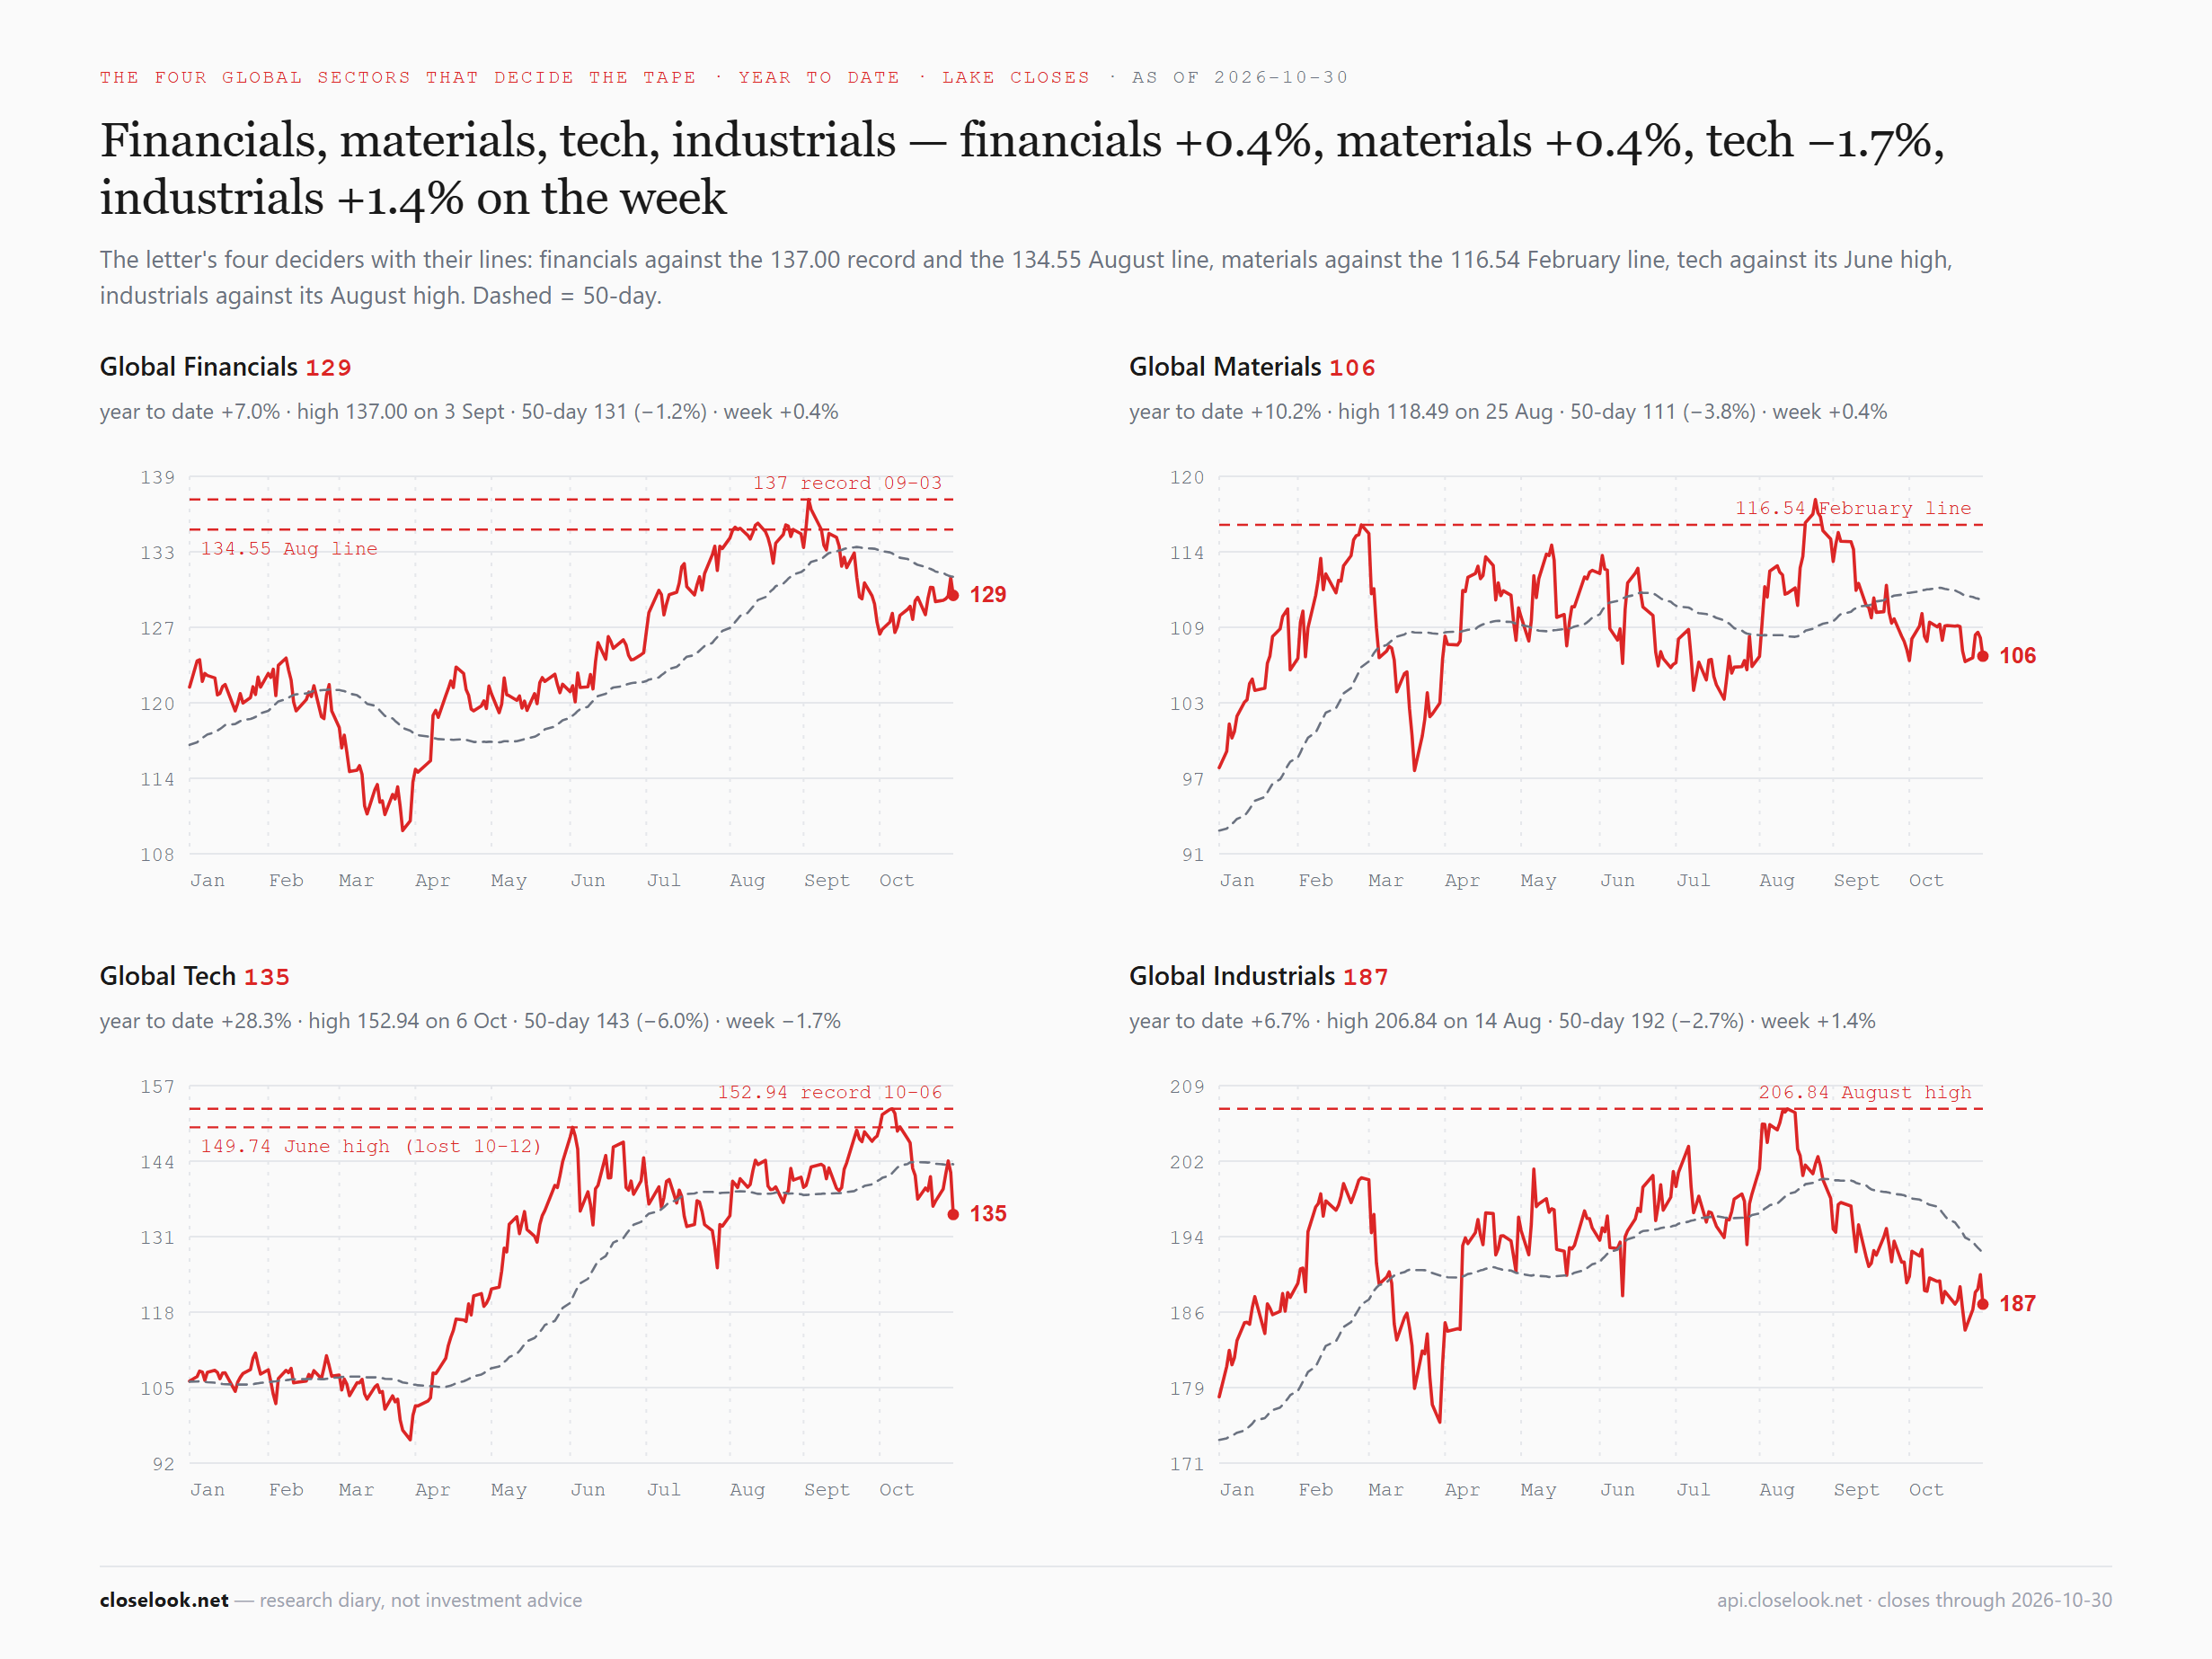
The global sectors — nine of eleven green, health care first. Health care +2.98% to 112.66 — above last week's one-year closing high of 110.35 — utilities +1.43%, industrials +1.41%, real estate +1.11%, discretionary +0.79%, staples +0.64%, energy +0.49% to 64.19, a record close of the year, financials +0.40%, materials +0.40%. The red: communication −4.13% and technology −1.66%. The world index itself fell 0.37%. Nine sectors up and the index down is what it looks like when the two biggest sectors carry the weight.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| IXJ | iShares Global Healthcare | 112.66 | +2.98% | +10.32% | +11.28% | +21.23% | +15.67% |
| JXI | iShares Global Utilities | 82.92 | +1.43% | +7.84% | -1.33% | -6.56% | +5.43% |
| EXI | iShares Global Industrials | 187.11 | +1.41% | -1.14% | -5.14% | -4.49% | +6.71% |
| REET | iShares Global REIT | 26.43 | +1.11% | +2.52% | -7.43% | -3.26% | +5.93% |
| RXI | iShares Global Consumer Discre | 191.28 | +0.79% | +3.47% | -2.34% | -3.44% | -6.81% |
| KXI | iShares Global Consumer Staple | 72.16 | +0.64% | +10.29% | +3.40% | +5.05% | +11.62% |
| IXC | iShares Global Energy | 64.19 | +0.49% | +12.67% | +15.91% | +12.99% | +53.09% |
| IXG | iShares Global Financials | 129.19 | +0.40% | +1.72% | -3.00% | +6.07% | +6.95% |
| MXI | iShares Global Materials | 106.46 | +0.40% | -0.50% | -1.42% | -3.37% | +10.16% |
| VT | Vanguard Total World Stock | 155.33 | -0.37% | -1.60% | -0.08% | +2.73% | +10.12% |
| IXN | iShares Global Tech | 134.69 | -1.66% | -9.13% | +1.30% | +12.01% | +28.28% |
| IXP | iShares Global Comm Services | 106.58 | -4.13% | -9.88% | -5.72% | -13.69% | -12.08% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
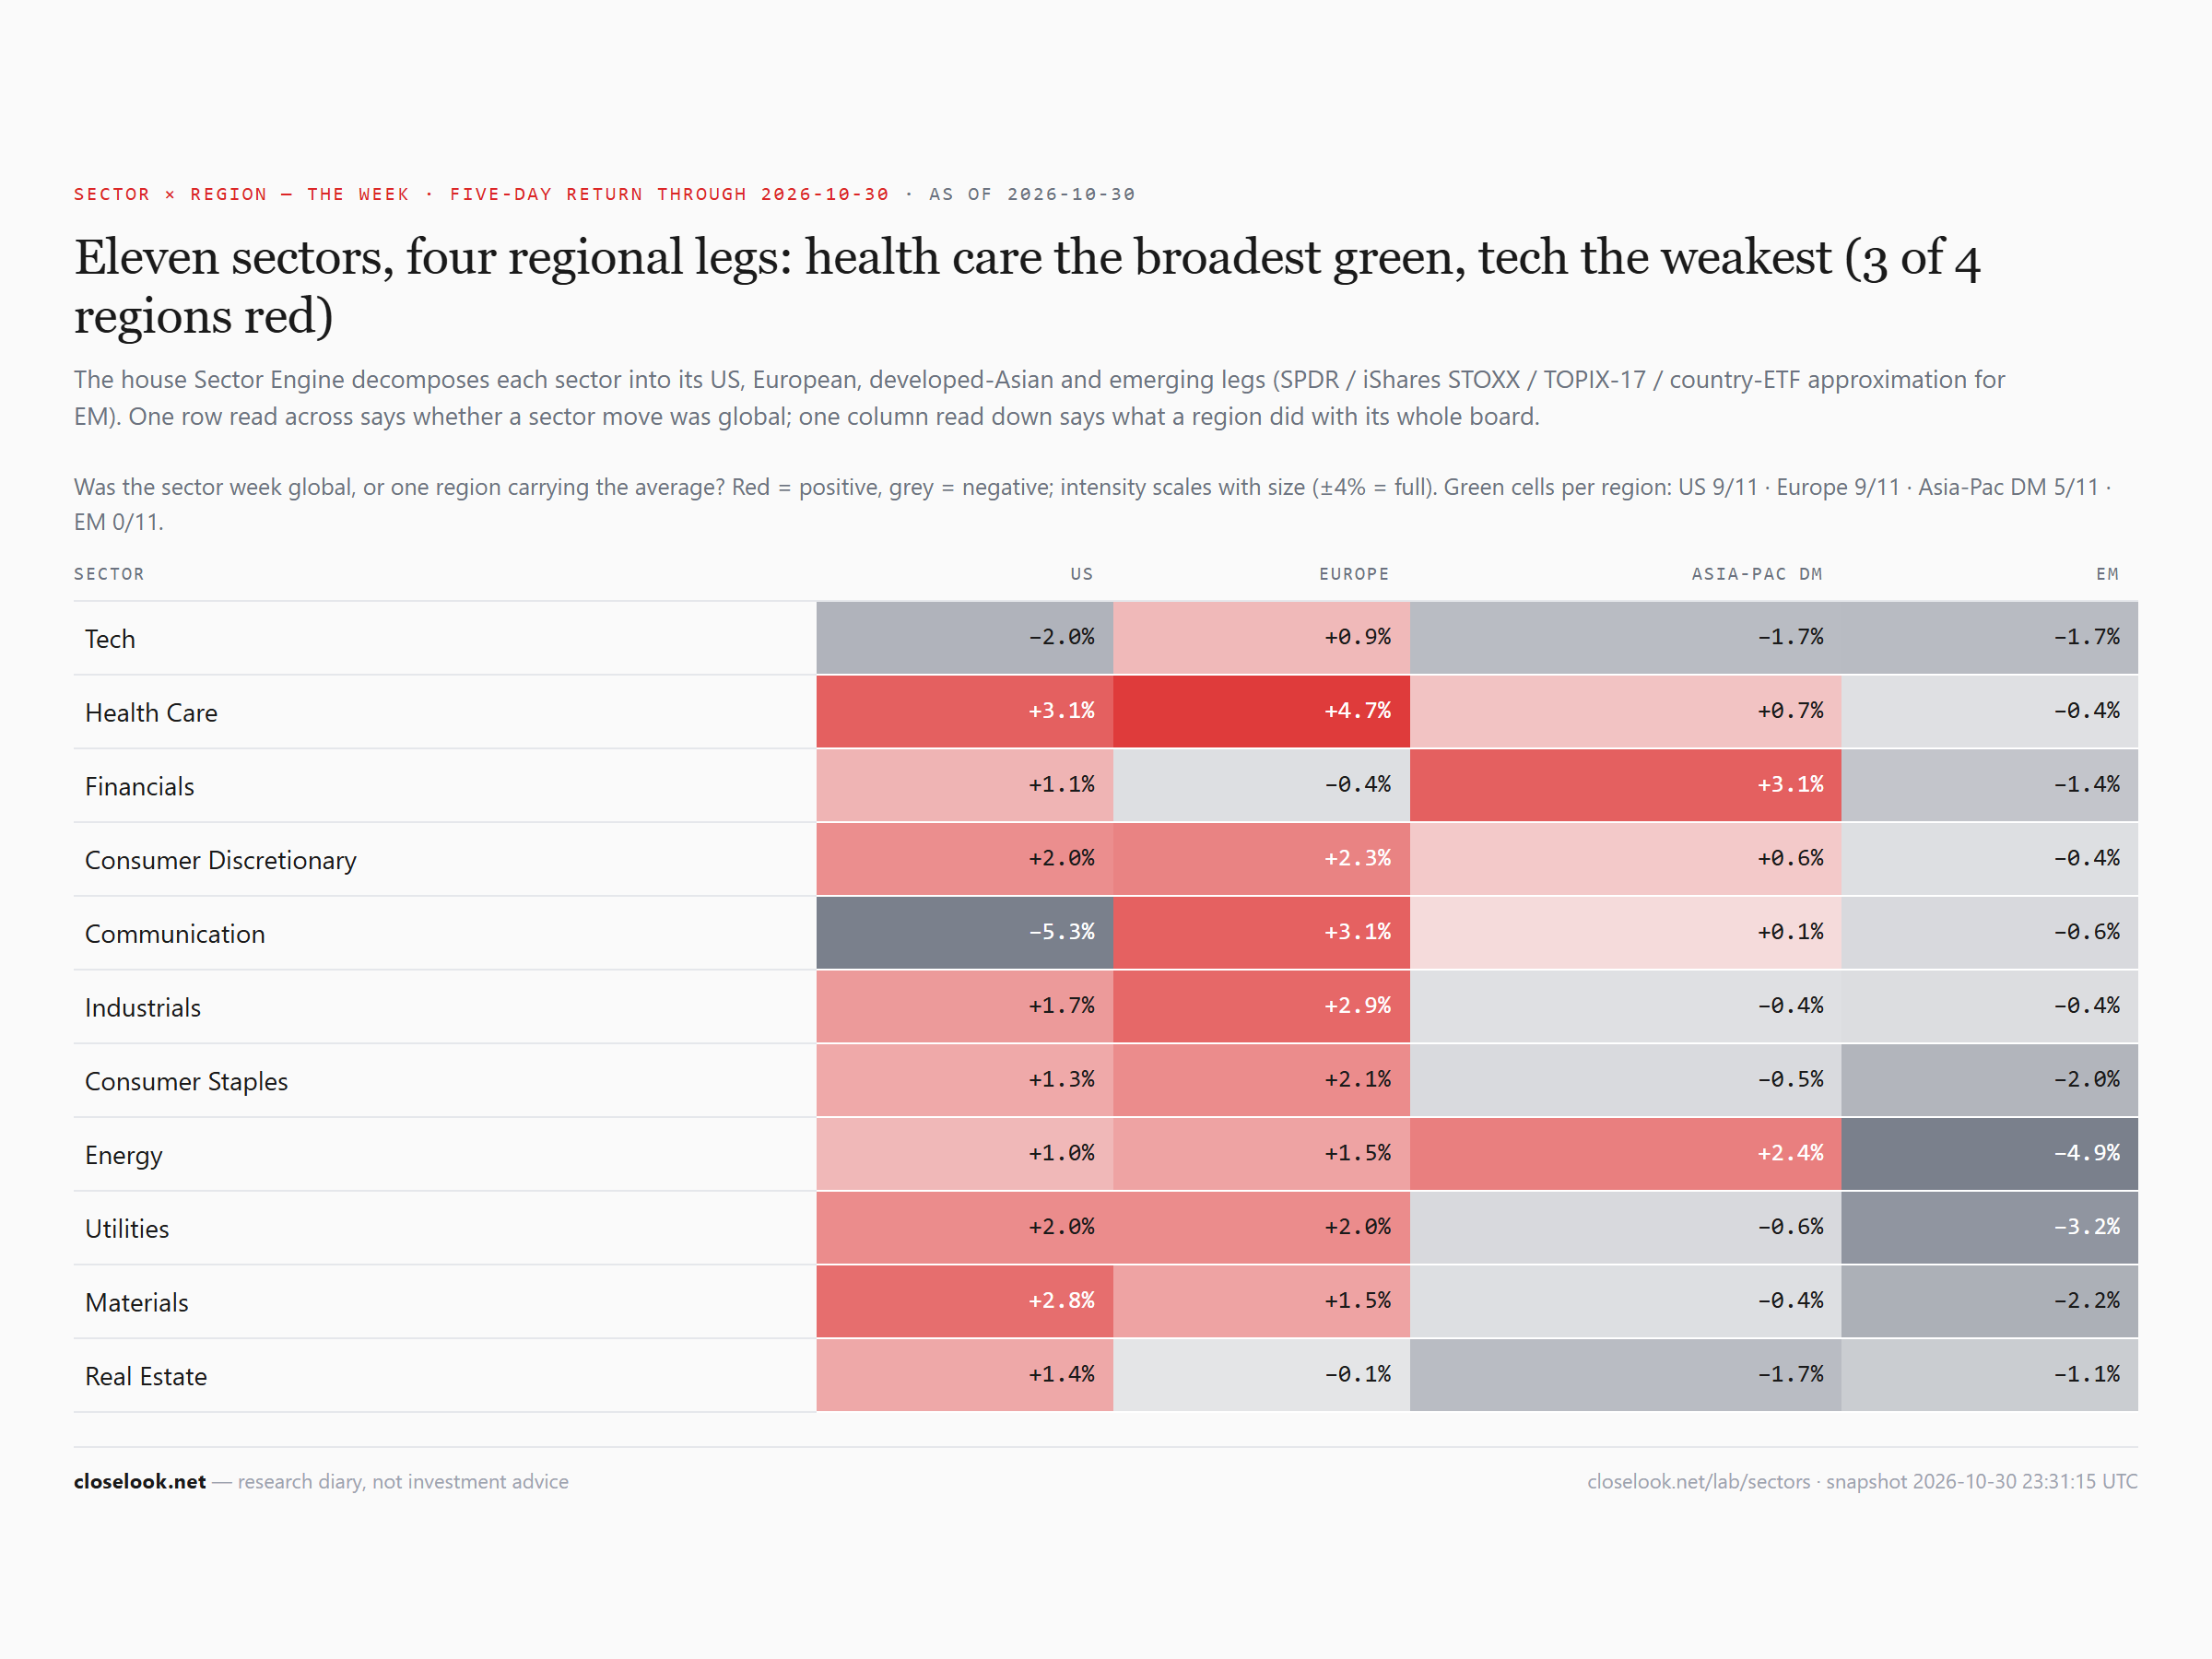
Was the sector week global, or one region carrying it? Health care rose in America (+3.1%), Europe (+4.7%) and developed Asia (+0.7%) and slipped 0.4% in the emerging markets. Technology: America −2.0%, Europe +0.9%, developed Asia −1.7%, emerging markets −1.7% — a third week running that Europe's software-heavy tech beat Asia's chip-heavy tech. Communication services: America −5.3%, Europe +3.1% — the widest US-minus-Europe spread in the matrix, −8.4 points, the sector where Alphabet and Meta sit.
The Global Compass
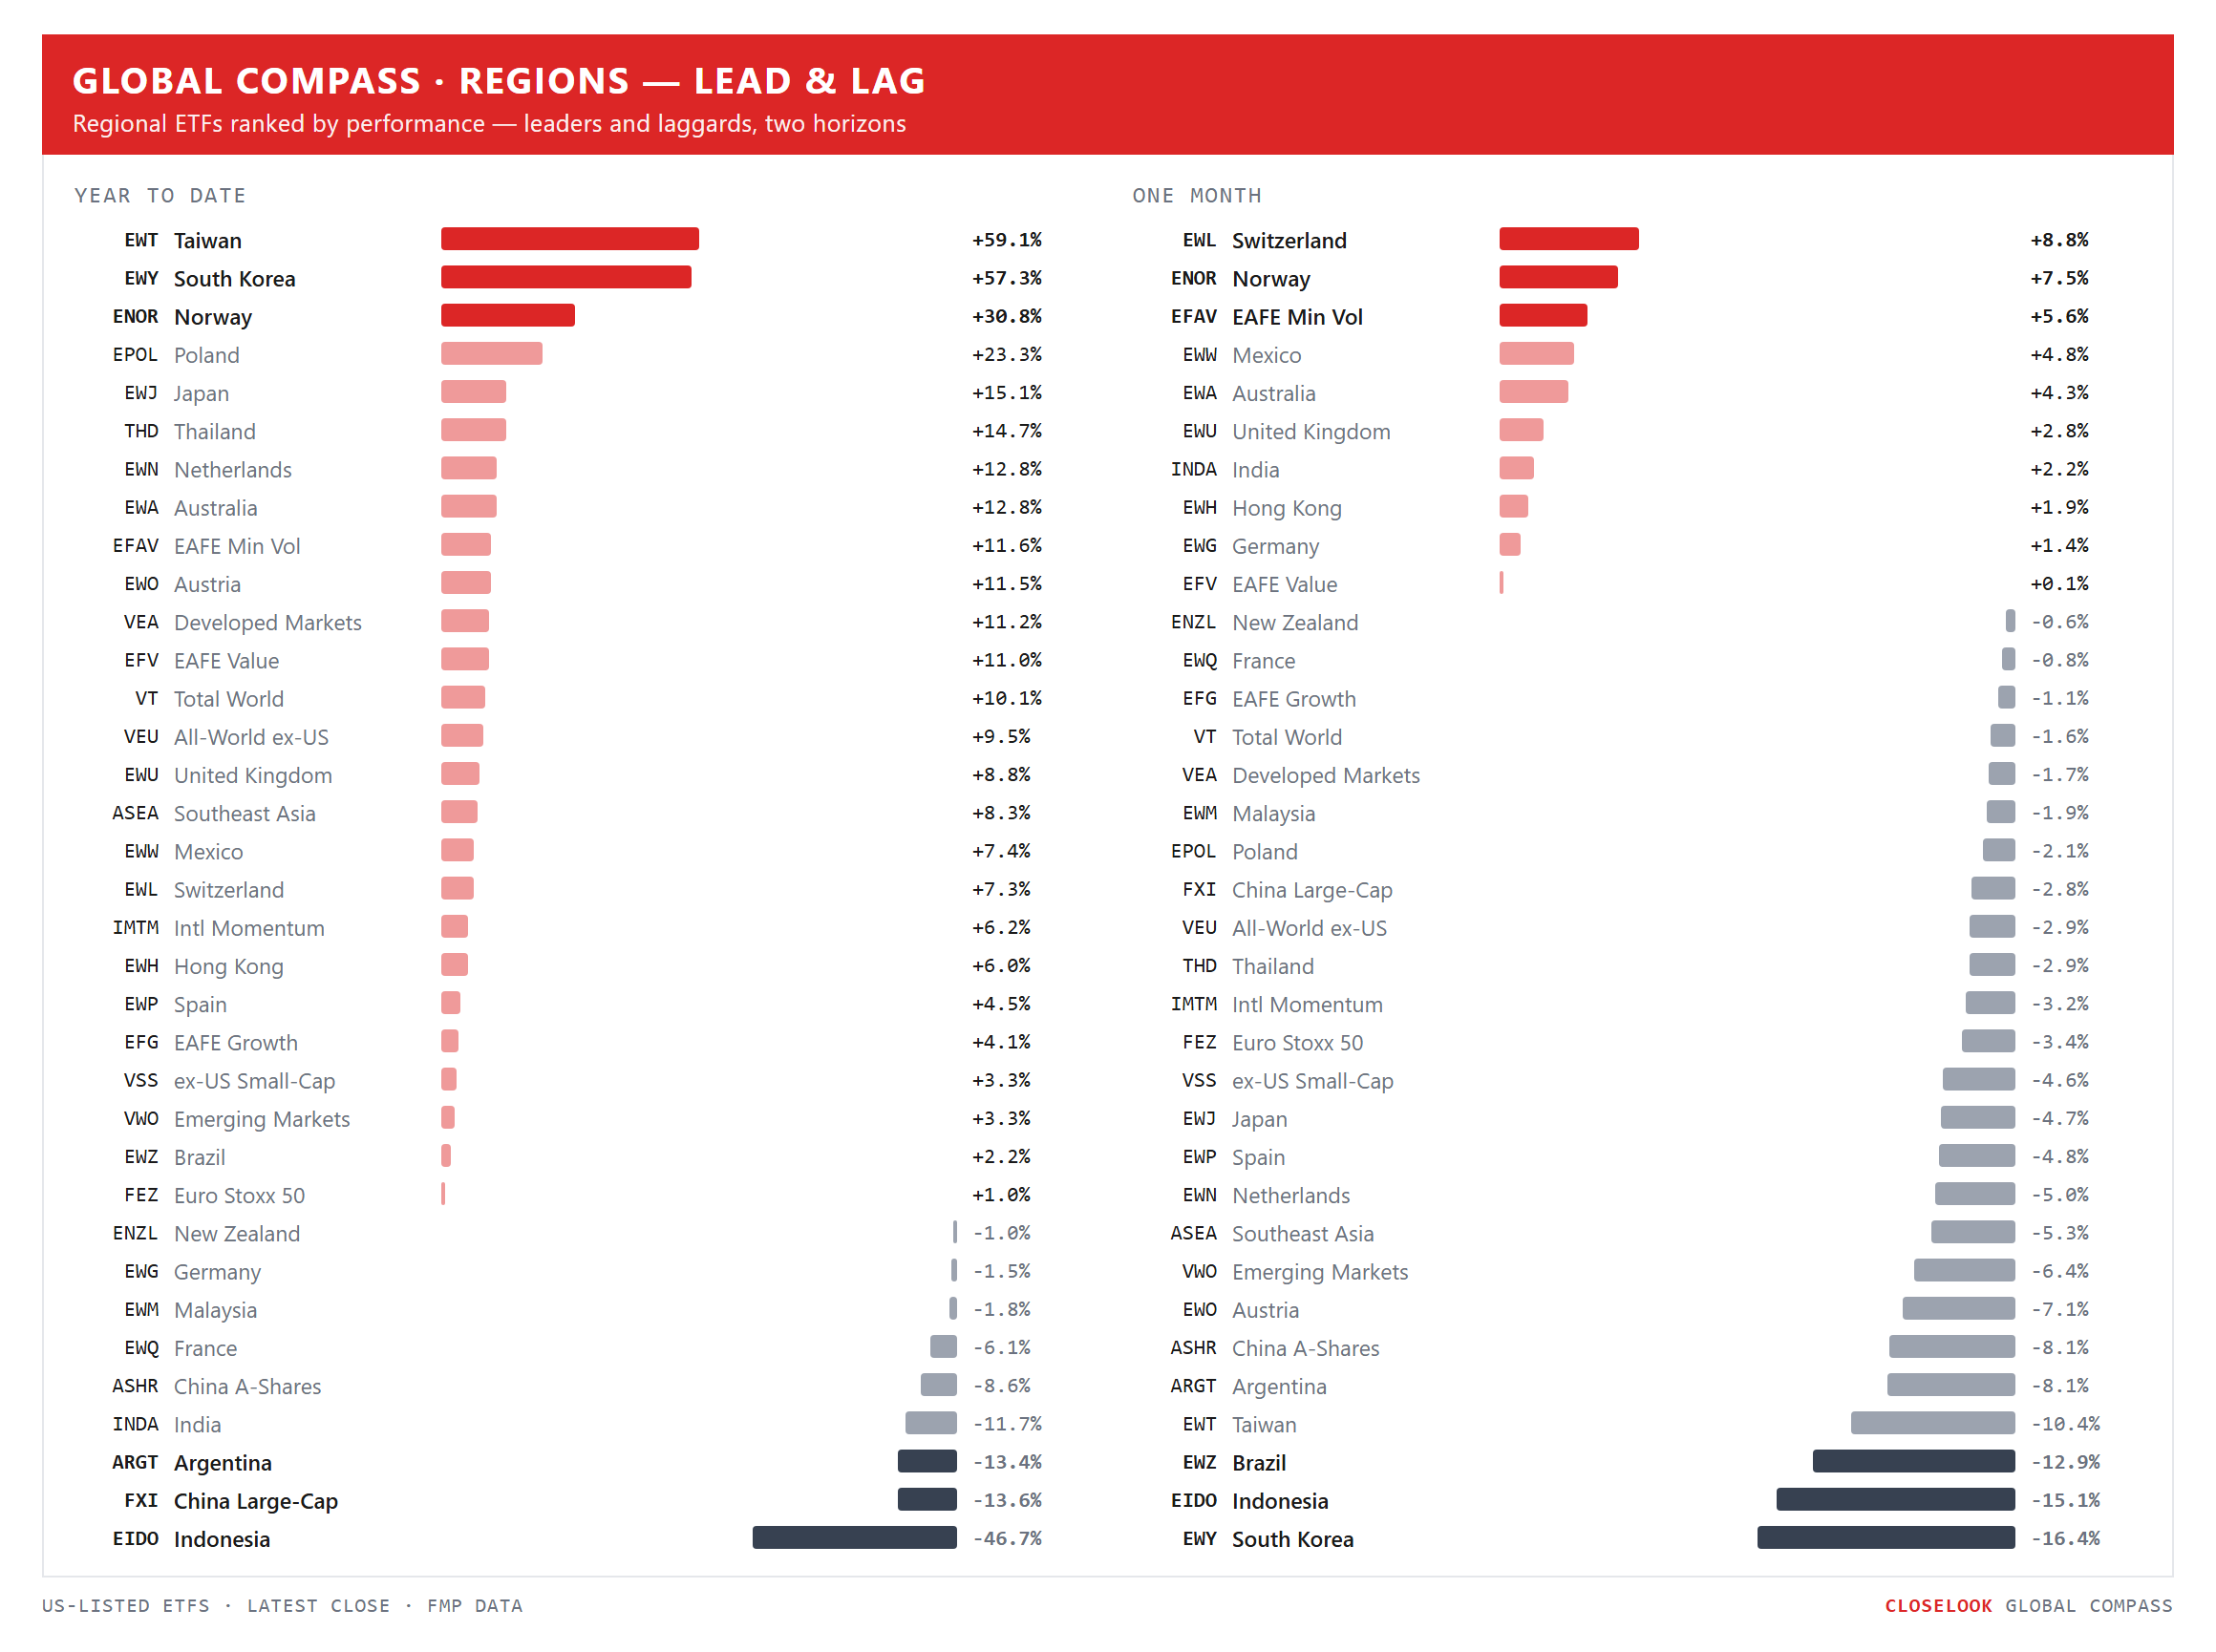
Regions: developed over emerging, a third week. VEA +0.56% against VWO −2.34%. The emerging basket carries Brazil, Taiwan and the A-shares, three of the week's losers. The developed basket carries Germany, Switzerland and Australia, three of its winners.
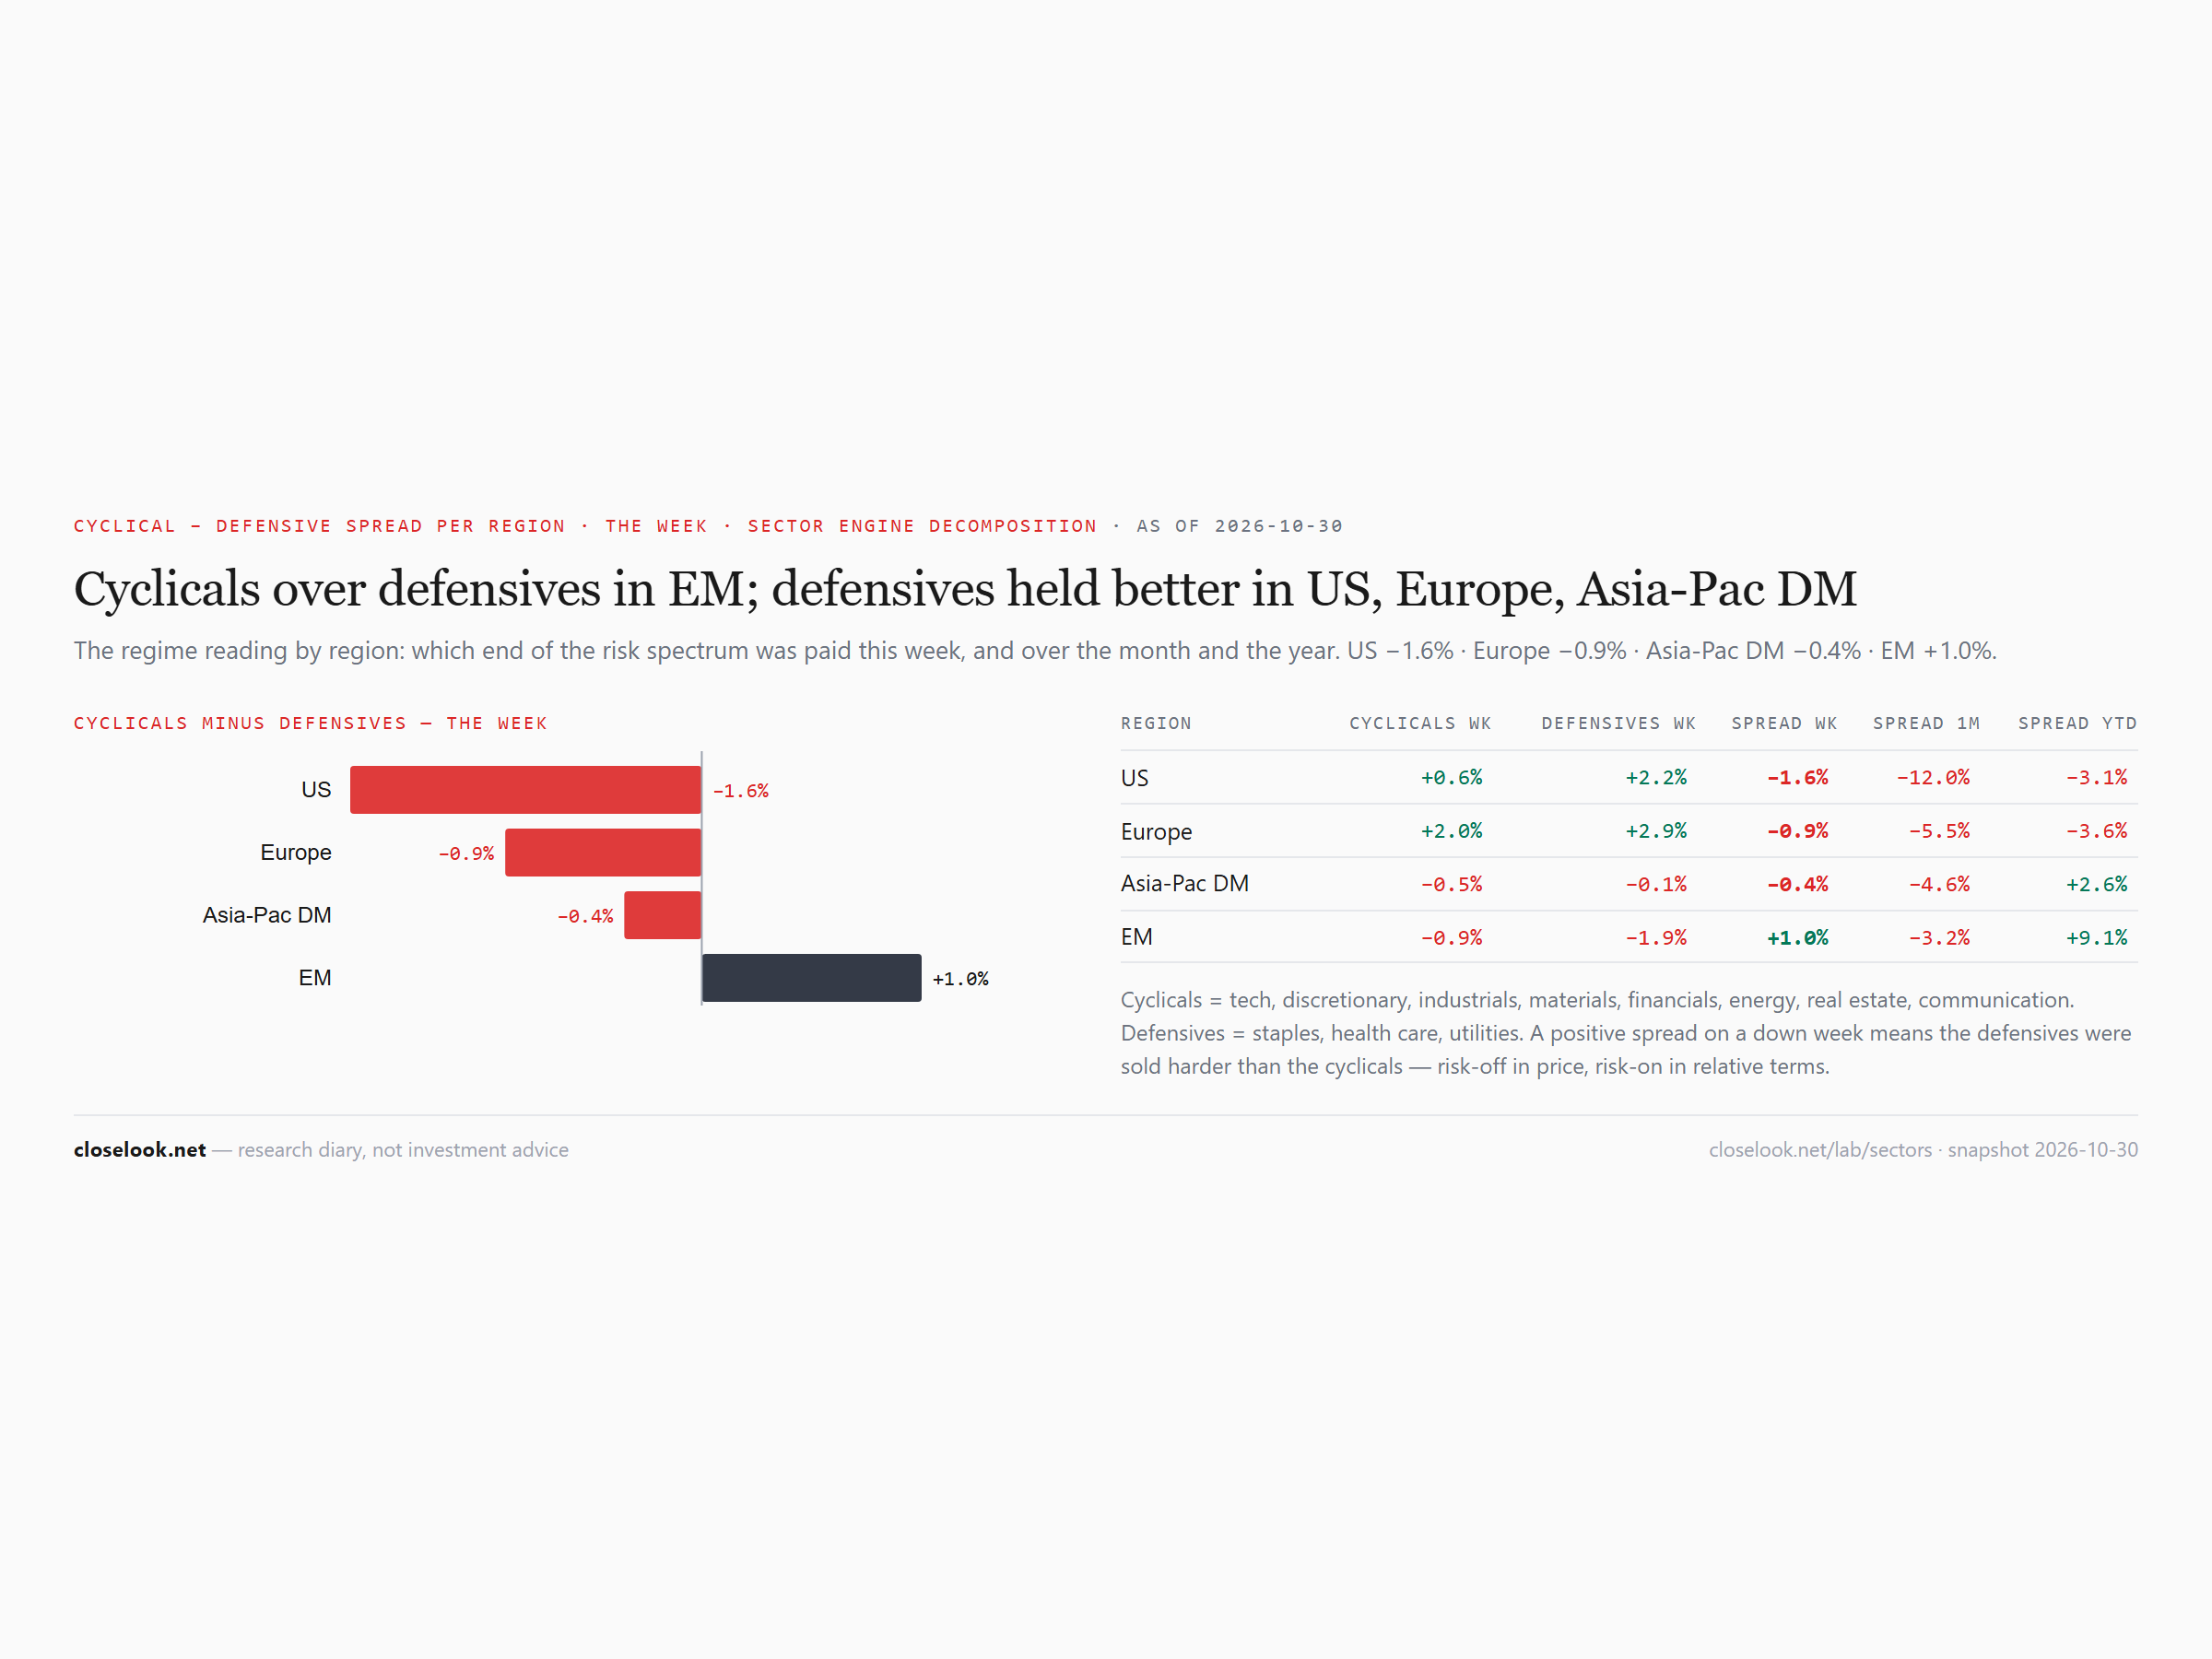
Sectors: defensives over cyclicals in three of four regions, a fourth week. The engine's cyclical-minus-defensive spread was −1.6 points in the US, −0.9 in Europe, −0.4 in developed Asia and +1.0 in the emerging markets. On the month the US spread is −12.0 points. On the year it has turned negative, −3.1 points, from +4.6 a week ago. For 2026 as a whole, America's defensive sectors are now ahead of its cyclical ones.
Sectors: the leaders' bench. Technology 134.69, 11.9% under its October 6 record. Industrials 187.11, 9.5% under August. Financials 129.19, 5.7% under the September 3 record, an eighth week under the 134.55 line. Materials 106.46, a tenth week under the February line.
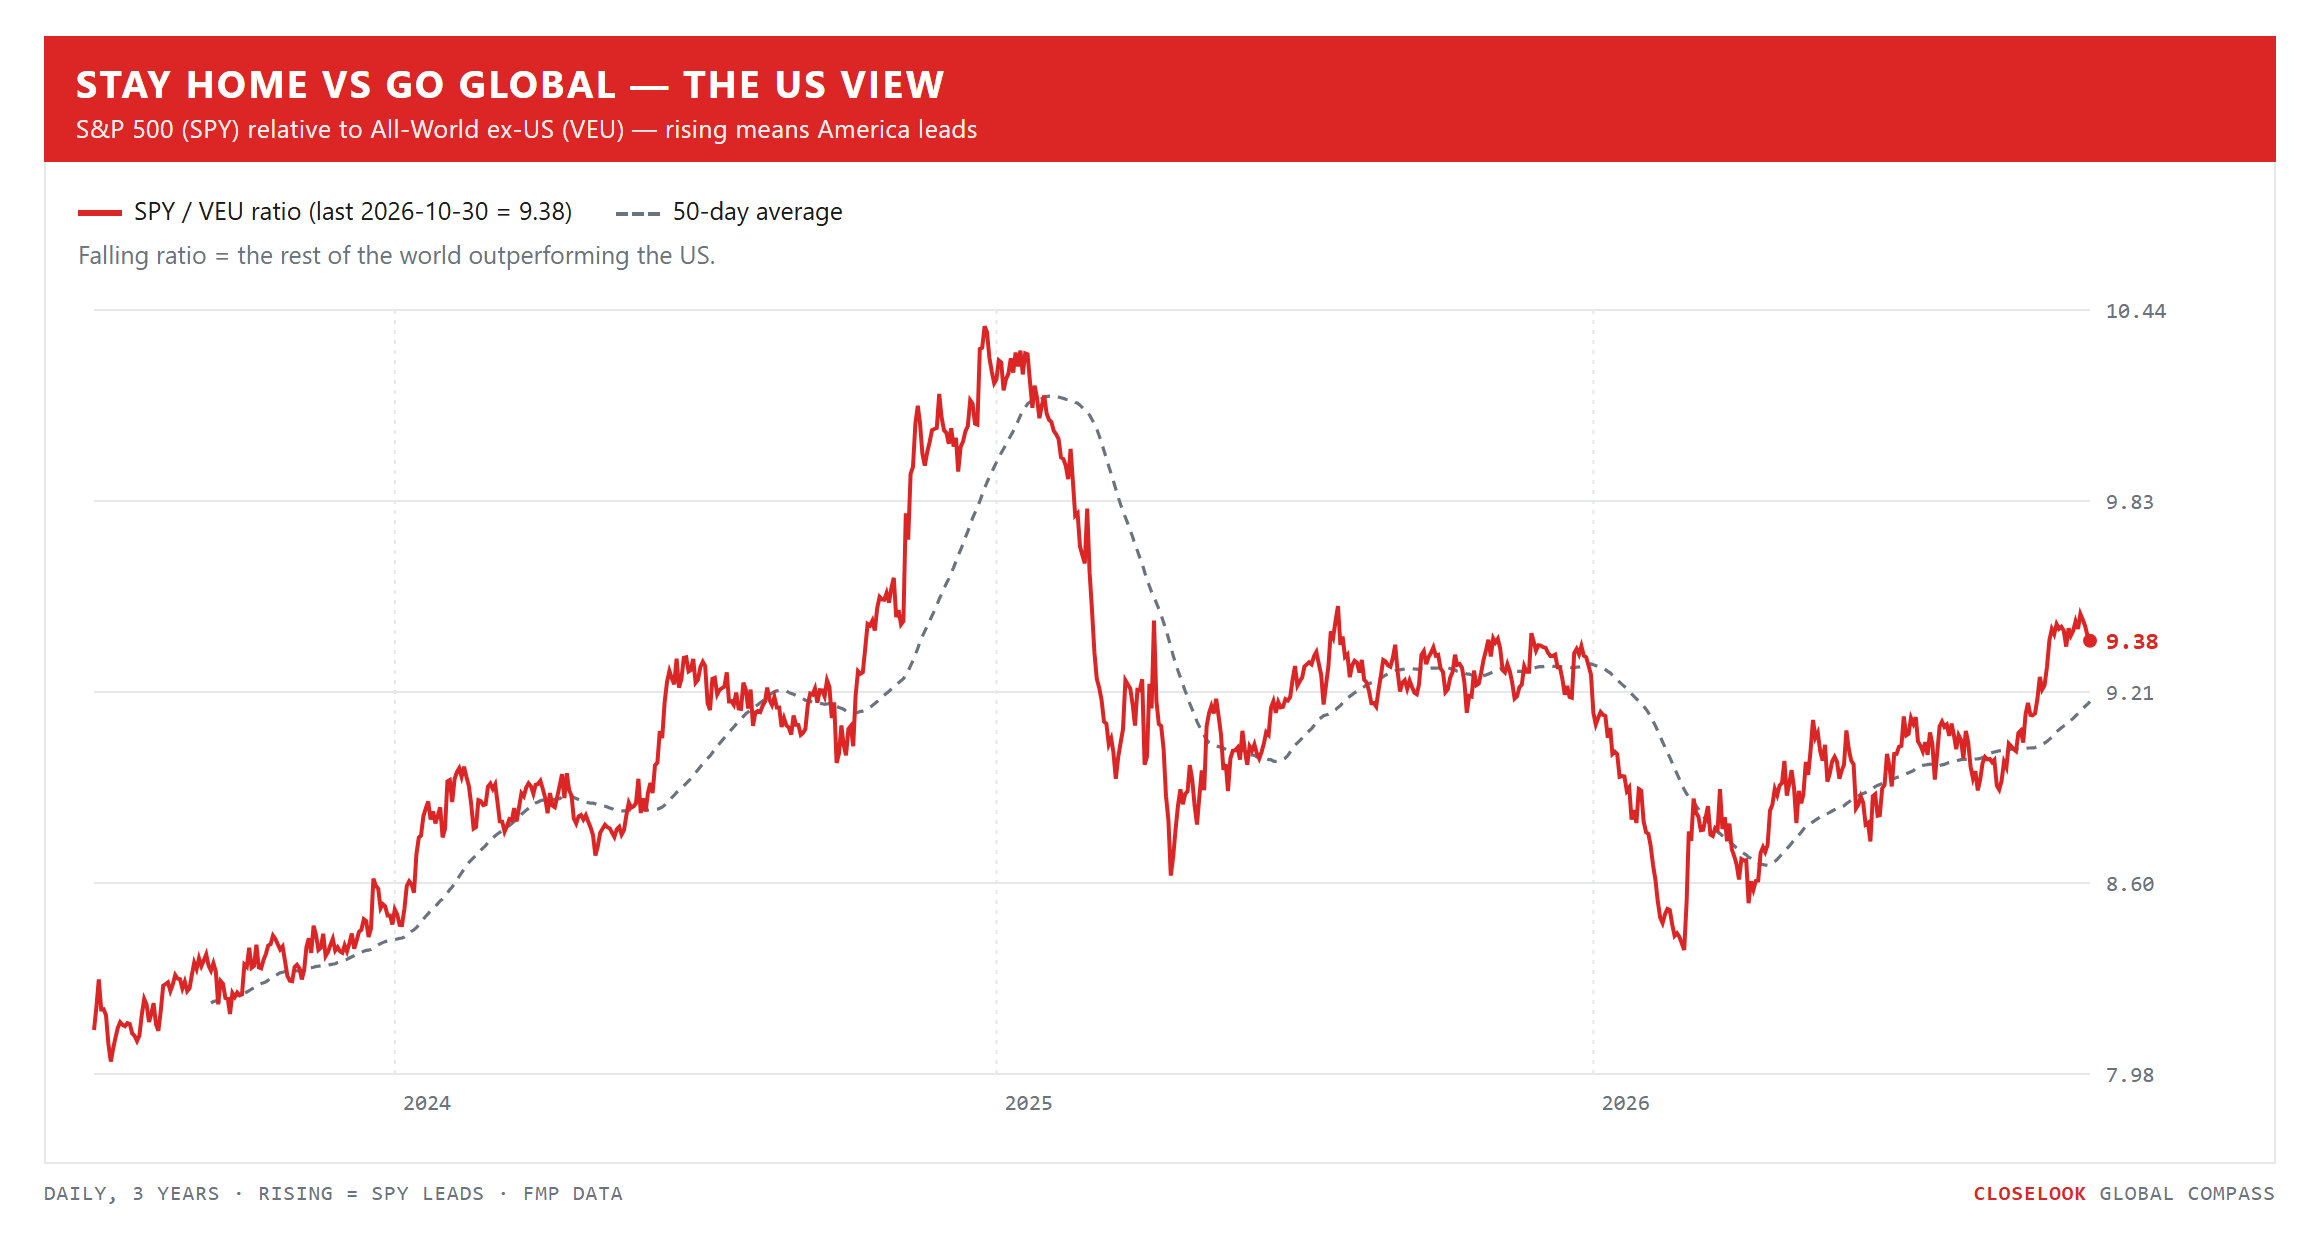
Stay home vs go global — the US view. This week the world beat America, by a little: VEU −0.16%, VT −0.37%, SPY −0.56%. On the year: +10.8% for America against +10.1% for the world and +9.5% for the world ex-US.
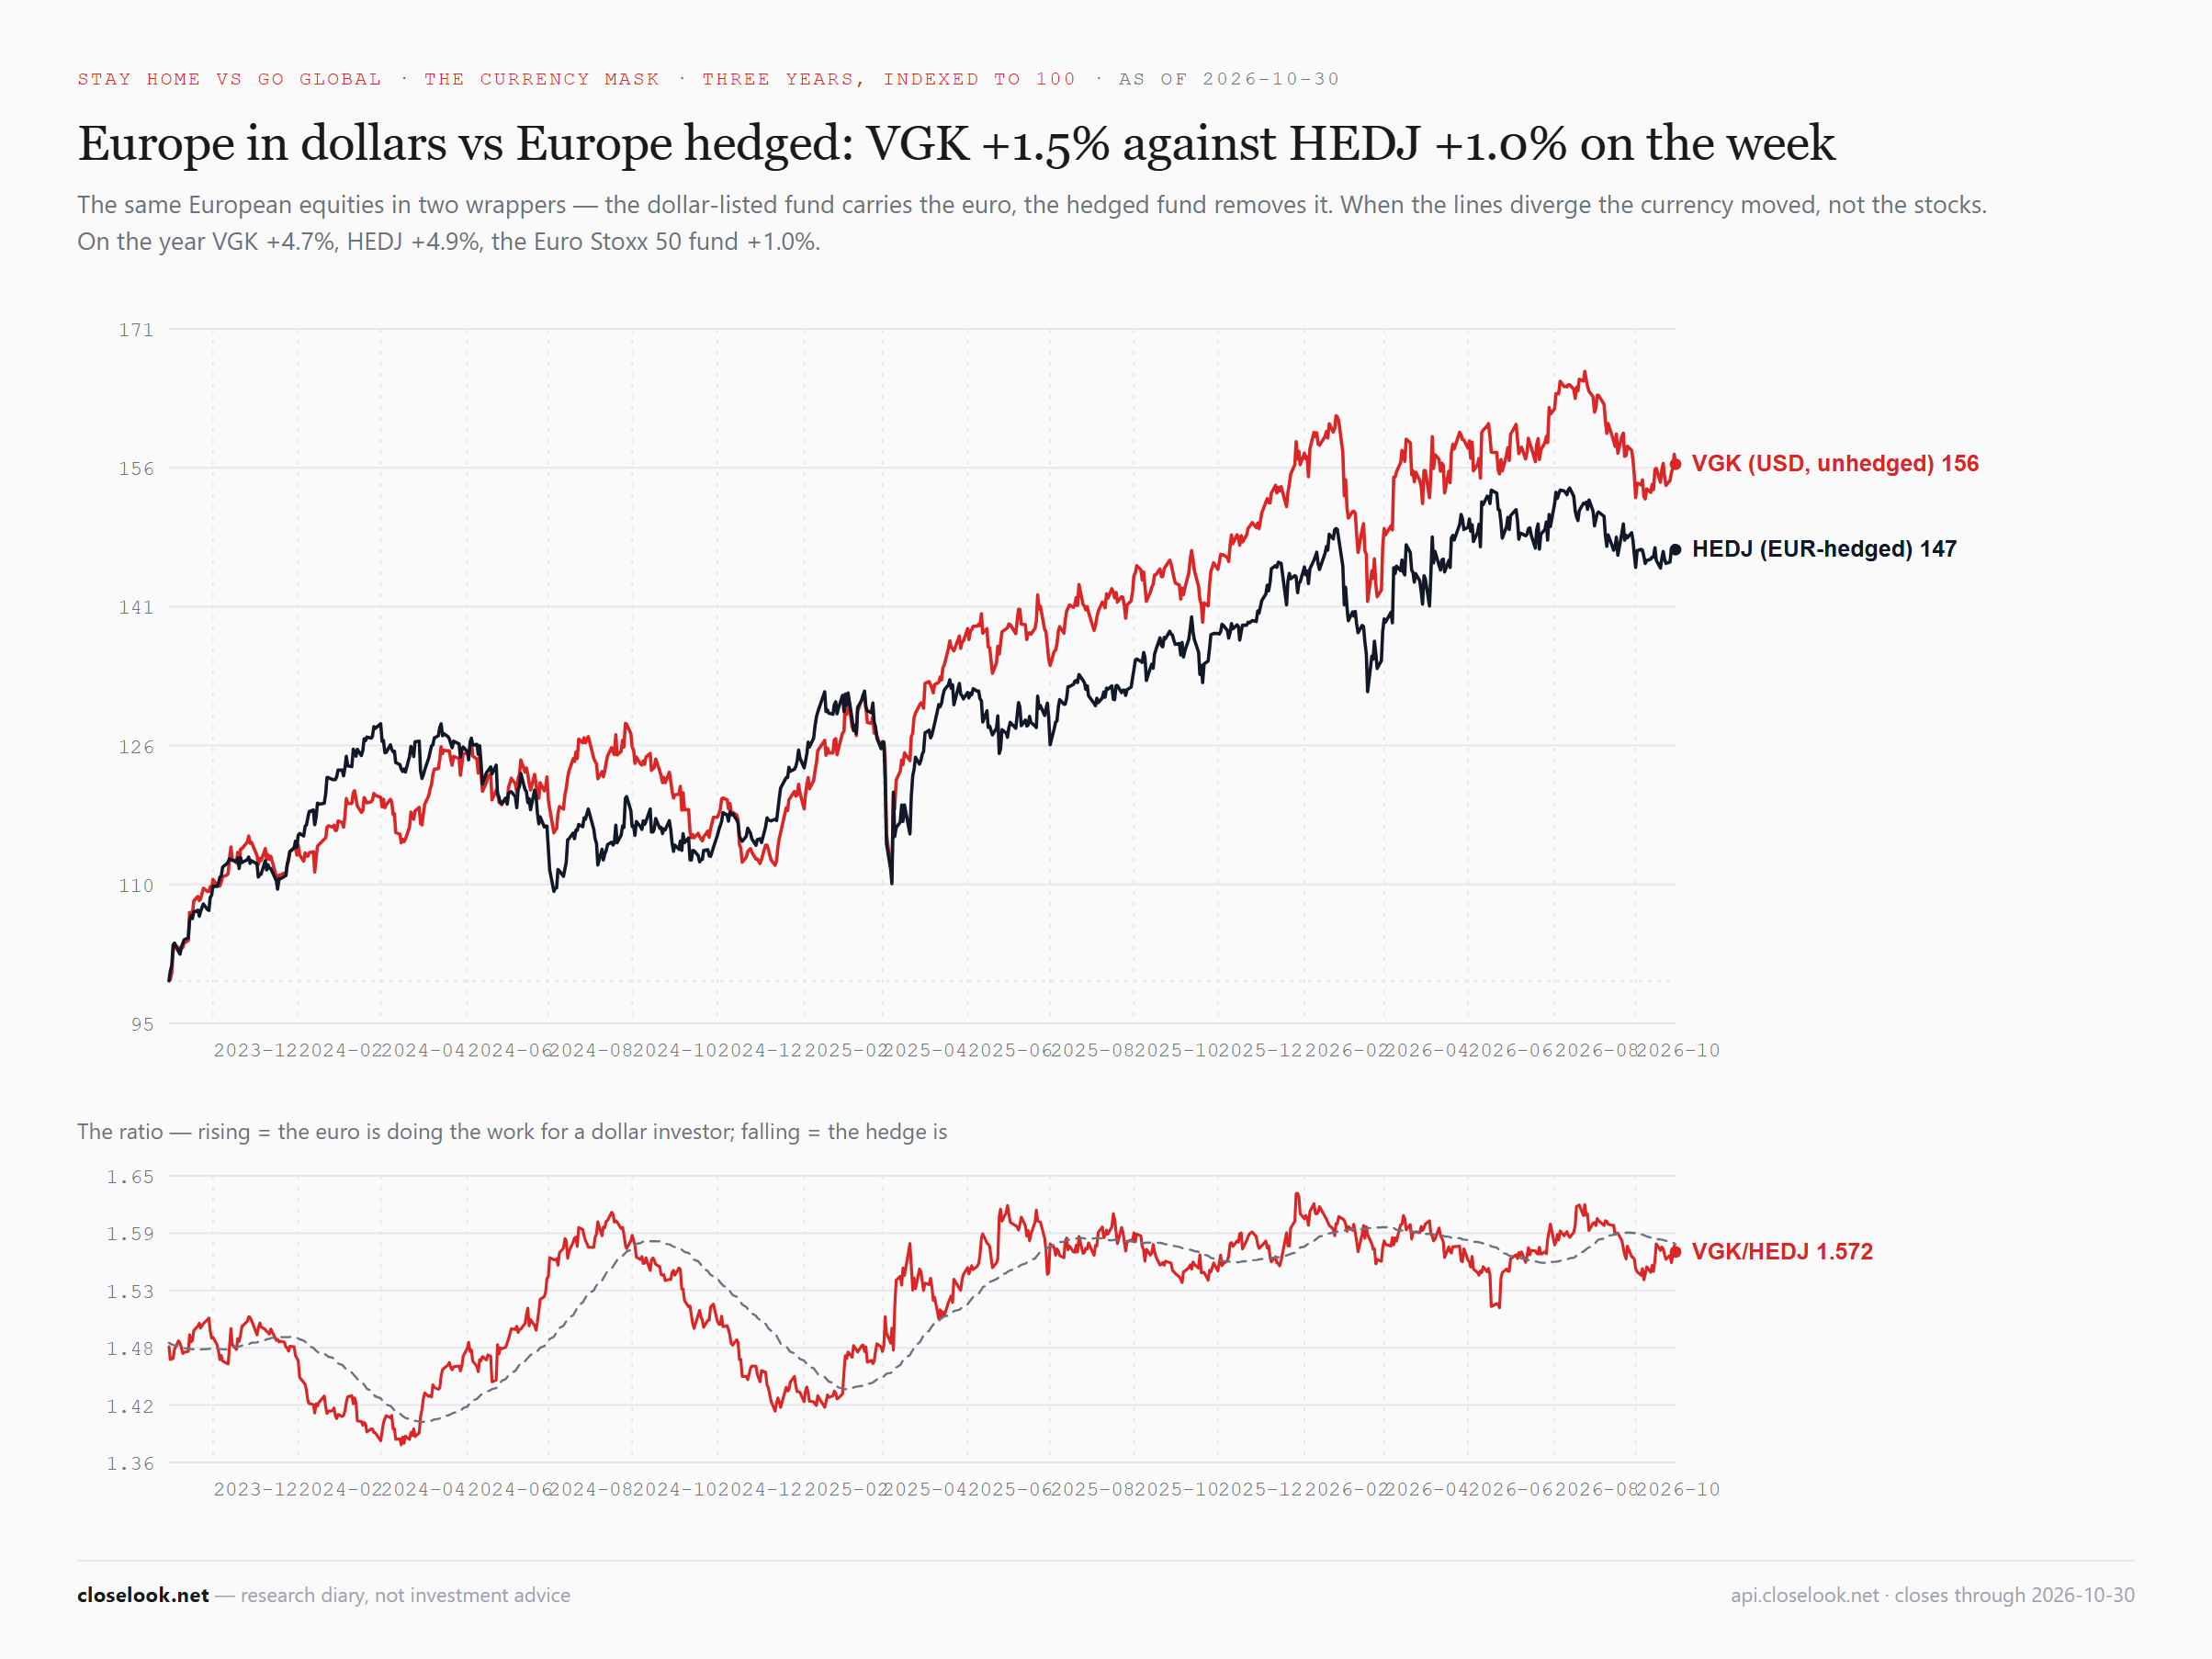
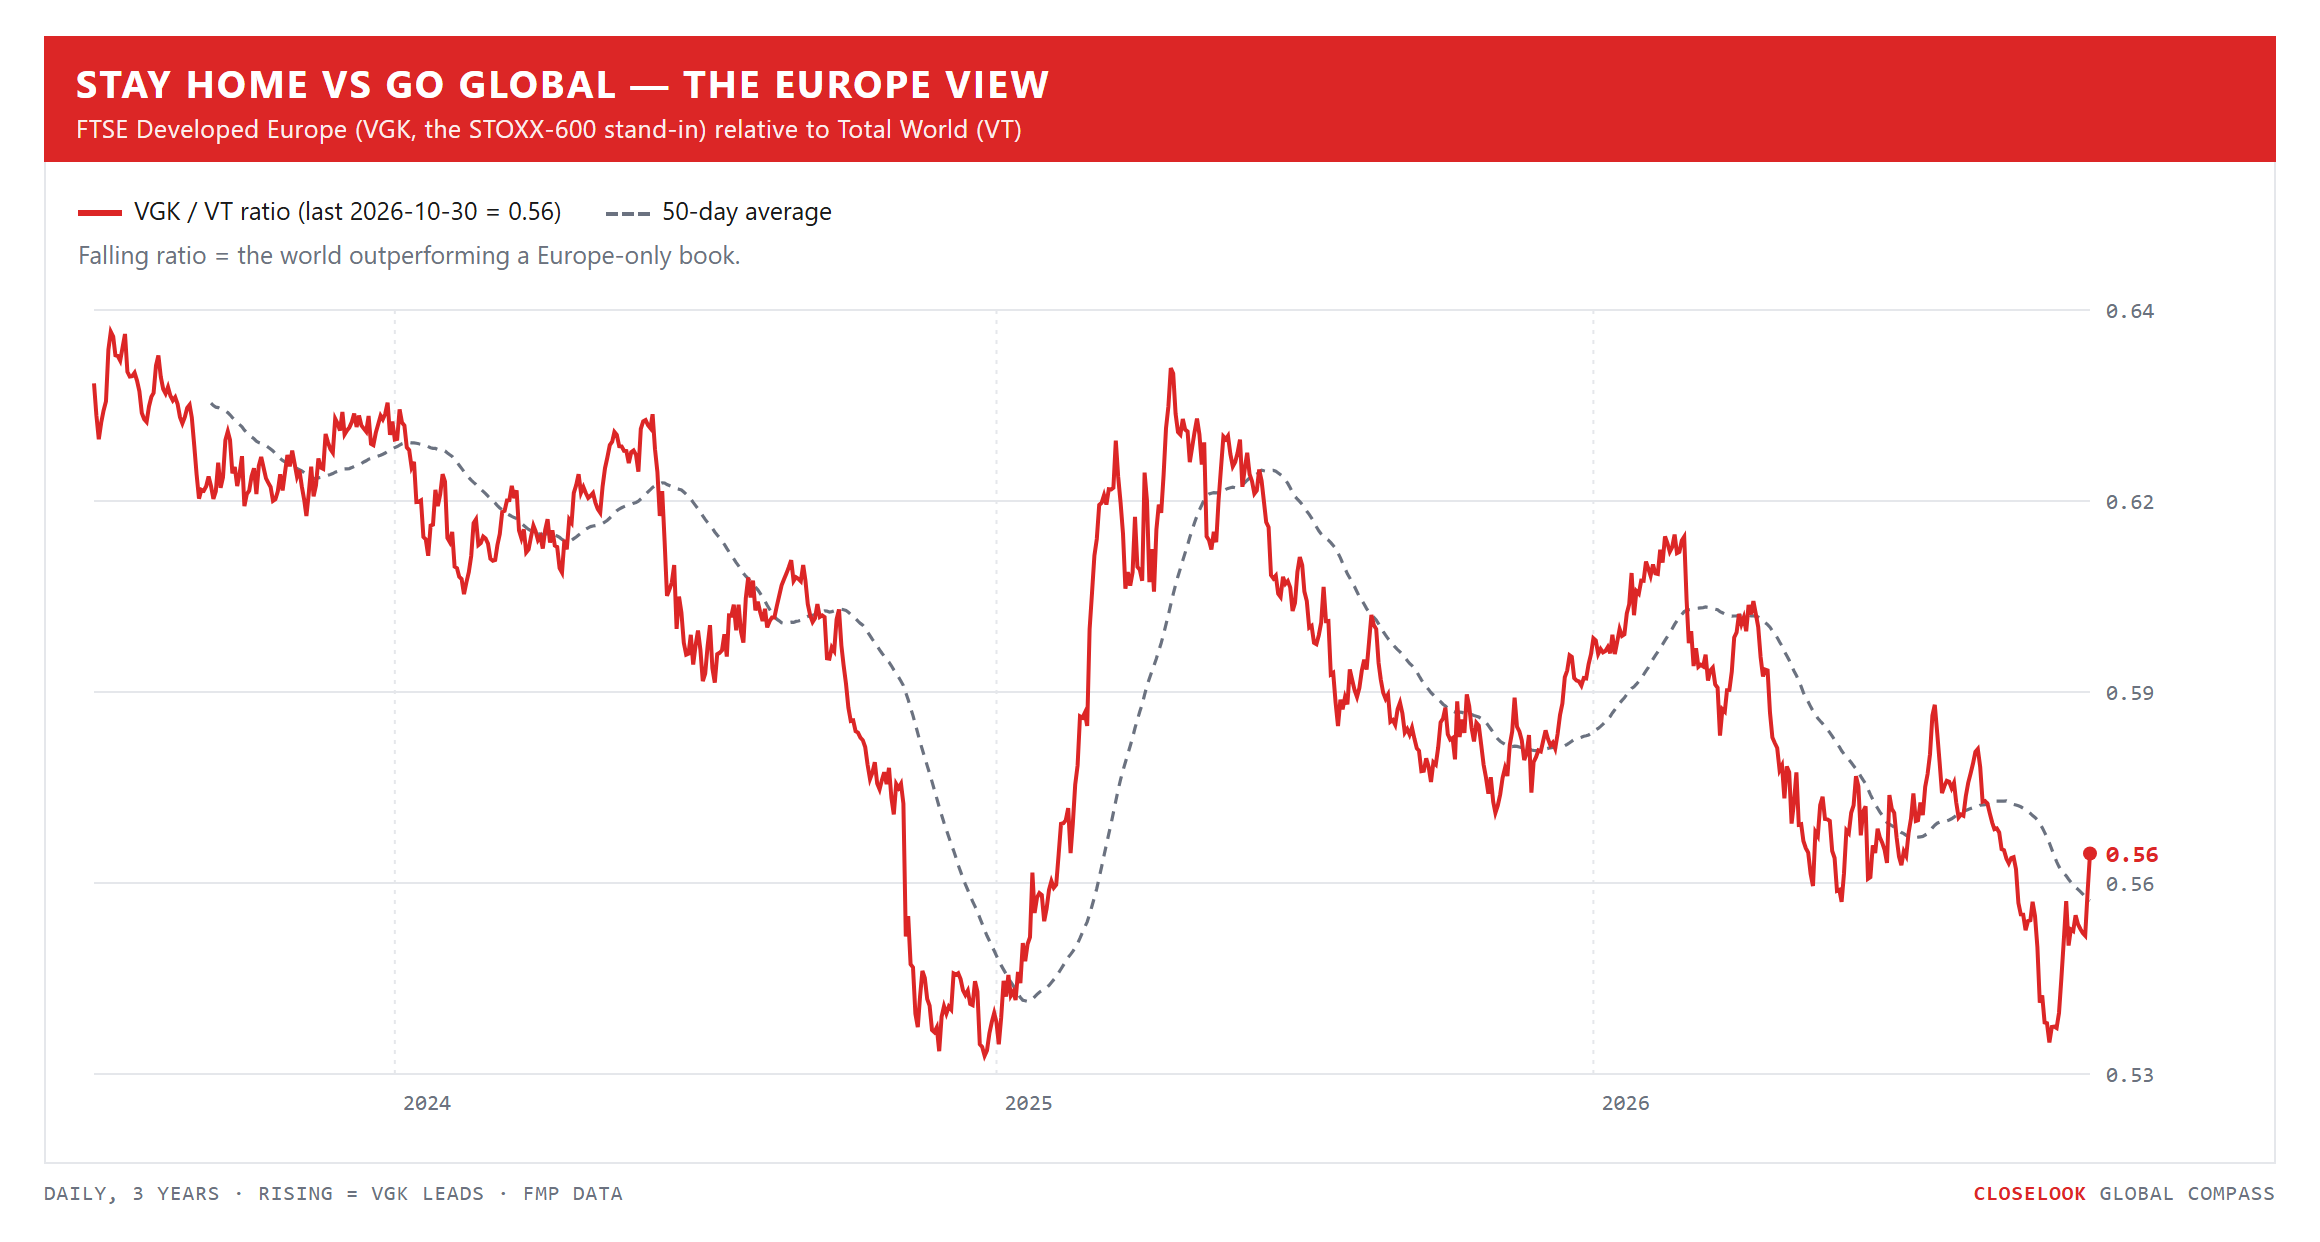
Stay home vs go global — the Europe view: everyone up but Spain. In local terms: the STOXX 600 +1.73% to 646.75, the DAX +2.53% to 25,818, the CAC +2.52% to 7,979, the Euro Stoxx 50 +1.04% to 6,131 — and outside the euro the FTSE 100 +0.37% to 10,730 and Switzerland's SMI +2.35% to 14,802, a record close. Spain's IBEX fell 1.77%. The dollar-listed Europe fund rose 1.50%, the euro-hedged one 1.03%; the euro slipped 0.3% to 1.1169. The French fund rose 2.10% to 42.24, 2.4% above the low of the year it made on 12 October.
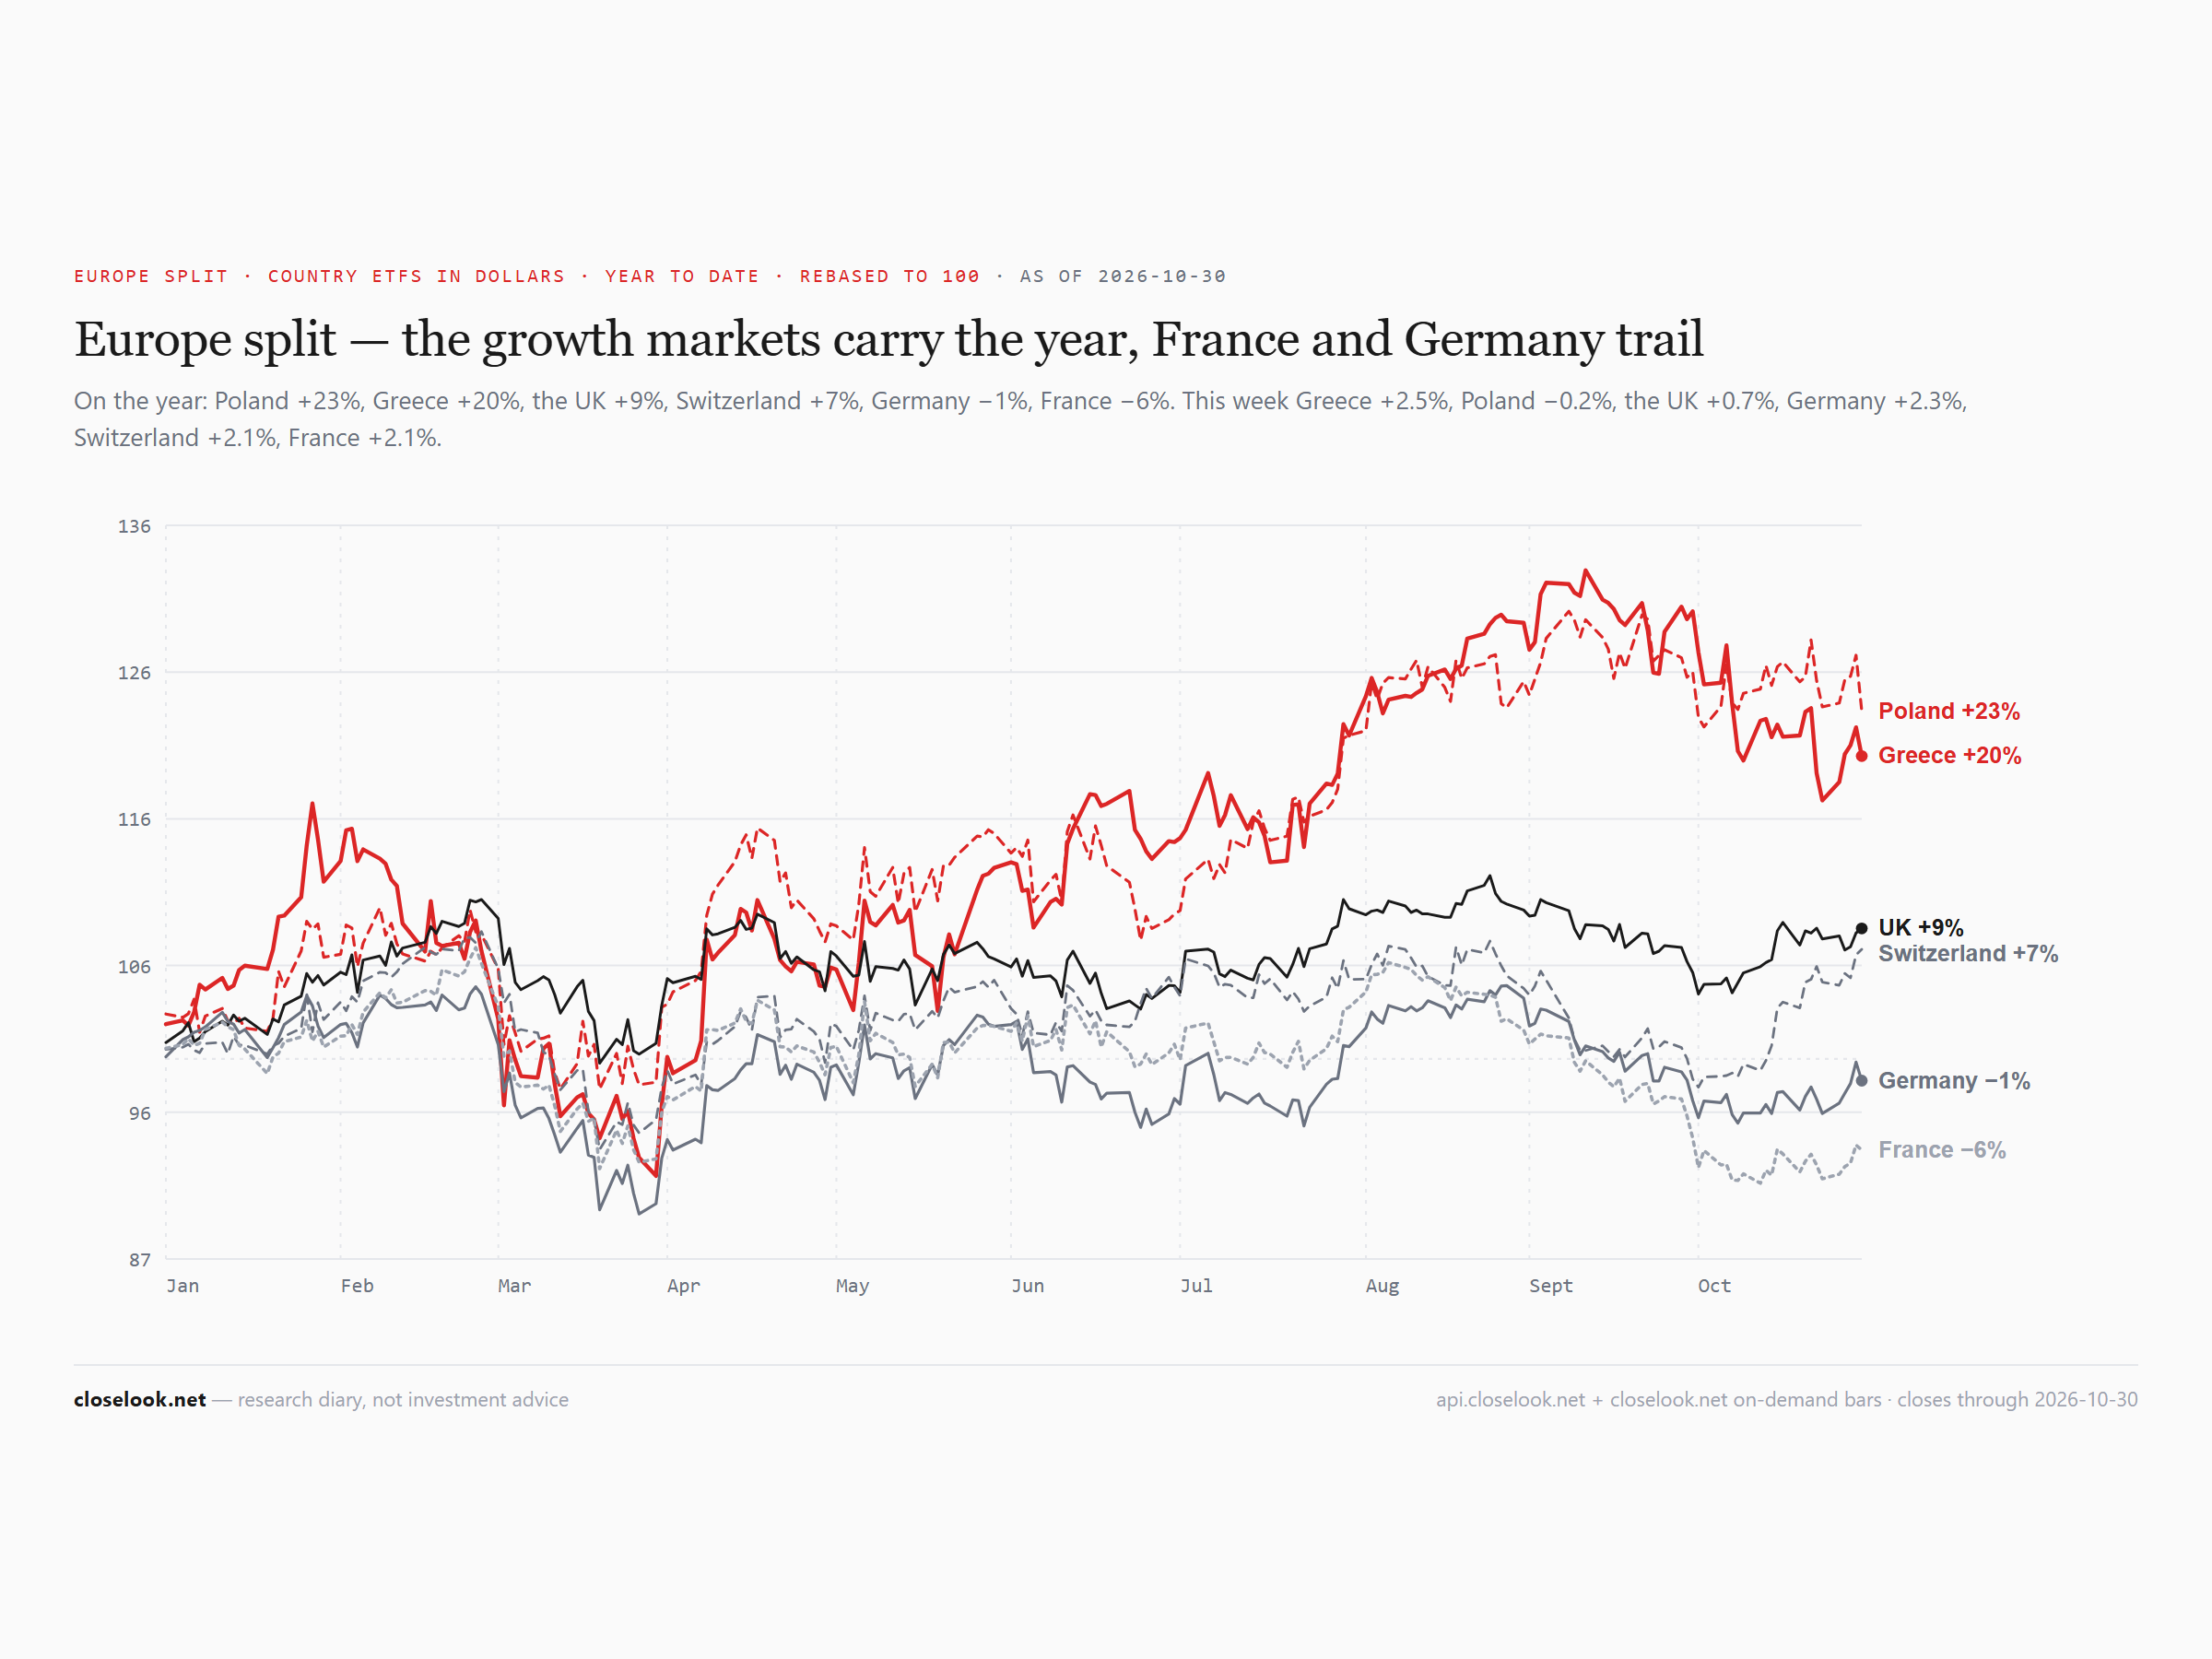
Europe split — the core came back, the periphery paused. Germany +2.3%, France +2.1%, Switzerland +2.1%, Austria +2.1% and Norway +2.2%, against Spain −2.0% and Poland −0.2%. The Netherlands, Europe's chip-equipment market, rose 0.9% despite Friday. Last week Germany and France fell with the core. This week they led the bounce — and both are still below where they started 2026.
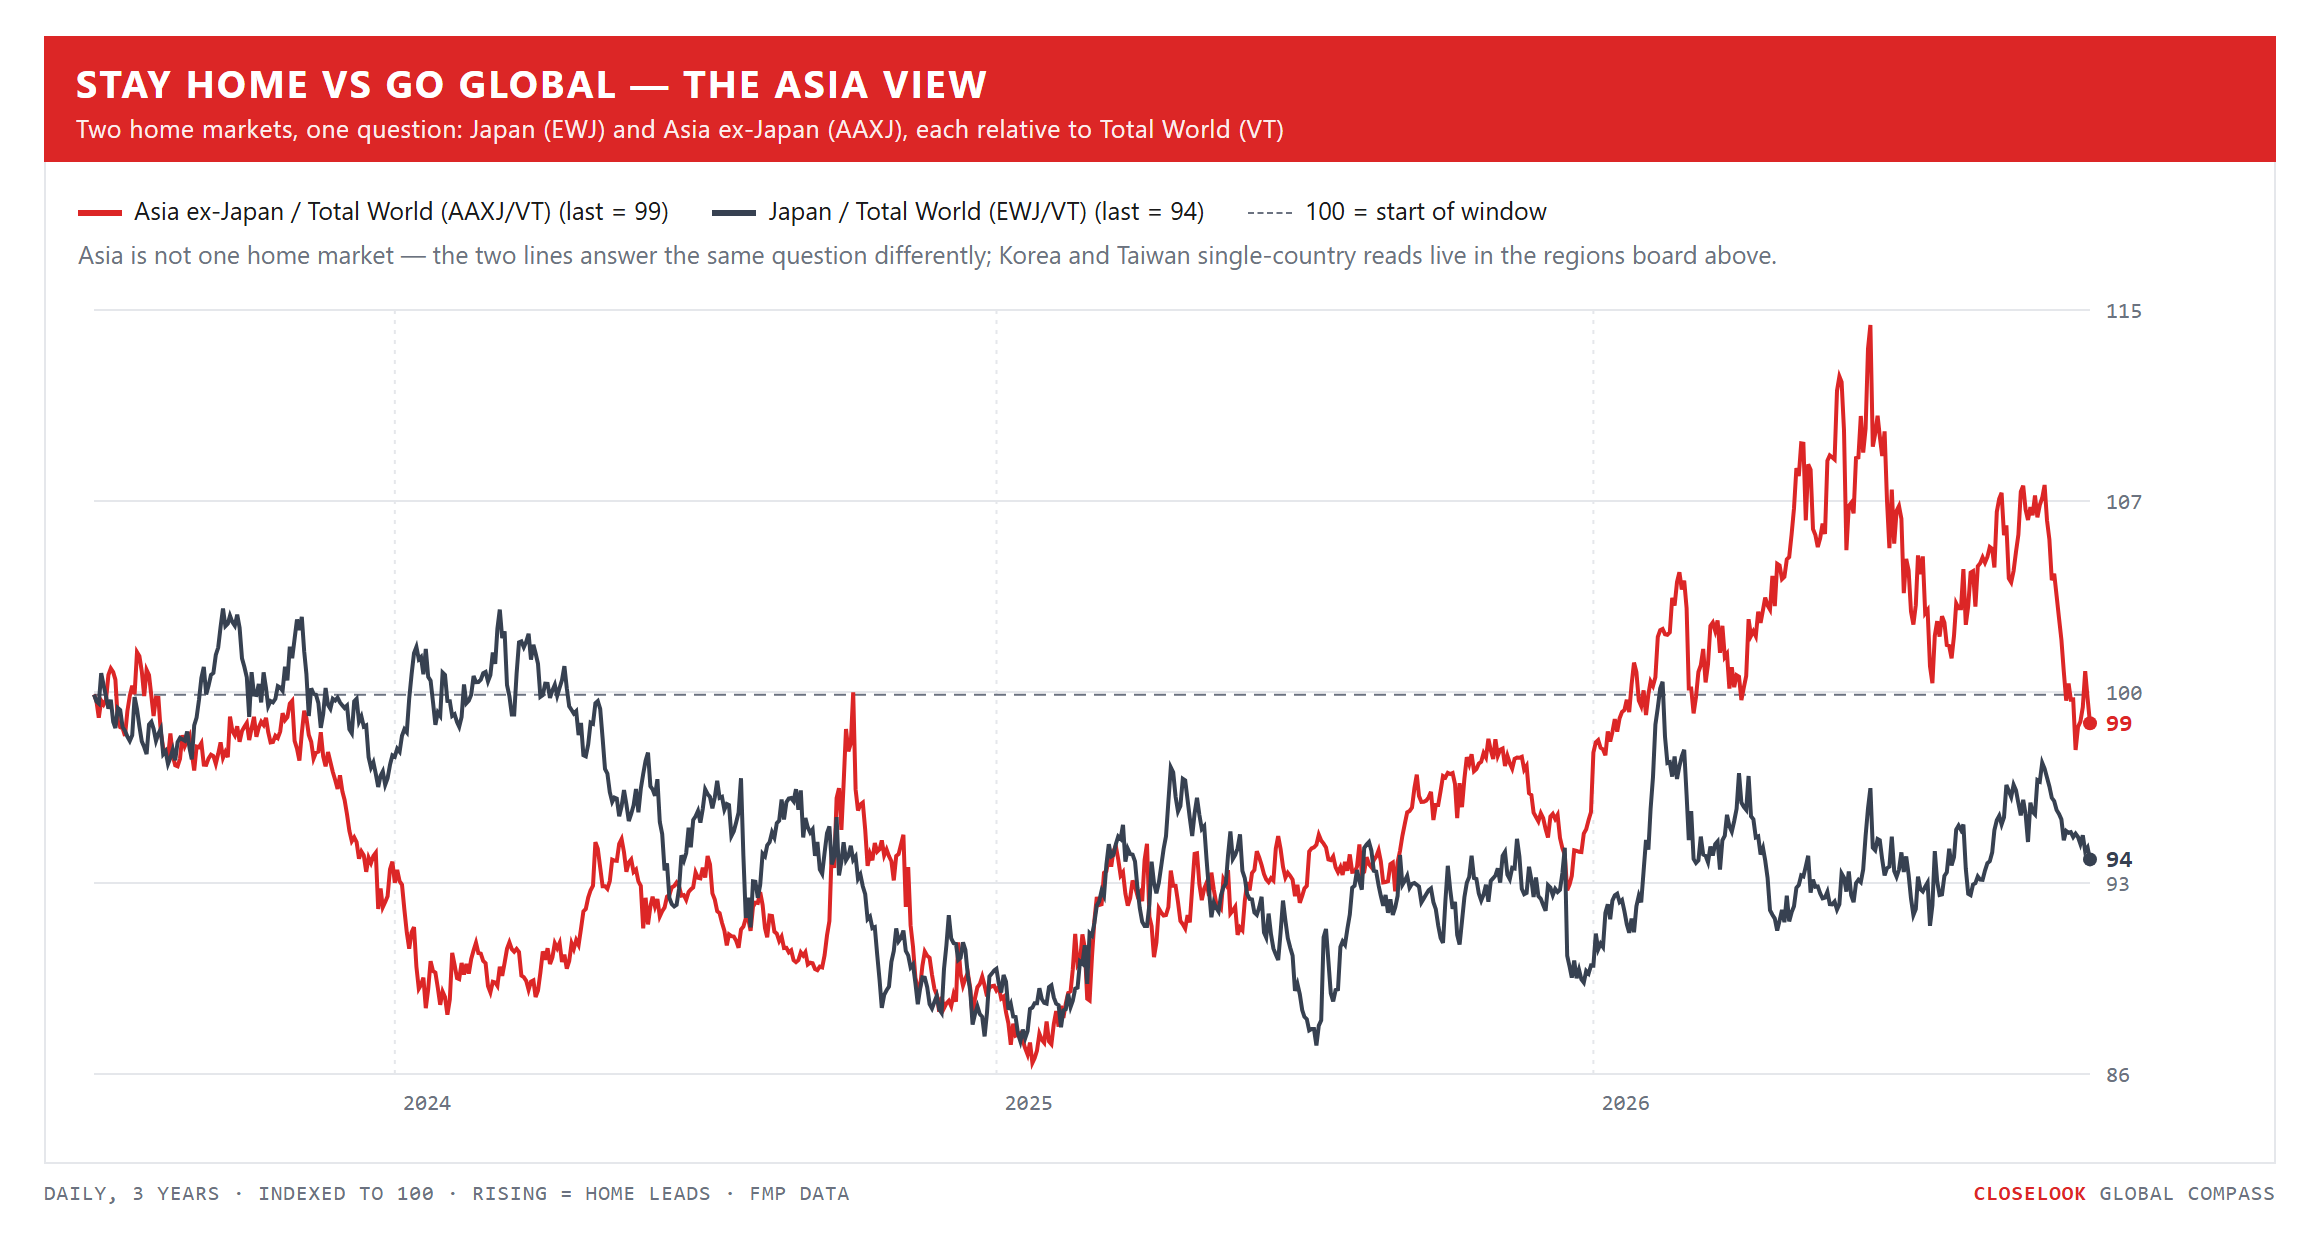
Stay home vs go global — the Asia view: the week split on Friday. Korea: EWY +1.08%, the Kospi +3.3%, the Kosdaq −3.6%. Taiwan: EWT −3.61%, the Taiex −1.8%. Japan: the Nikkei +1.0%, the TOPIX flat, the dollar fund −1.26% — the yen weakened from 156.74 to 157.52 per dollar. China and Hong Kong +1 to +4%, the A-shares −2.3%. India: the dollar fund +2.71%. Australia +1.44%. The markets that own the AI hardware rose into Wednesday and fell on Friday. The markets that own almost none rose all week.
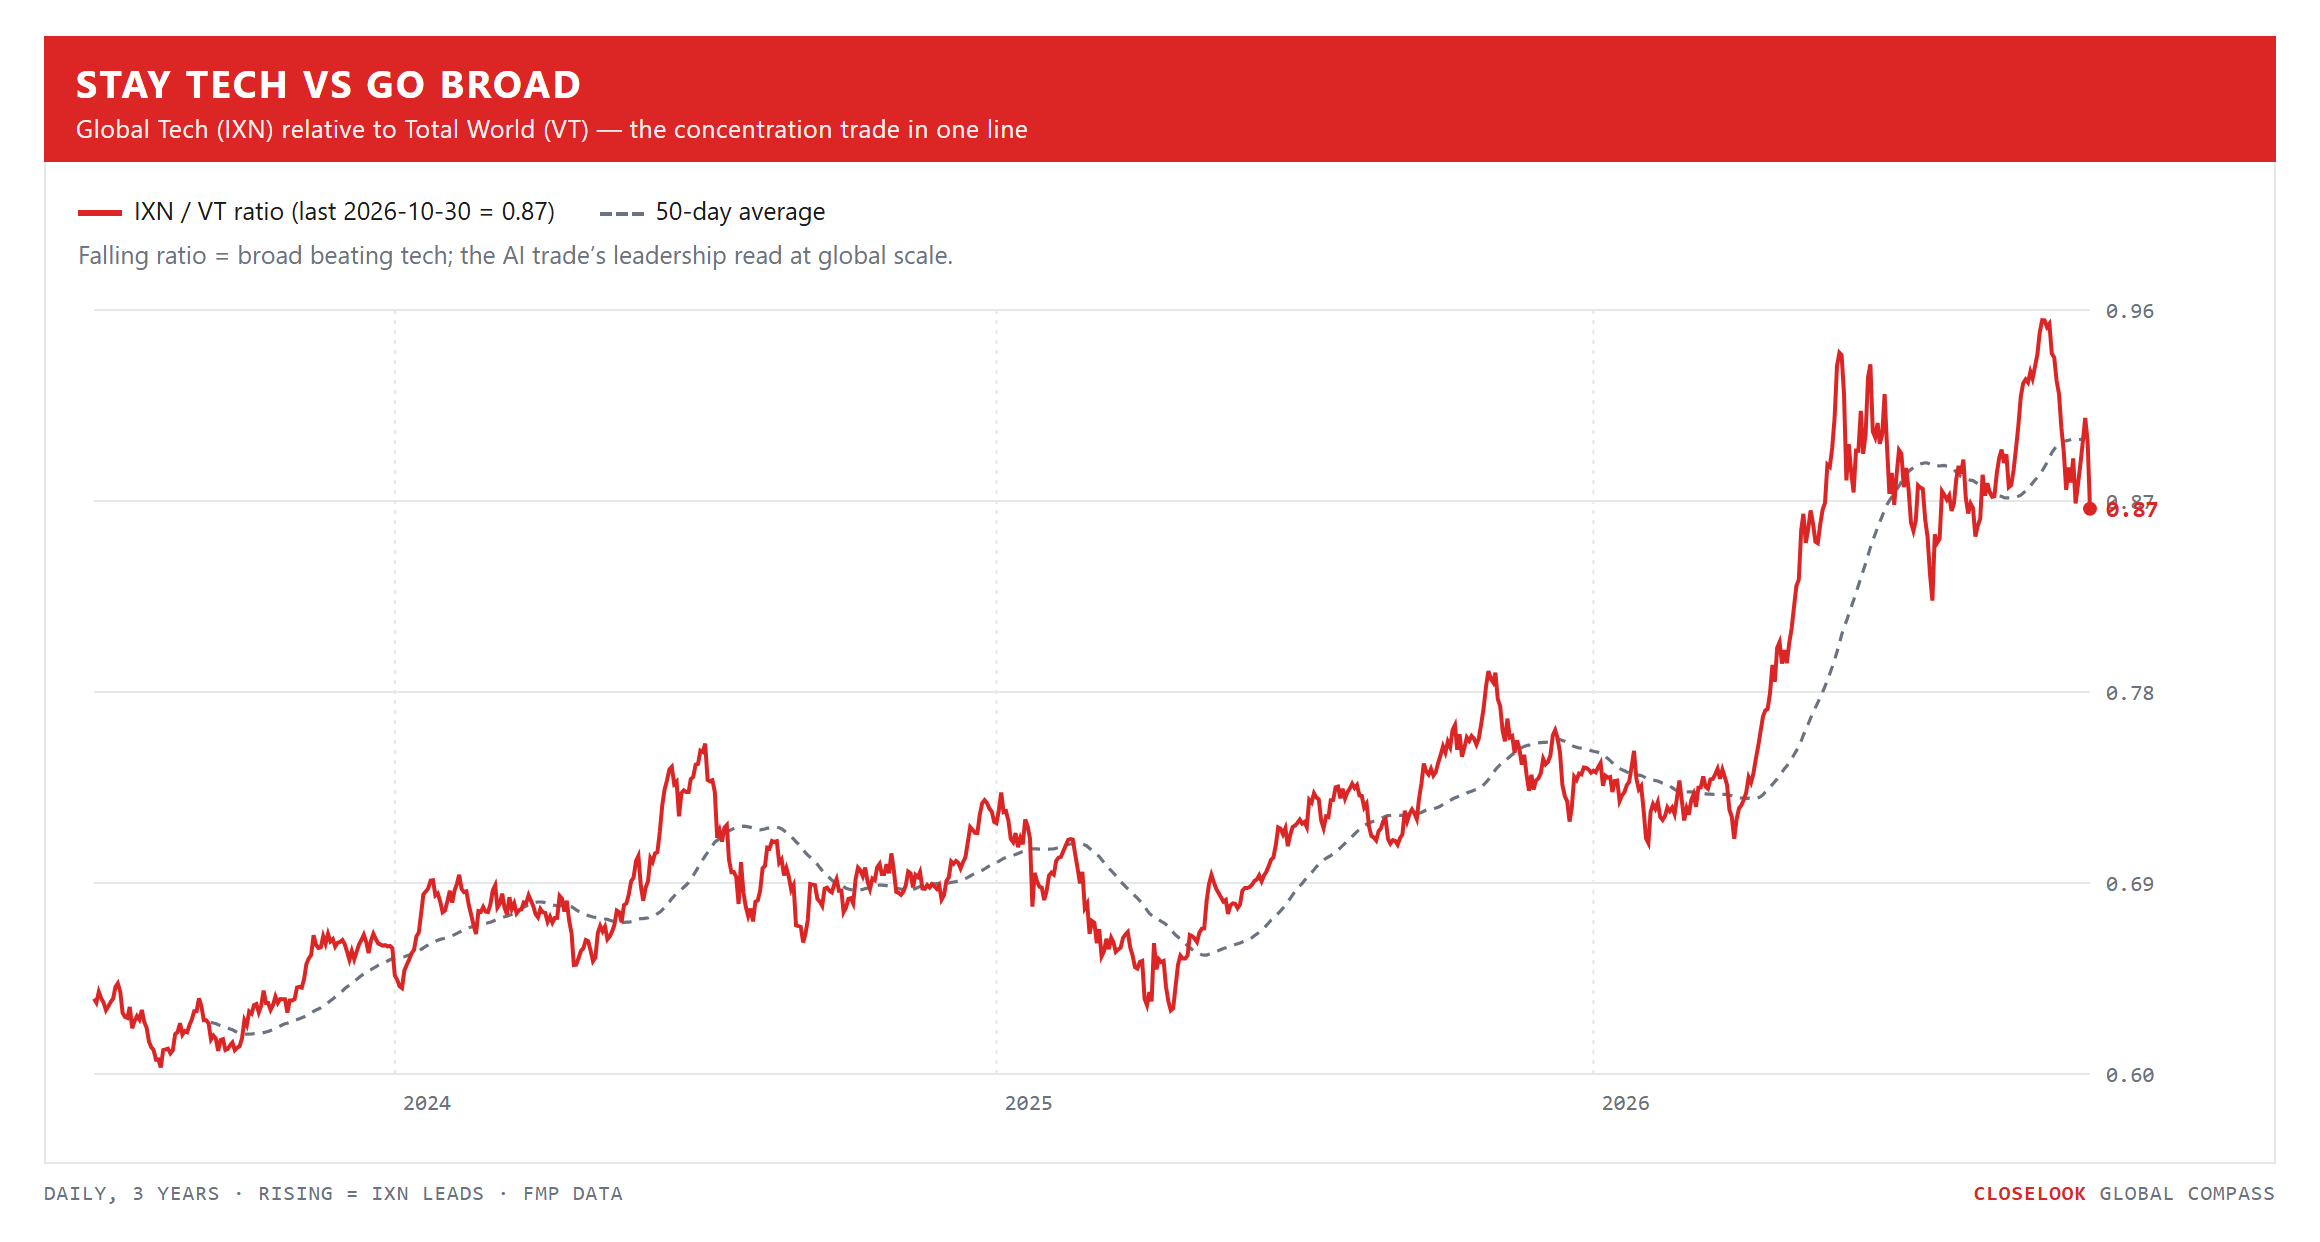
Stay tech vs go broad — broad won, everywhere. The equal-weight S&P +0.82% against the S&P's −0.56% and the Nasdaq 100's −1.97%; the world −0.37% against global tech's −1.66%. Small caps rose 1.30%. On the year tech still leads by far: global tech +28.3% against the world's +10.1%.
Momentum vs defensive — min-vol at a record, again. International min-vol rose 0.29% to 96.25, a record close; global min-vol rose 0.35% to 129.42. International momentum rose 0.55% to 50.96. On the year min-vol leads, +11.6% against +6.2%. Value and growth were level on the week, +0.53% against +0.68%; on the year value leads +11.0% against +4.1%.
The Closelook letters — where this one sits. The house thesis, compressed: the stock market is a growing system at the aggregate level in which most constituents slowly fade while a small group massively outperforms — and that group changes; it never stays static. Own the aggregate, know the current winner group, watch for the rotation. Last week a new candidate for the winner group stepped forward — the software that runs on the chips. This week it was sold with everything else, and the market's money went to the places it goes when it wants to wait: health care, staples, Switzerland, the bonds. This letter reads the map; Sunday's US letter reads the tape and the AI indices' patterns; Sunday evening's Hypergrowth letter reads the names.
2 · The State
The mechanism, named: raising cash, one region at a time. Put the week in order. Monday: Brazil's runoff result reached the market; EWZ fell 19.8%, while the chip index rose 2.8% and the Nasdaq 100 1.1% — the rest of the world ignored Brazil. Tuesday: the five big-tech reports of the week before had all beaten and none had been rewarded; the market paid three smaller suppliers for theirs instead — Celestica, Cadence and Amkor rose 6 to 13% in the day. Wednesday: SK hynix reported a record quarter; the Kospi rose 6.6% through 6,000. The Fed held its range at 3.75–4.00% in a 10–2 vote, two officials preferring a hike. After the close Microsoft, Alphabet and ServiceNow reported. Thursday: Alphabet fell about 13% and ServiceNow about 27% in the day's trade, Microsoft's after-hours gain disappeared, and Eli Lilly rose 6.6%. Friday: Intel fell 30% on its outlook, the chip index 7.2%, the Nasdaq 100 fund 3.5% — and gold 3.5%, the bitcoin fund 5.1%, silver 5.7% with them.
The pattern under the dates. The selling did not arrive everywhere at once. It came to one place at a time, and each time it found a reason: an election in Brazil, a set of mega-cap reports in America, an outlook in the chips. What did not sell all week: the bonds, health care, staples, Switzerland, India, energy. That list is what a market buys when it wants to wait, not when it wants to run.
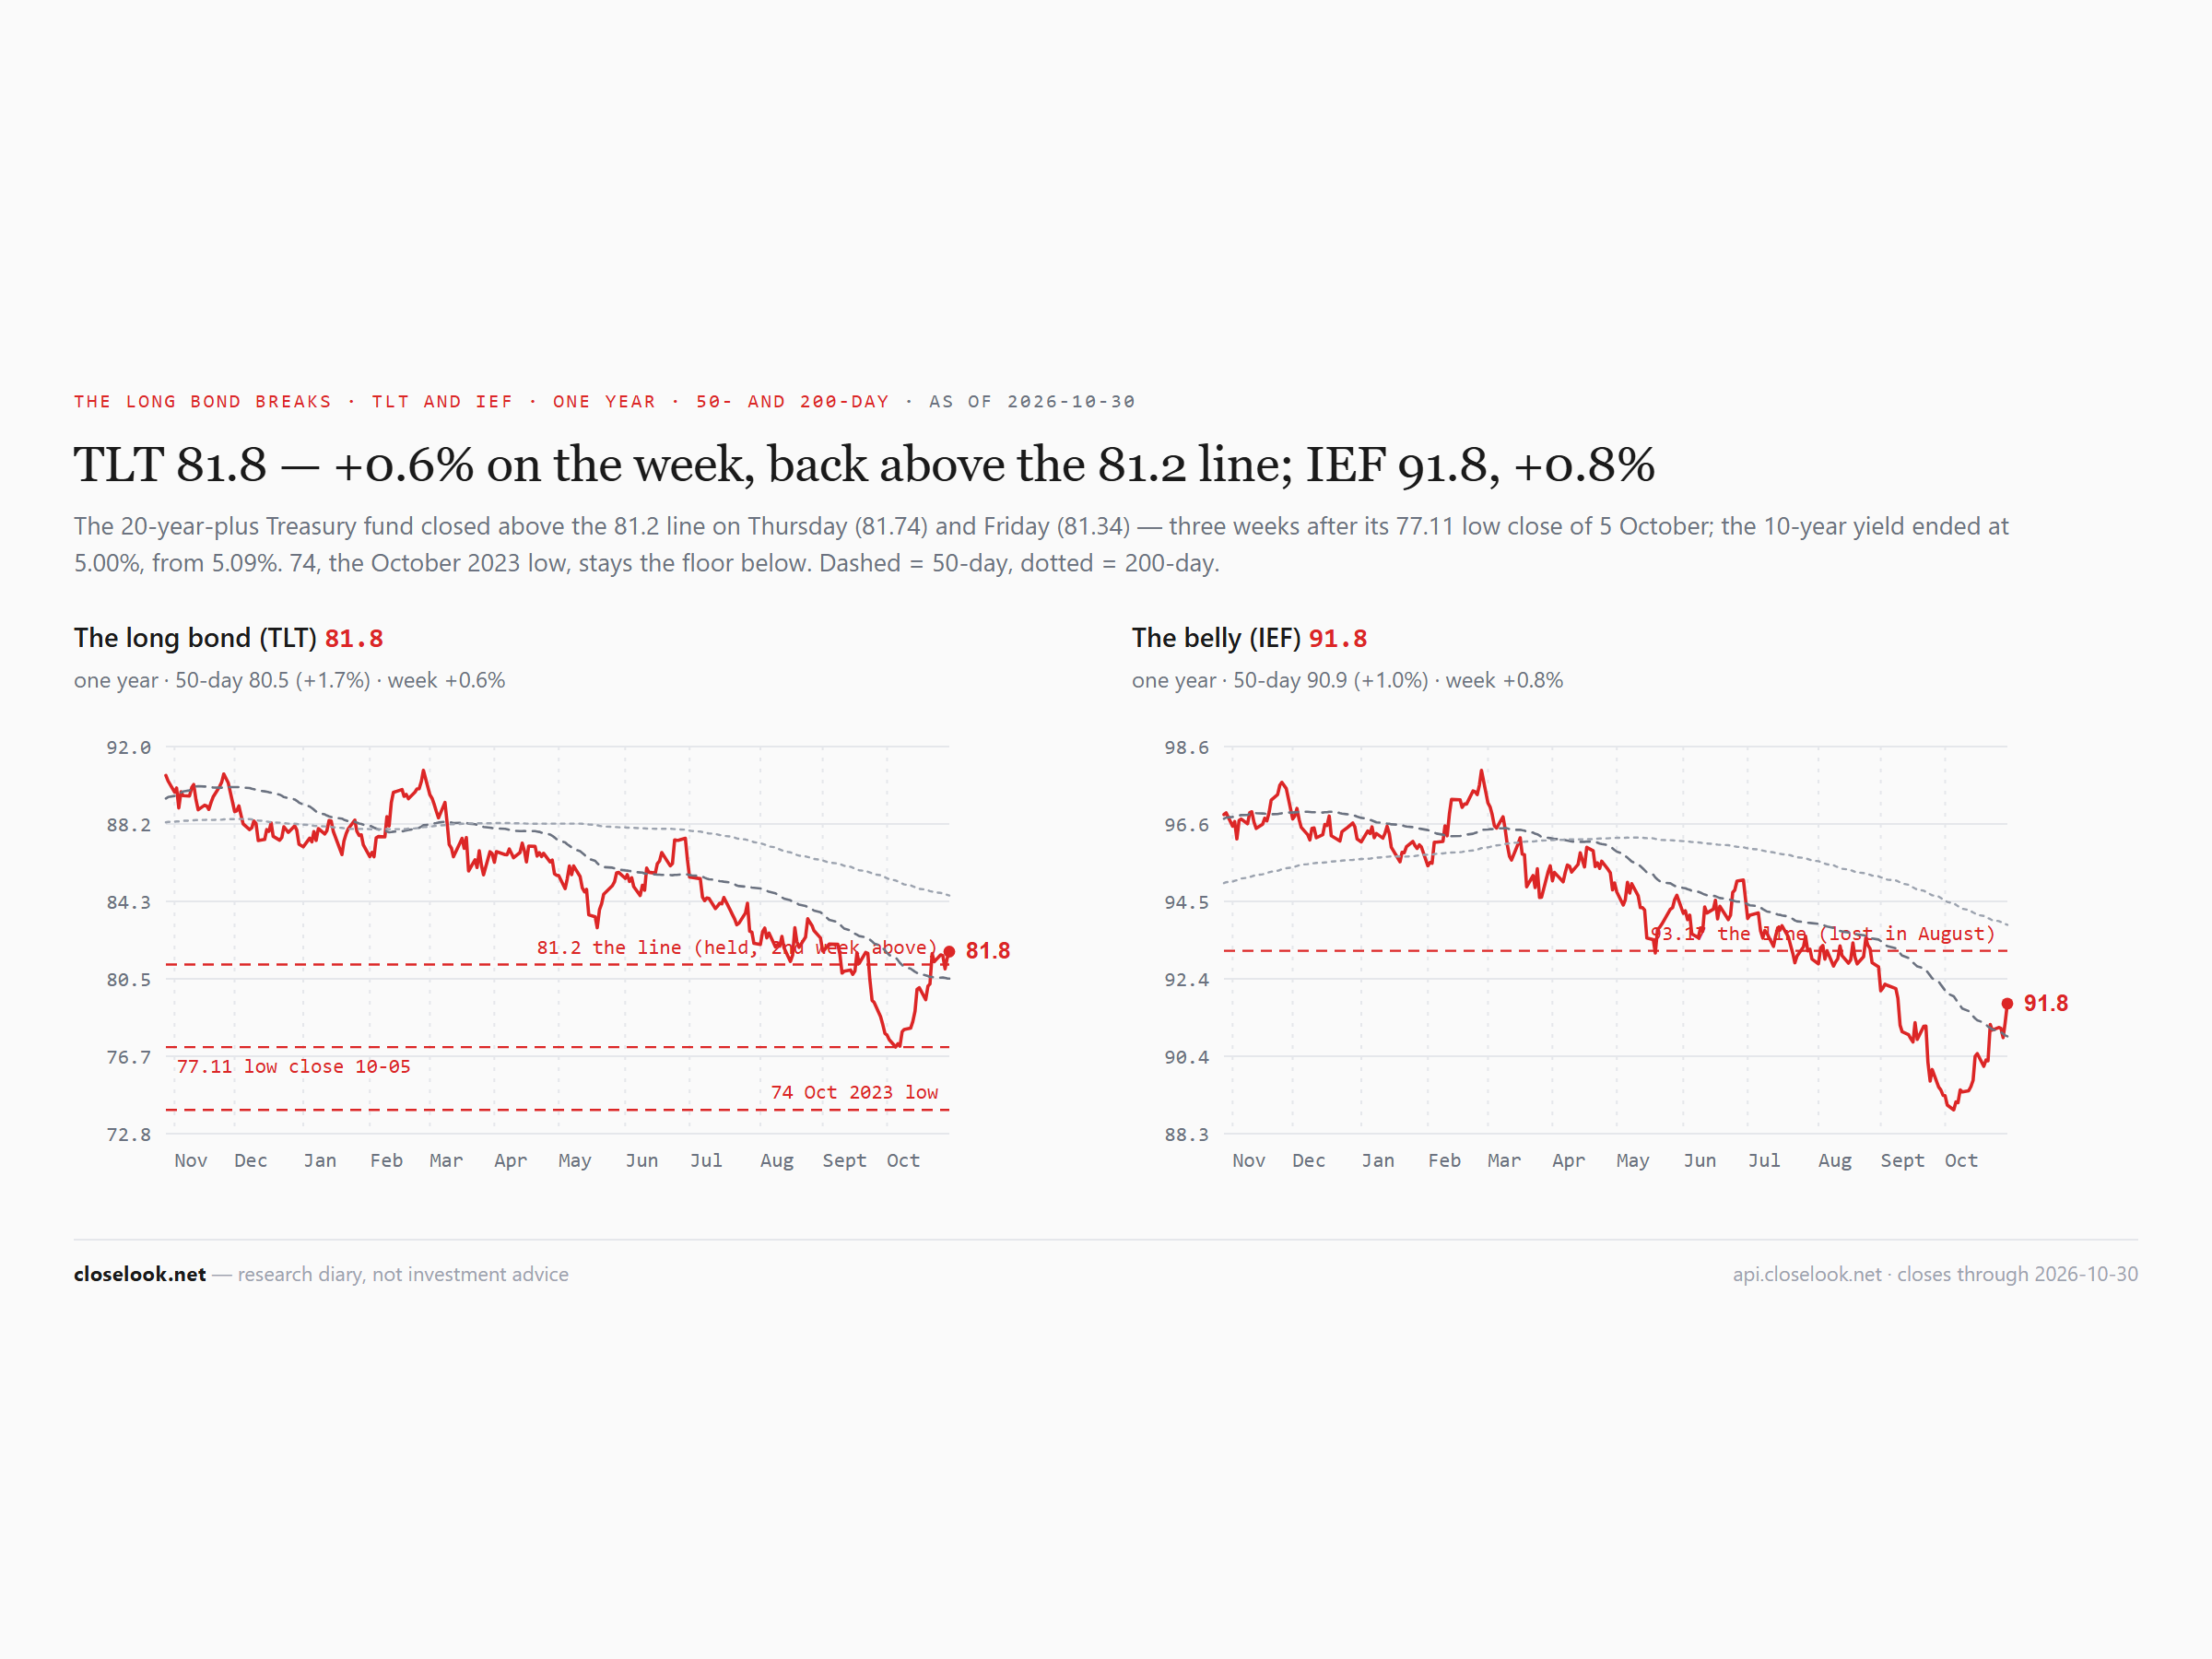
The rate peak, confirmed. The US ten-year closed the week at 4.93% on the house sovereign board, from 5.00% a week ago and 5.31% at the close on 5 October — 36 basis points lower in 21 days. Last week this letter wrote that a weekly close under 5.0% would confirm the rate peak. That is the close. The long bond rose 0.61% to 81.84, a second week above the 81.2 line; IEF 91.76, +0.78%.
The odd part: yields fell while the Fed's next move is priced as a hike. The Fed held in a 10–2 vote, with Governor Cook and Cleveland Fed President Hammack preferring a quarter-point increase. Its statement said the economy is "expanding at a strong pace" and inflation "remains elevated", and gave no rate path. After Thursday's third-quarter growth figure of 3.4% and September's 3.6% inflation reading, CME FedWatch put the odds of a December hike near 80%. Bond buyers are pricing one more hike and a slower economy after it — the second half of that sentence is what pulls the ten-year down.
France still pays more than America — by less. The French ten-year closed Friday at 4.97%, still above the US ten-year's 4.93%. On the house spread series France now pays 161 basis points over Germany, from 167 a week ago; it was 68 at the end of June. Italy pays 113, Greece 93. The German ten-year closed at 3.34%.
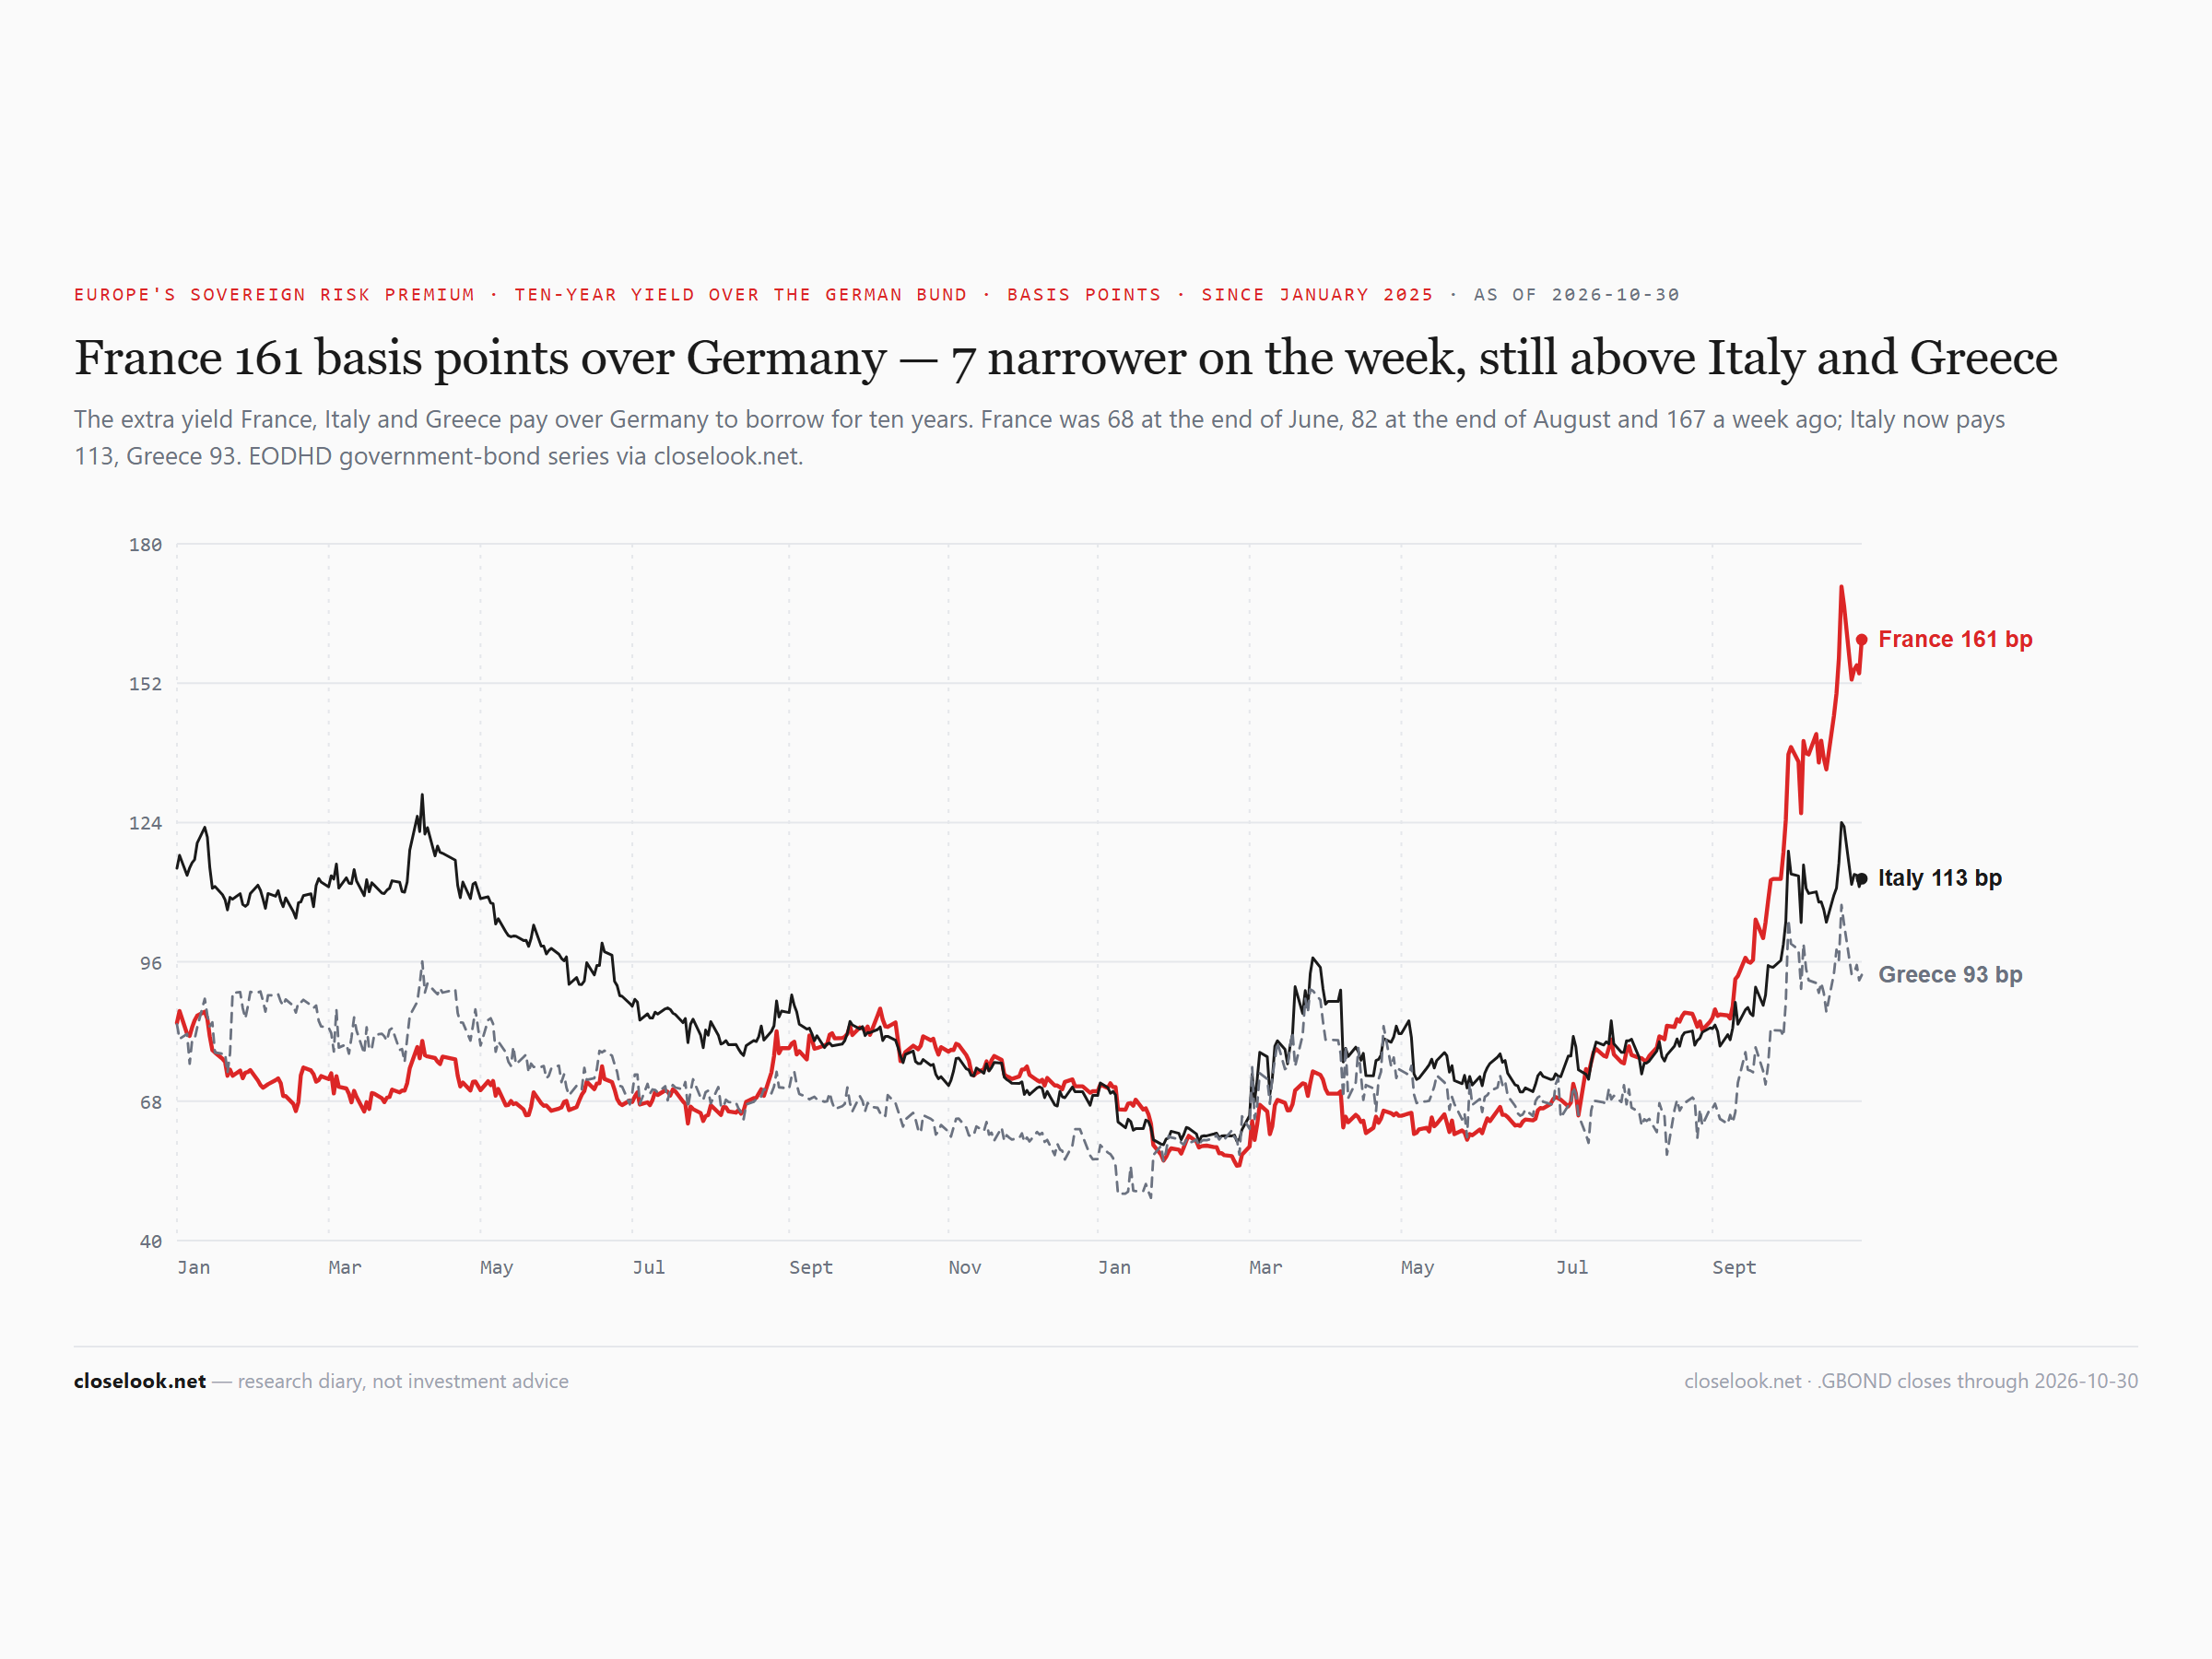
The rate map — one sentence each. America: 4.93% on the ten-year, down 7 basis points on the week. Britain: 5.29%, 5.72% on the thirty-year — still the highest long yield on the board. Japan: 2.77%, from 2.80%. Germany: 3.34%. France: 4.97%. Italy: 4.49%. Canada: 3.80%. The equal-weight ten-year on the board stands at 4.23%, from 4.29%; the house sovereign pressure index fell to −1.66 from −1.16 — less pressure, not more.
The consequence — the map, restated. This letter's positioning: this diary stays away from mainland Europe's core, and from France in particular; Greece and Poland stay the exceptions. This week the core bounced 2% and France's spread narrowed by six points — one good week after a month of bad ones does not change the map. The book holds Switzerland, and it was the book's second-best line again. This is a diary's positioning, not advice.
Oil — held at the top. The oil fund slipped 0.41% to 168.83, 0.4% under last week's high close of the year; the Brent fund rose 0.56% to 71.39, a new record close. US energy closed at its highest of the year, 70.02, and global energy at 64.19. Oil at these levels is a cost for every economy that imports it — Europe and most of Asia — and the falling ten-year now rests on it staying here, not going higher.
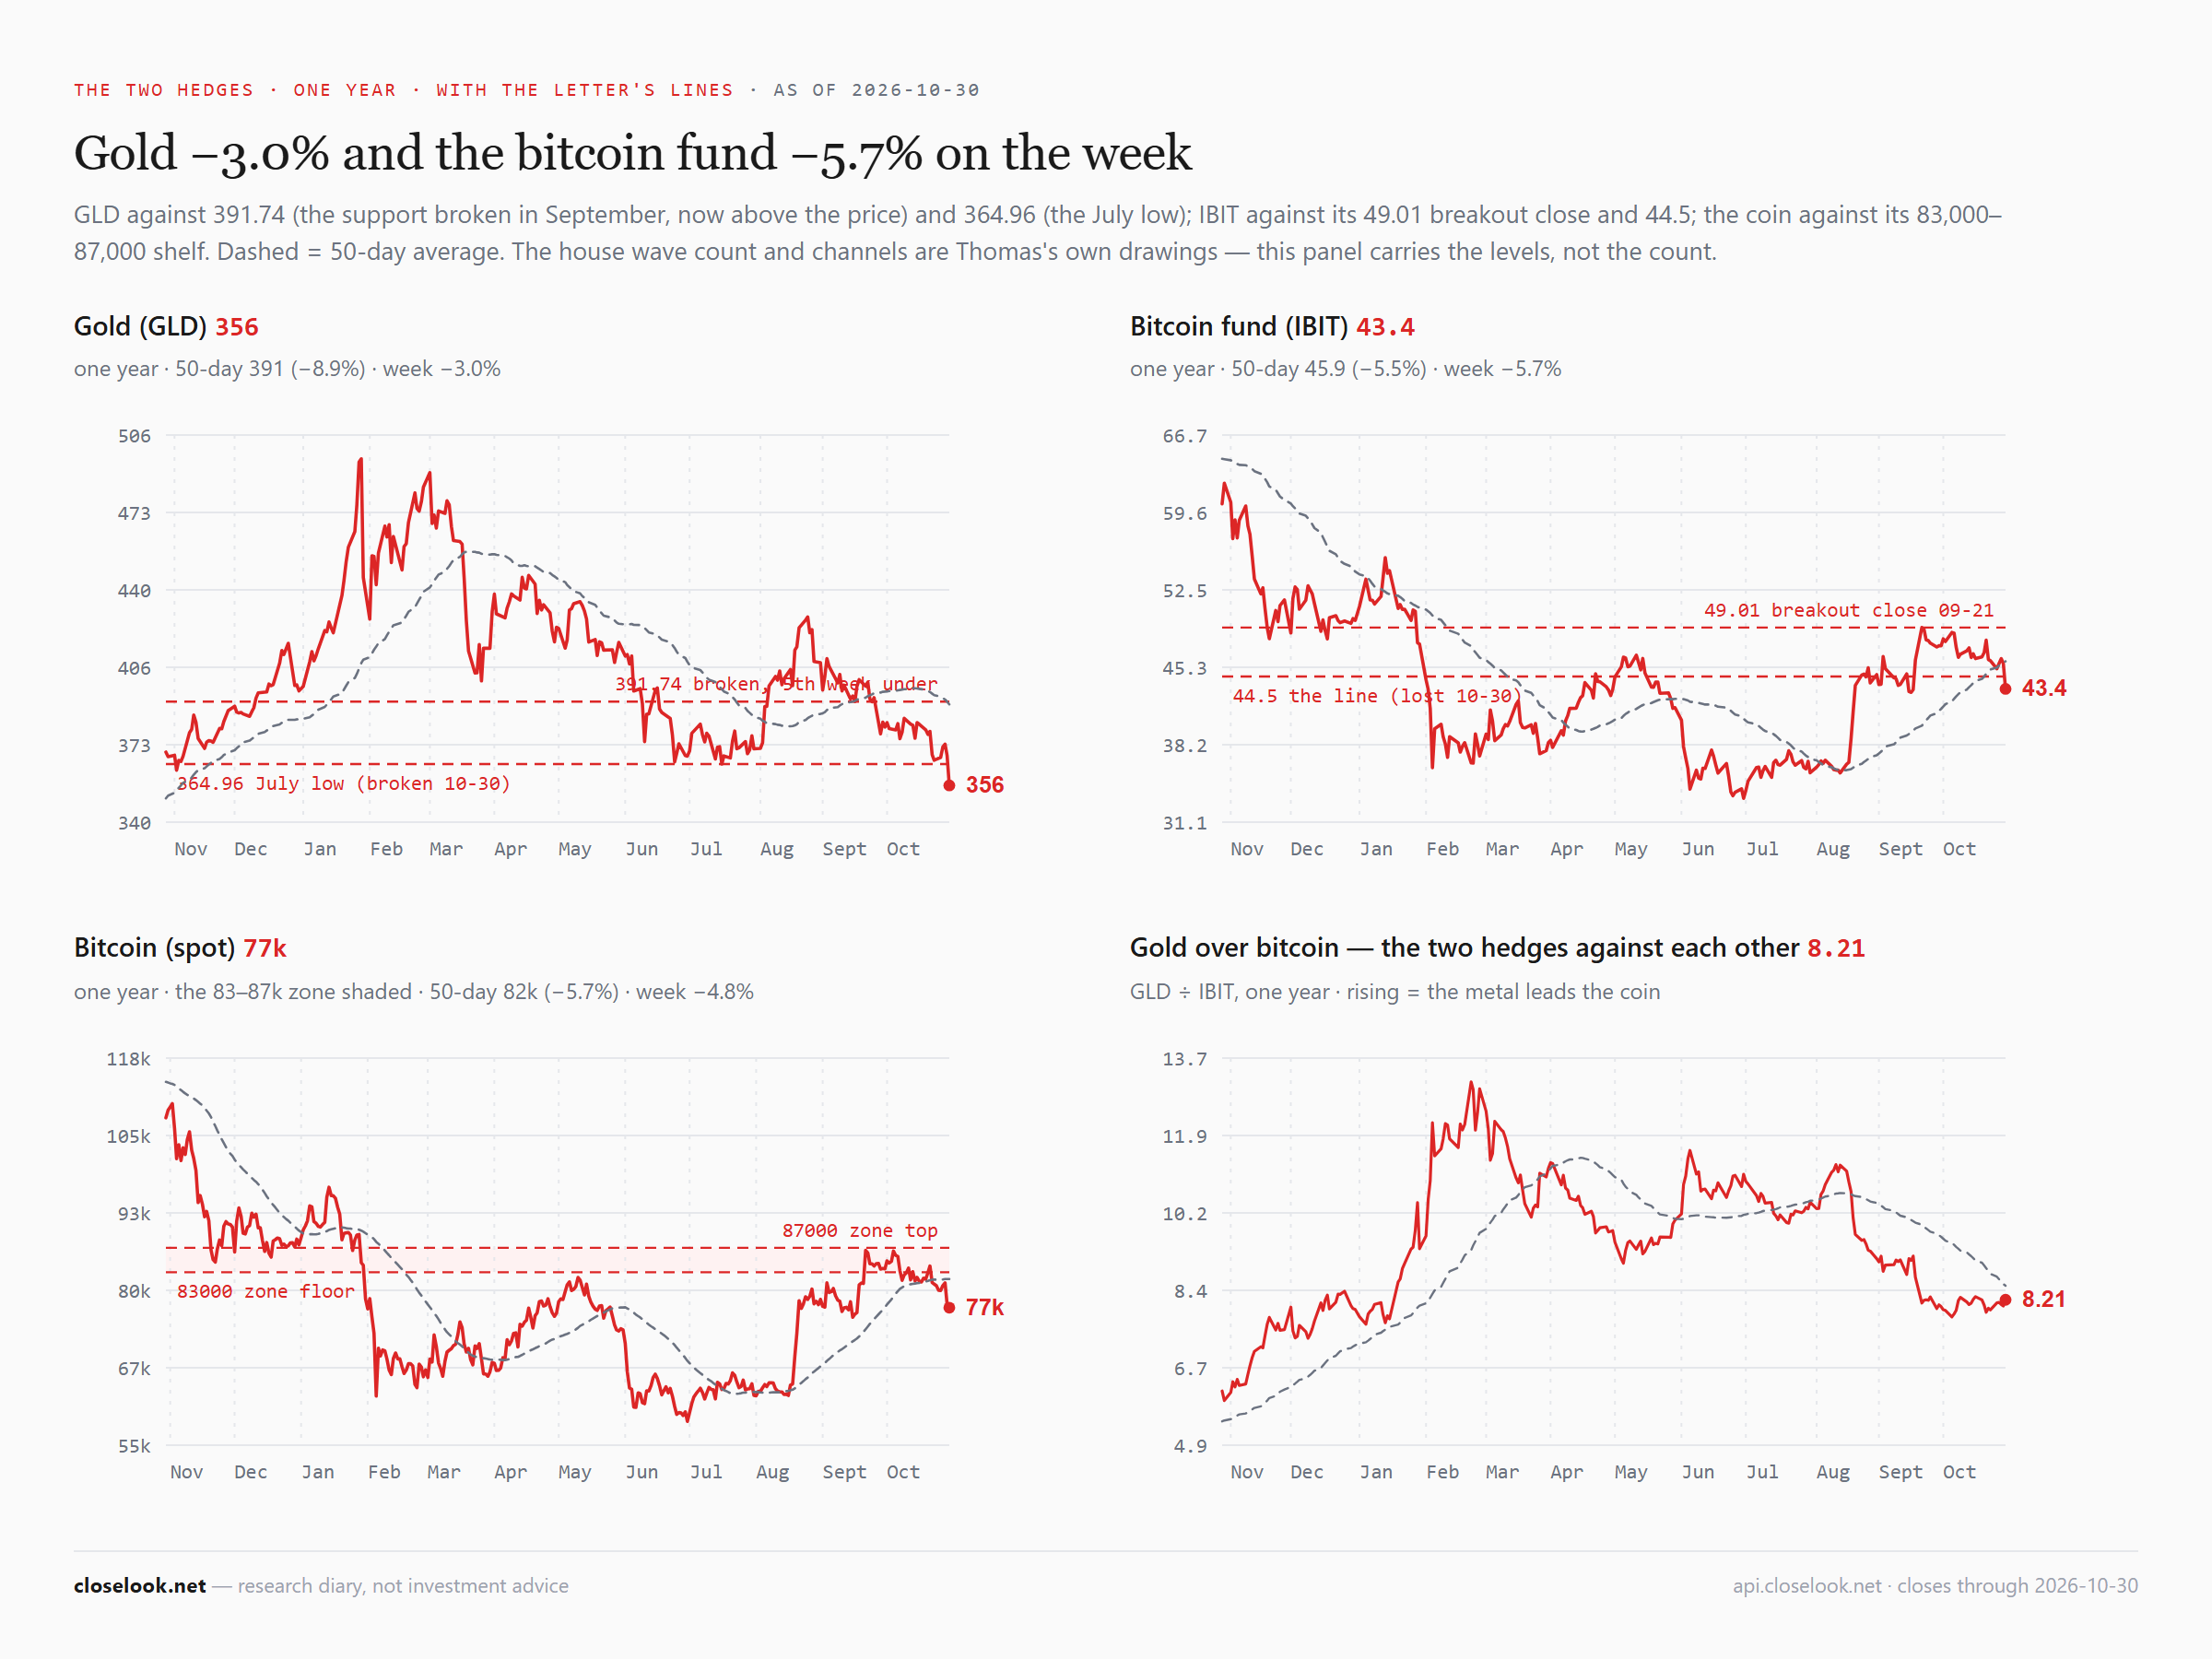
The hard assets — the July low broke. Gold fell 2.95% to 355.78 — under its July low close of 364.96 and the lowest close of the past year, 28.3% under its January 29 record of 495.90. Silver fell 8.46% to 44.60, its lowest close of 2026, 57.8% under its January high. Copper miners fell 1.55%. Bitcoin closed Friday at 77,192, −4.8% on the week; the fund fell 5.66% to 43.36, under the 44.5 line. Last week the metals fell while oil rose. This week they fell again while the bonds rose. The metals are trading slower growth, not inflation.
Seoul: up on the week, down on the day. The fund walked 152.72 → 157.46 → 165.91 → 161.83 → 152.89. Wednesday's close was the highest in three weeks; Friday's gave almost all of it back. EWY is 30.3% under its June high and +57.3% on the year. In won the Kospi still closed the week 3.3% higher at 5,731 — a dollar investor got about a third of that.
Taiwan: the steep line, a second week under. EWT closed 105.61, 107.25, 108.94, 105.99, 101.11. Last week the editor's chart showed the steep channel that carried the fund all year broken. This week the fund tried to get back toward it on Wednesday and failed; Friday's close is the lowest of the two weeks since the channel broke. Taiwan is still +59.2% on the year.
Europe, the voting machine and the weighing machine. Euro-AI rose 2.87% to 1,254.83, six of seven sleeves green: power, grid and cooling +4.70%, semi equipment +3.82%, defence +2.94%, industrial AI +2.48%, medtech +2.10%, enterprise AI and data +1.22% — only chip architecture fell, 1.99%. A week ago Europe's machines and power fell while its software rose. This week the machines and the power came back.
The macro print. Three numbers: a 4.93% US ten-year, gold under its July low, and Brazil −24%. The first says the rate peak holds. The second says the market is pricing slower growth, not more inflation. The third says a single election can still take a quarter out of a country fund in a week — which is the risk of owning one.
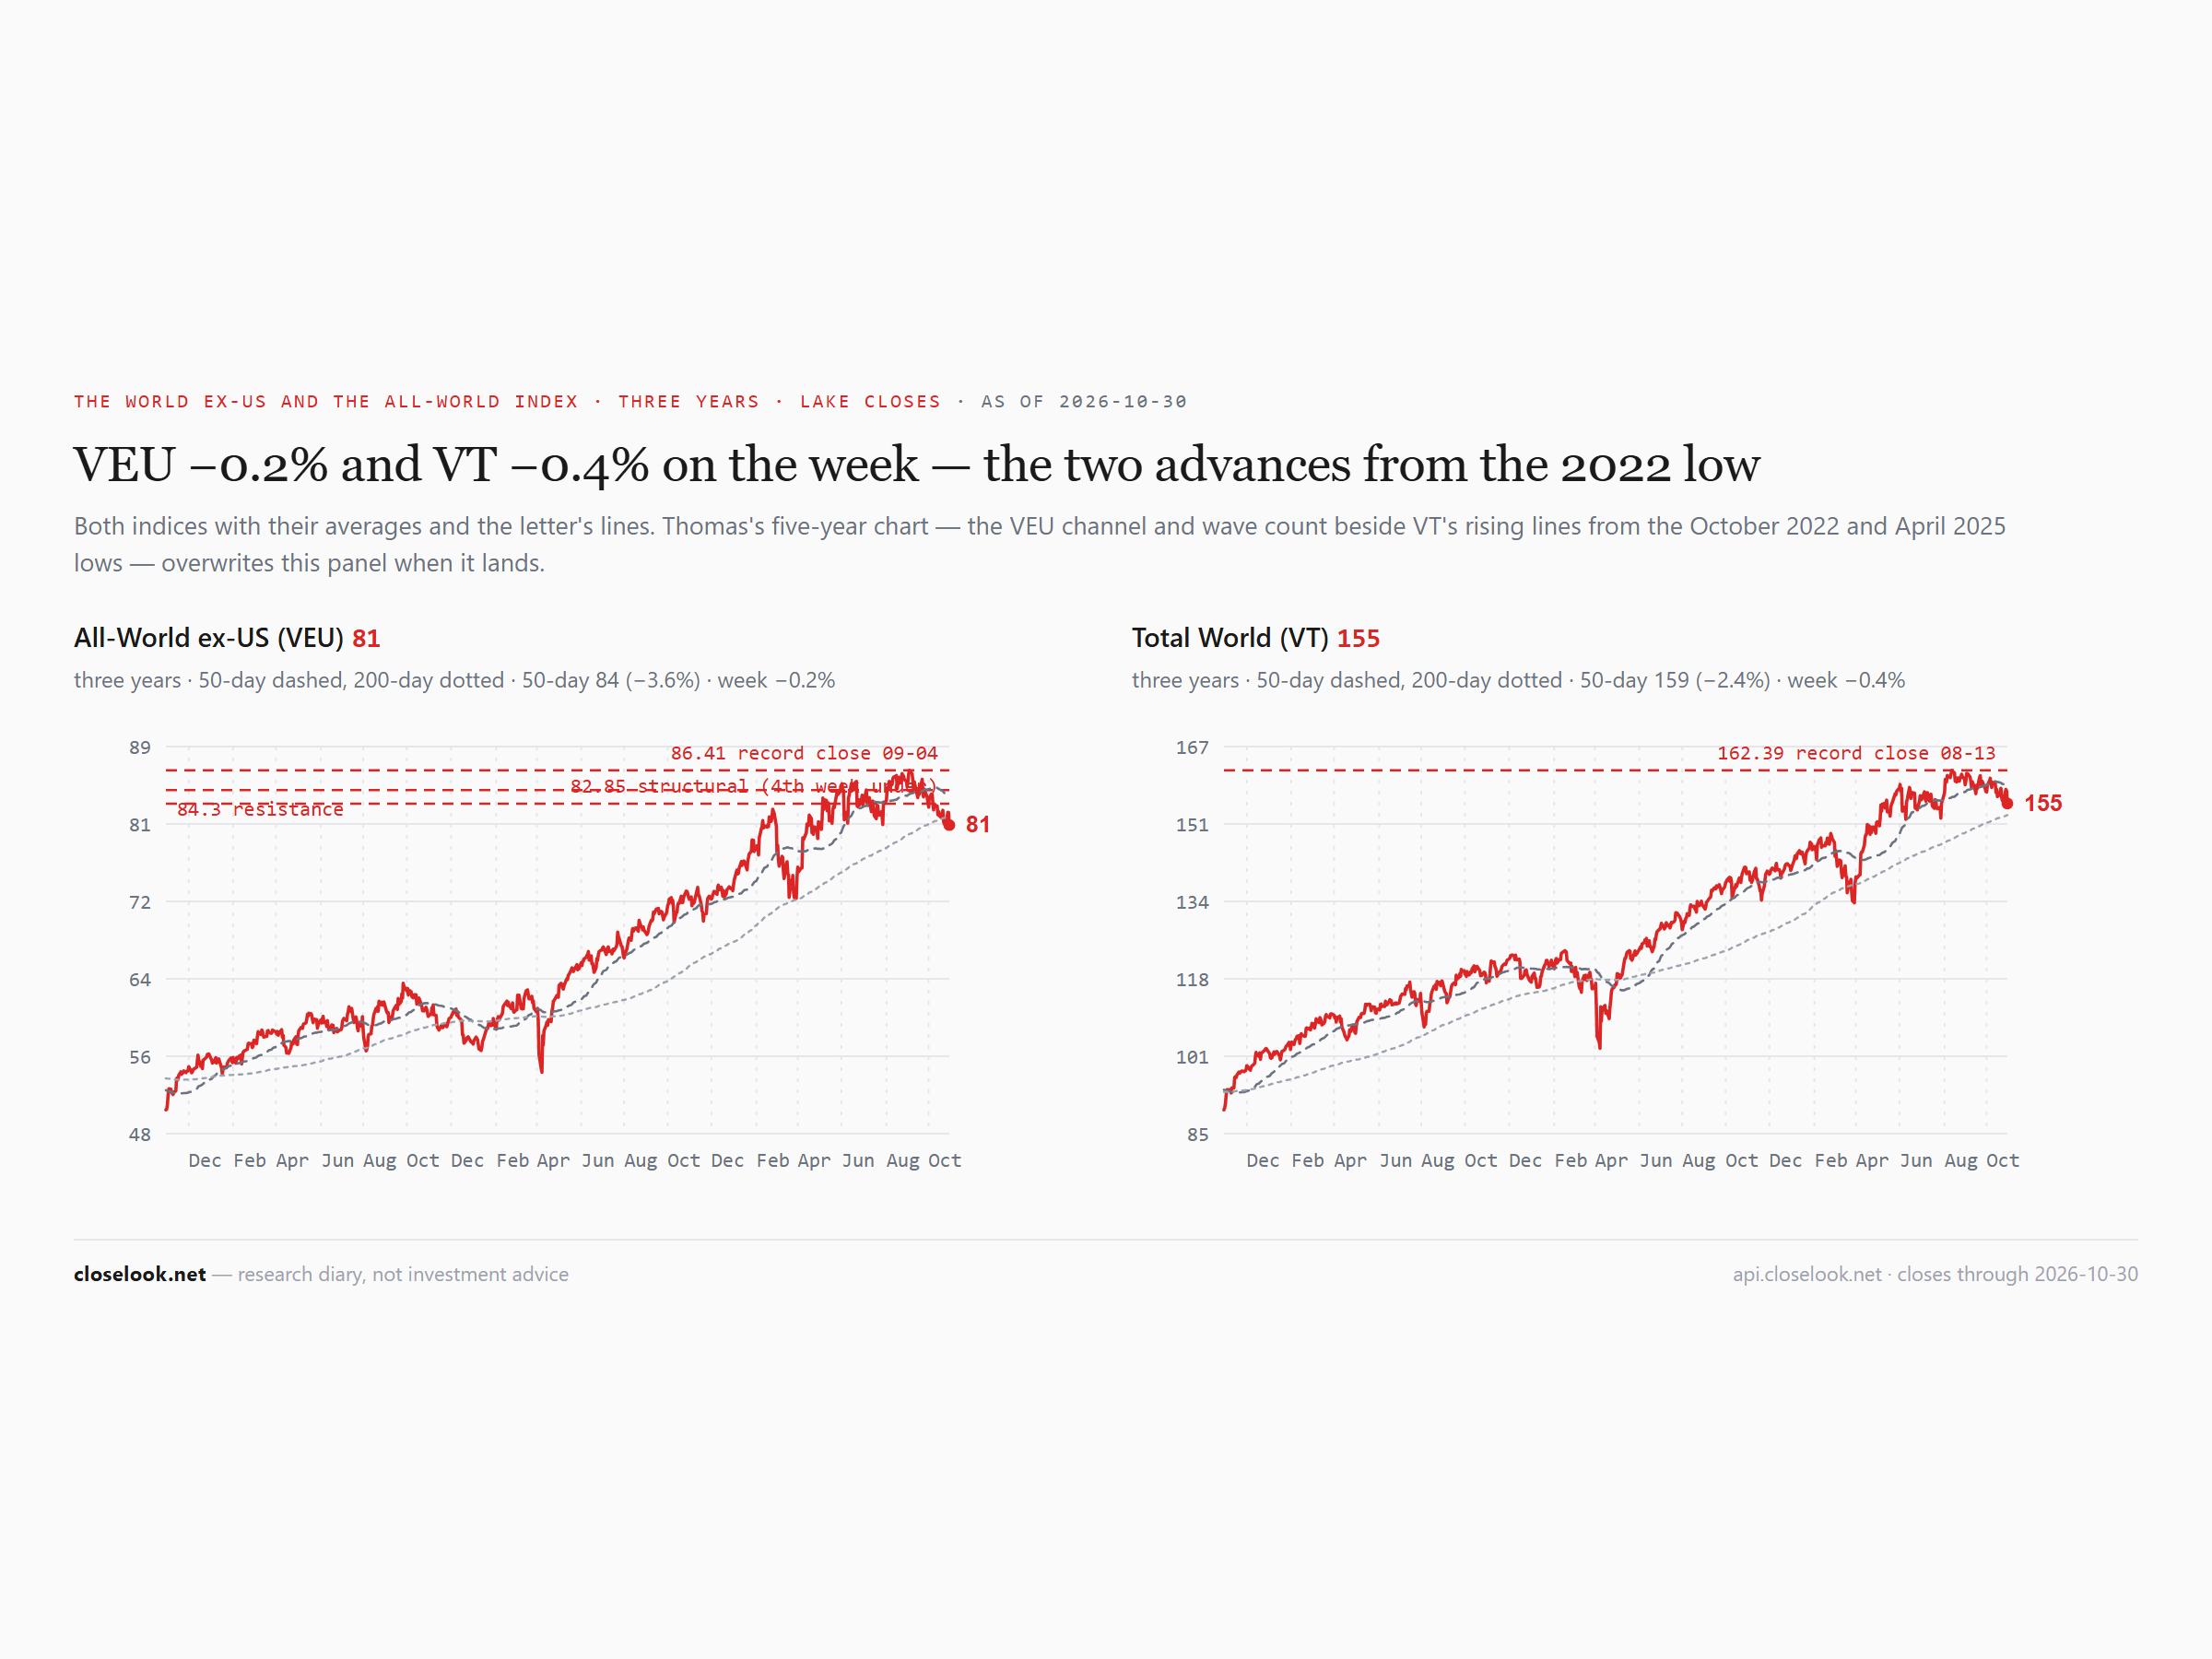
The structural read — the world ex-US held its floor, the all-world did not get back into its range. VEU's Friday close of 80.57 and its intraday low of 80.06 sit on the horizontal support near 80.3 — the summer lows: 79.83 on 4 May and 80.38 on 29 July. The editor's preferred count reads the world ex-US as forming wave 4, a complex consolidation, and this line is where a fourth wave would be expected to hold. It held for a second week. VT closed at 155.33, under last week's 155.90 on the upper line of the channel from 2022 and still under the 156.82 floor of its August–October range. On the editor's alternative count the all-world advance since April 2025 is a fifth wave; a weekly close well under the 2022 channel line would be the first sign that it has ended. This week's close is a hair under it, not well under it.
3 · The Outlook
The three-index read — the builders held, the runners and the sellers fell. We read the three together because they are three stages of one spend: capex (Rubin Build-Out, what gets built), opex (Agentic Ecosystem, what it costs to run), applications (Agentic Winners, what gets sold on top).
Capex +0.57% on the week to 1,713.44, twenty-three of thirty-six sub-indices green, +66.7% on the year. Opex −5.28% to 1,540.57, one of fourteen green, +56.1%. Applications −5.43% to 913.38, one of nine green, −6.7%. Last week the ladder split by twelve points with the builders at the bottom. This week it split by six with the builders at the top.
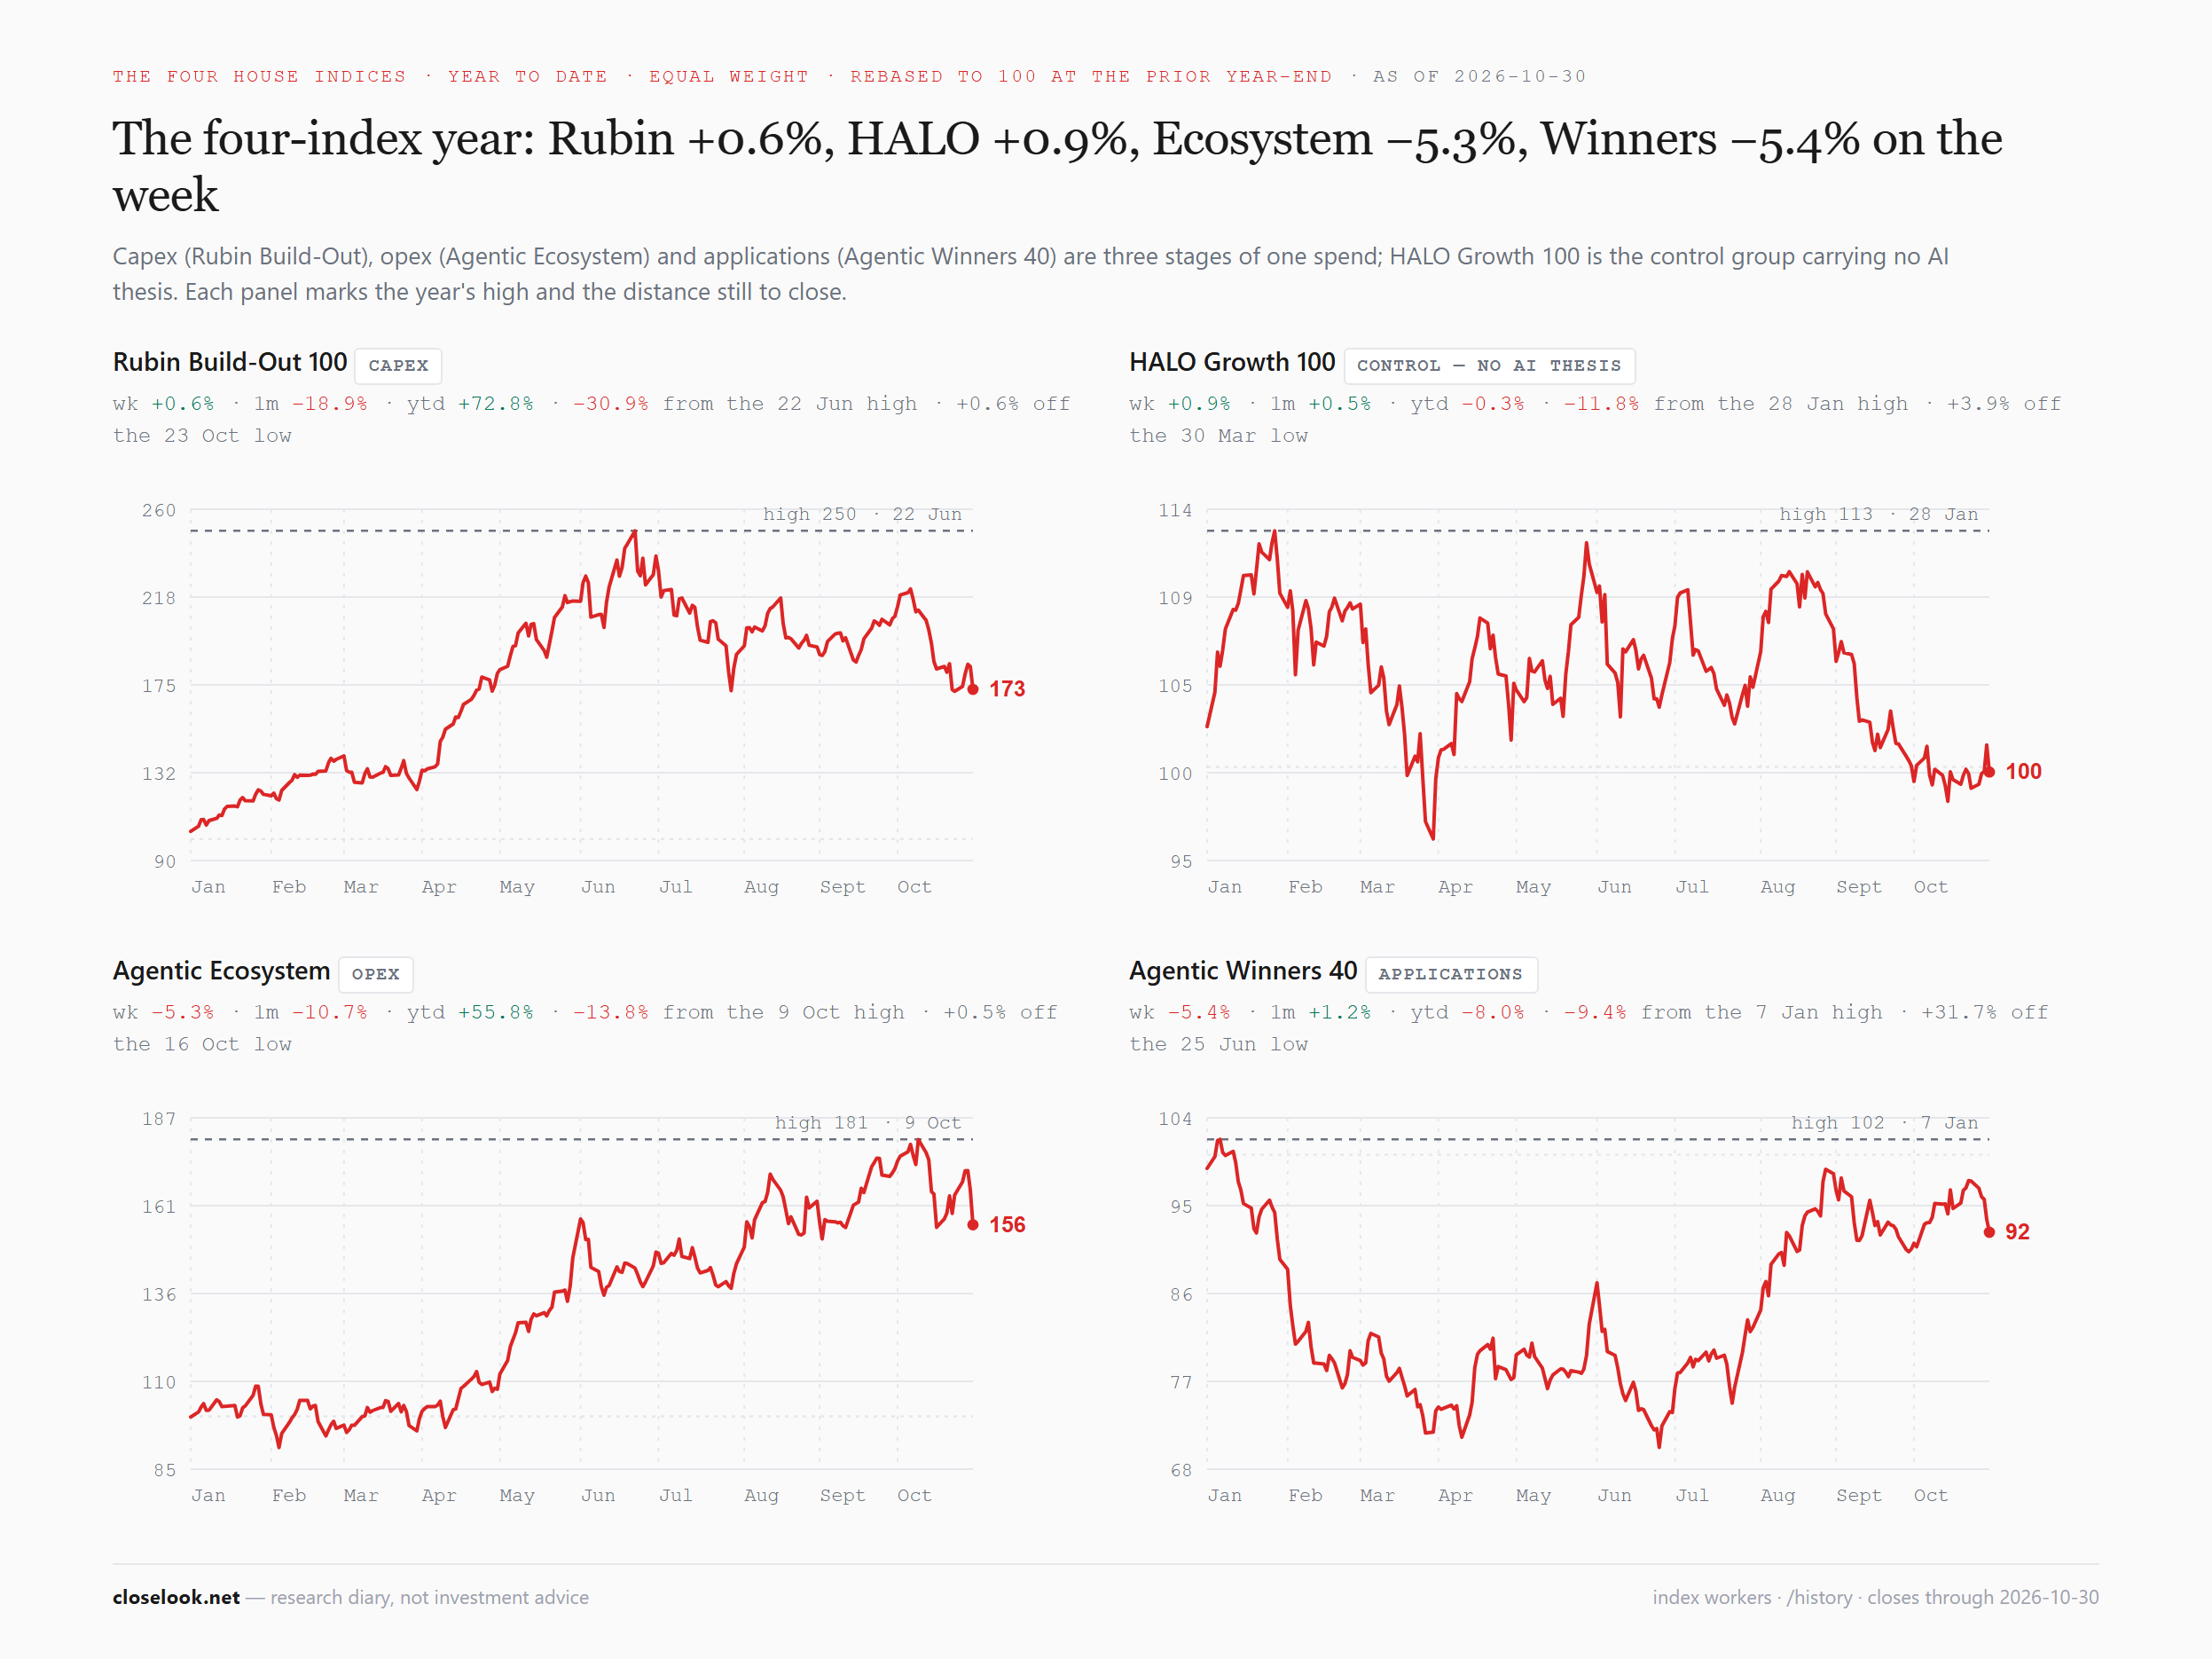
The control group rose. HALO — our growth index carrying no AI thesis — rose 0.91%, −2.5% on the year, fourteen of twenty-three sleeves green. Inside it, space and satellites +6.05%, longevity +4.88%, the speculative leg +4.50%, defence and drones +3.18% — while Latin America fell 6.25%, payments 4.92% and Asia-Pacific 3.59%.
Read the windows together. On the year capex still leads: +66.7% against +56.1% against −6.7%. On the month the applications lead again: applications +1.2%, opex −10.7%, capex −18.9%. The index with the worst year has the best month for a second week.
The distances to the highs. Capex 30.9% under its June 22 high. Opex 13.8% under the record it made on October 9. Applications 9.4% under its January high. HALO 11.8% under January. The US letter reads the shapes these four lines are drawing; this letter carries the levels.
Inside capex: the power and the memory led. The green: data-centre power and electrical +6.03%, data-centre construction +5.82%, HBM memory +4.59%, chip design +3.95%, the Europe constituents +3.88%. The red: substrates and interposers −6.51%, the AI factory systems −3.63%, grid and power infrastructure −3.50%, Asia-Pacific ex-Japan −2.76%, advanced packaging −2.33%. Last week the physical build-out fell hardest. This week its power and construction legs led.
Inside opex: everything fell but Europe. The one green: the Europe constituents +2.06%. The red, worst first: runtime and API gateways −10.70%, operations and observability −9.58%, govern and secure −6.85%, agentic security −6.84%, execution −5.76%. The layers that watch, secure and govern AI led last week by 10 to 15 percent; this week they gave back half of it.
Euro-AI, for the ladder's sake. The sovereign-Europe index rose 2.87% to 1,254.83, +25.5% on the year, 9.8% under its June high, six of seven sleeves green. On the ladder, Europe's AI index was this week's best.
The regime gauge. The Money Temperature board closed the week at 46, unchanged — mixed and transitional, inside neutral and, by its own construction, not a signal. The instruments: the Nasdaq 100 57, the dollar 52, the S&P 49, the long bond 49, emerging markets 45, bitcoin 42, the world ex-US 41, gold 31. A week ago bitcoin read 56 and the dollar 61; both cooled.
4 · What May Lie Ahead
The fourth quarter — the map holds its shape, the leader does not. This letter's expectation for the rest of 2026: America and Asia's corridor lead, mainland Europe and India trail, the dollar stays firm. Four weeks in: America still leads the year, the dollar has stopped rising, the corridor's leader is a second week under its trend line — and a week ago software stepped up to lead and this week it was sold. The expectation stands, with a caveat: a market that buys health care, staples, Switzerland and the bonds for four weeks in a row is a market waiting for a reason, and the reason has not come.
The season — the stance stands. This letter expected uncertainty through the reporting season and named the stance: buy dips, do not chase. This week showed what the season rewards: the suppliers that beat were paid, the spenders that beat were sold. The stance stands. On the editor's alternative count, the late part of a move rewards patience less and selection more.
The calendar. US clocks go back on Sunday 1 November — from Monday the New York close is 21:00 UTC. Apple and Palantir report after Monday's close, AMD on Tuesday. The midterm elections are on Tuesday 3 November, results into Wednesday. The Fed's next decision is on 9 December, with new projections; futures put a hike near 80% after Thursday's data.
Levels and tripwires — VEU first, on the floor for a second week. The marks: 86.41 the record close (September 4); 84.30 resistance; 82.85 the structural line — four weekly closes under it now; 80.57 Friday; the summer-low support near 80.3 — 80.38 on 29 July, 79.83 on 4 May, this week's intraday low 80.06; 72.75 the spring low (March 30). A weekly close under about 80 would say the fourth wave is deeper than drawn; a weekly close back above 82.85 would say it is ending.
VT — still under its range. 162.39 the high close (August 13); 156.82 the bottom of the August–October range, above the price for a second week; 155.33 Friday; 152.22 the July low; 134.19 the spring low. A close back above 156.82 puts VT back in its range; a weekly close well under the 2022 channel line would be the first sign that the fifth wave has ended.
The leadership pair — software and Taiwan, both lower. IGV 104.29 — the line near 110 lost after one week above it; 112.67 the high of the year (October 9); the round 100 below. Taiwan's EWT 101.11 — a second week under the steep line, 118.00 the record above, the round 100 just below. Last week this letter wrote that a weekly close for IGV above 112.67 would confirm the change of leadership and software back under 100 would cancel it. Neither happened. The test is open, and it now starts six points lower.
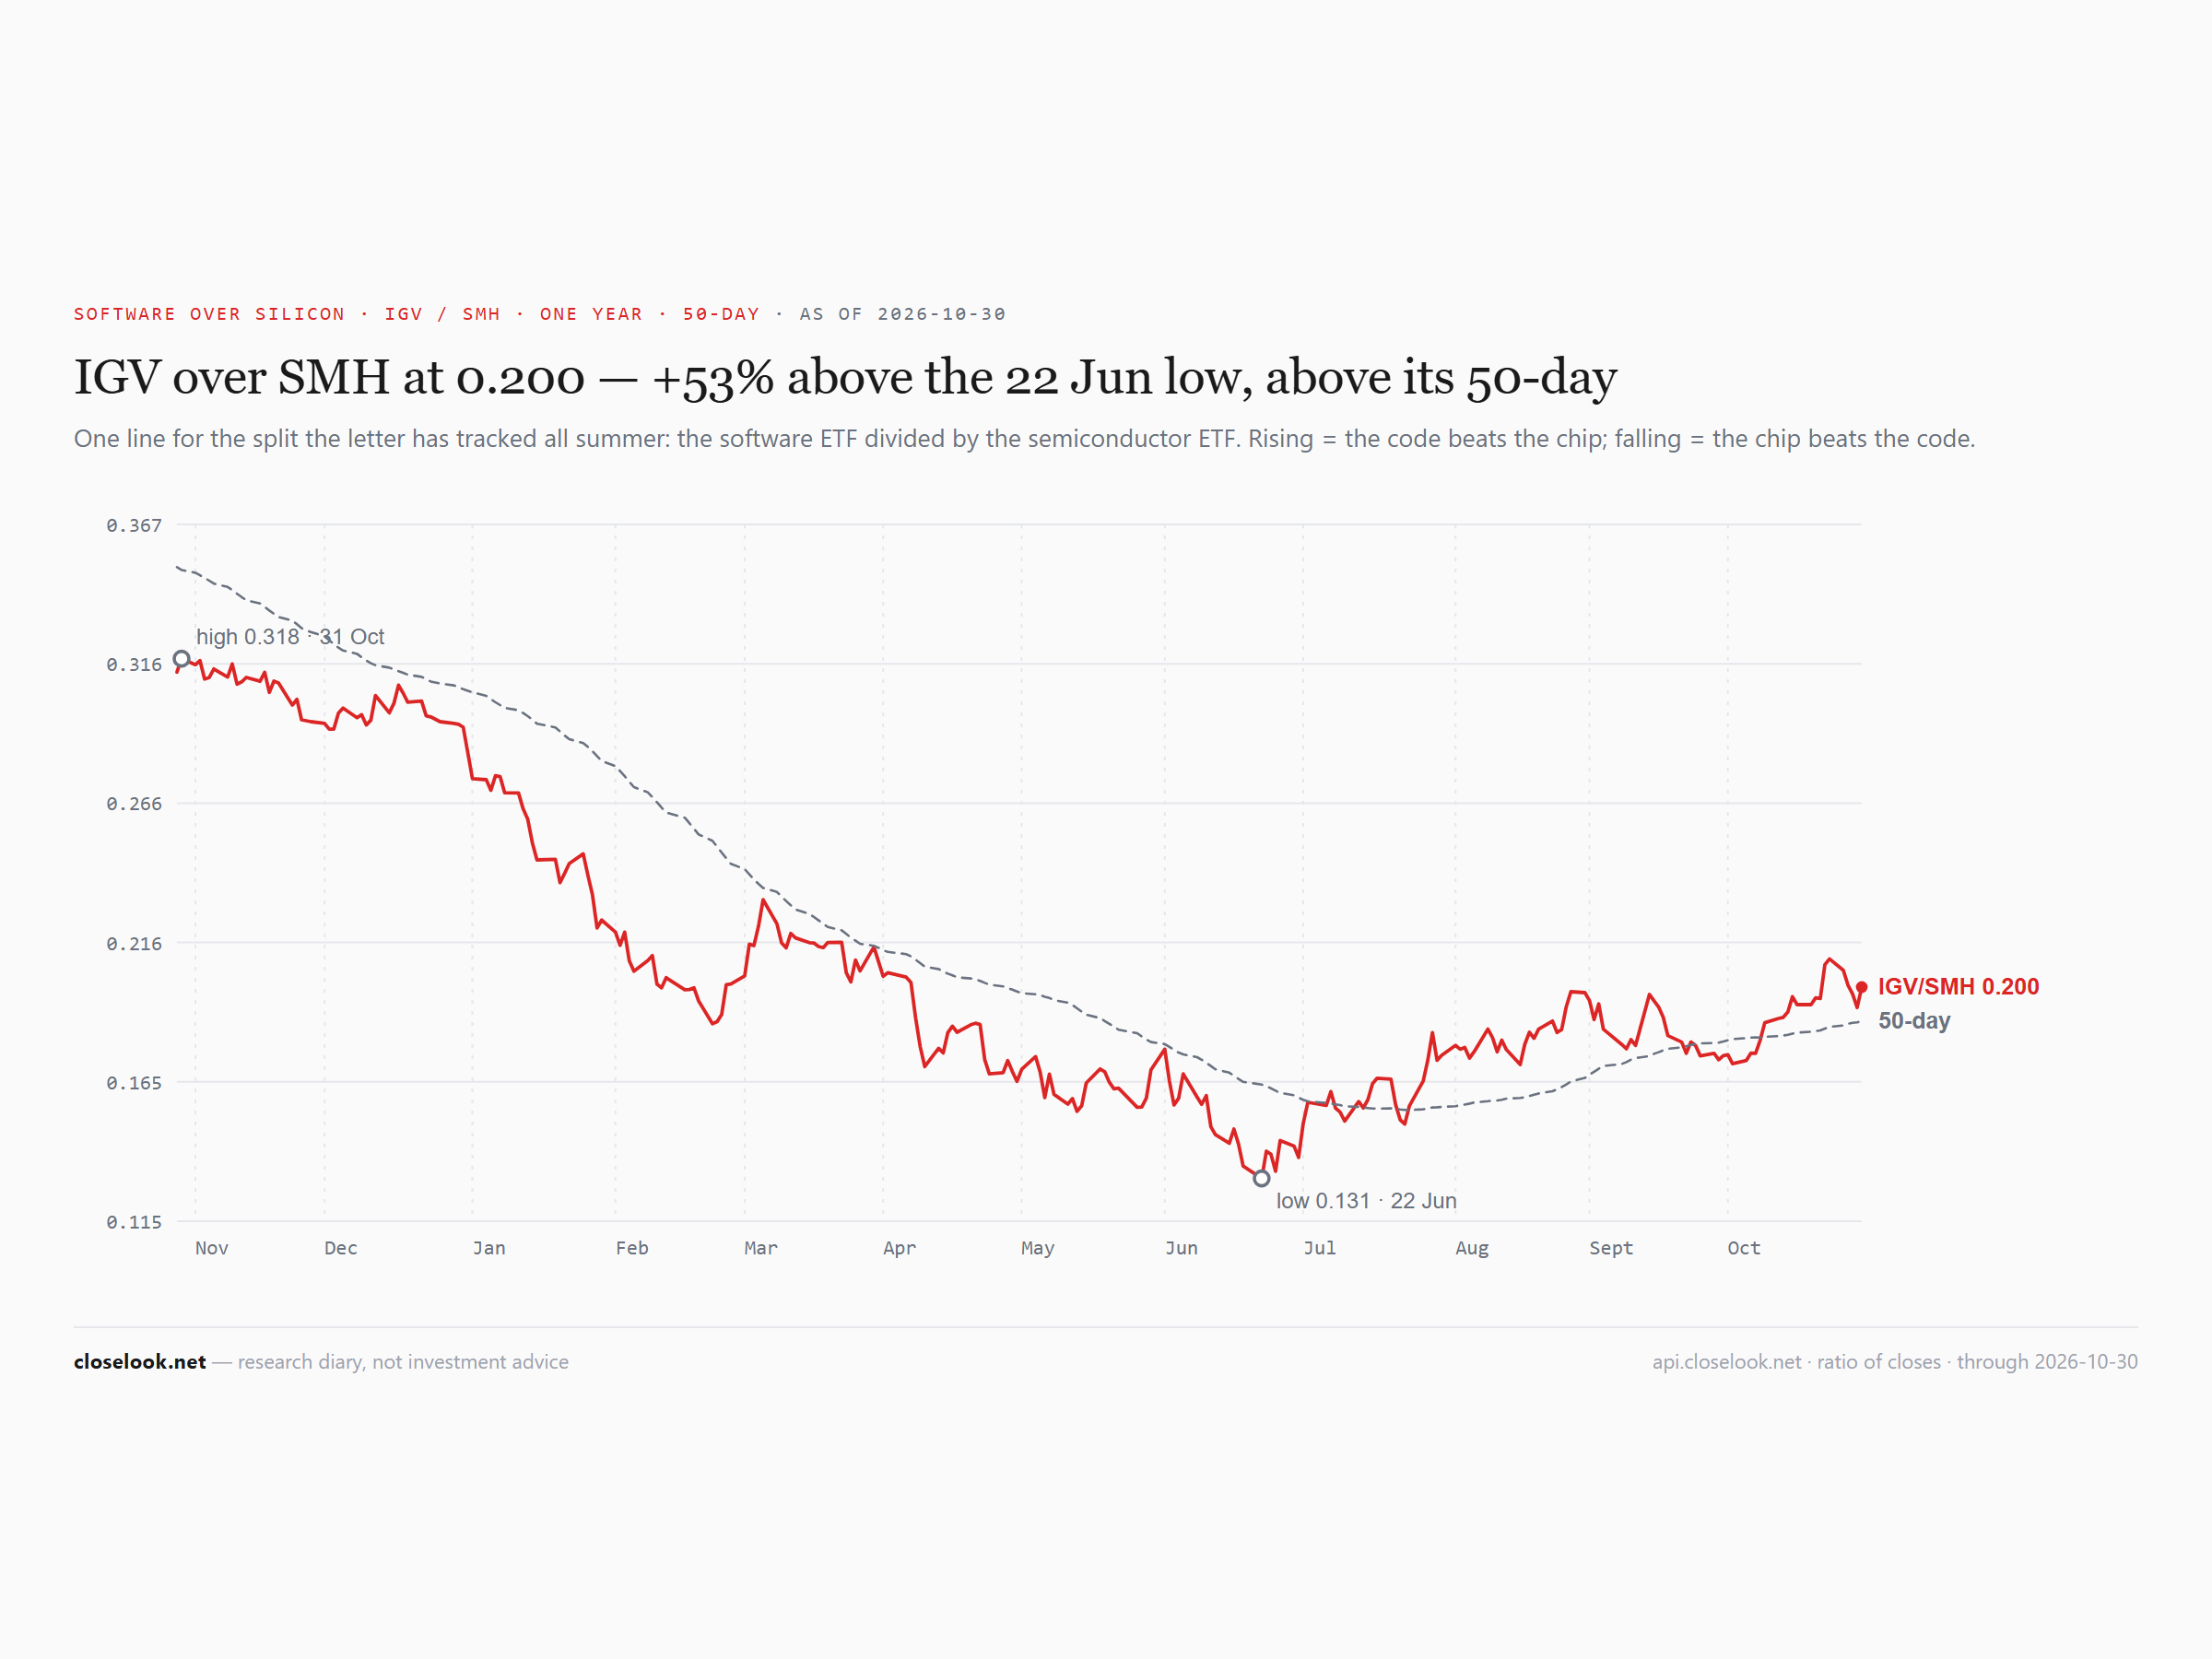
The leadership test abroad — not confirmed. Last week's test: Europe's tech beating developed Asia's, Euro-AI's enterprise layer beating its semi-equipment layer, the Netherlands, Taiwan and Korea lagging the broad ex-US index. This week: Europe's tech beat Asia's again (+0.9% against −1.7%) — but Euro-AI's semi-equipment layer beat its enterprise layer (+3.8% against +1.2%), and Korea and the Netherlands beat the ex-US index. One of three held. The software rally was an American week, and America then sold it.
The long bond — the line held. TLT 81.84, a second week above 81.2; 77.11 the October low close; 74, the October 2023 low, below. IEF 91.76, still under 93.17.
The ten-year — under the line. 5.31% on 5 October is the high close; 4.93% is Friday's — the first weekly close under 5.0%. A close back above 5.31% would say the peak was not one. Under 4.9% the next question is how much of a December hike the market still believes.
France — the spread narrowed. 161 basis points over the Bund on the house series, from 167; a ten-year yield of 4.97% against America's 4.93%. The next line above is the round 200; a narrowing back under 135 would say October was a spike, not a trend.
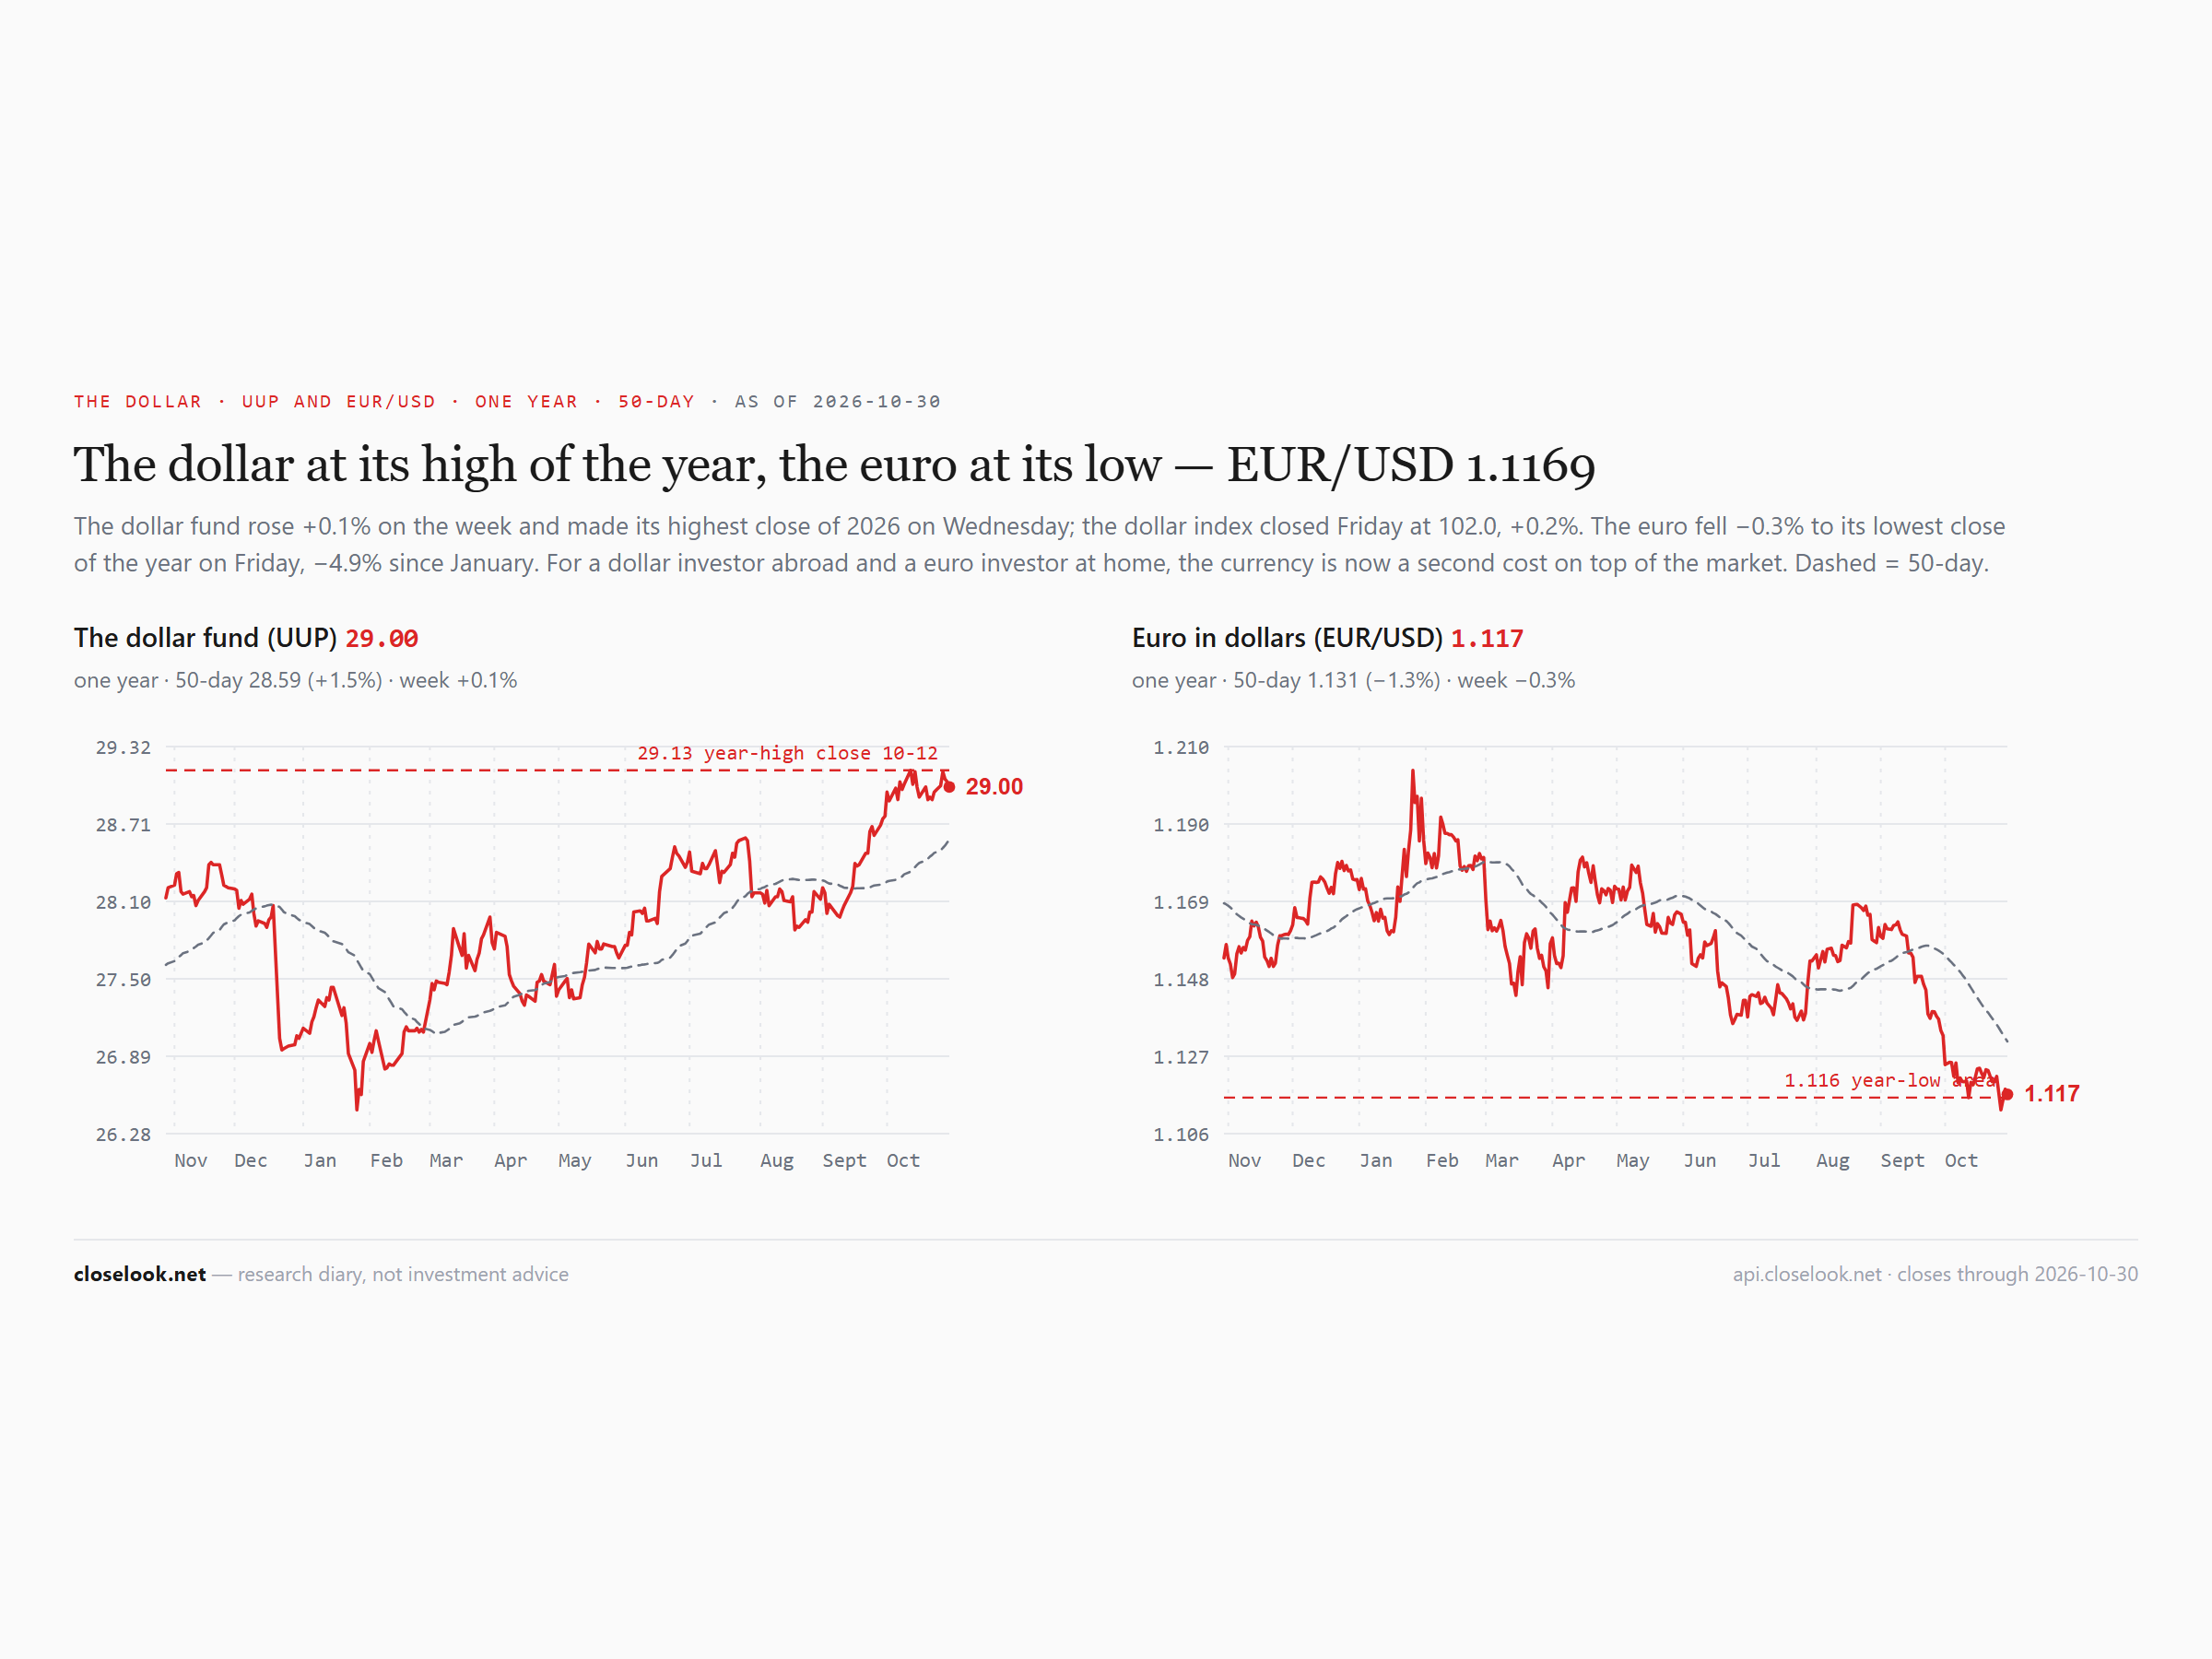
The dollar and the yen. The dollar fund's 29.13 on 12 October is the year's high close; 29.00 Friday. EUR/USD 1.1169, a tenth of a cent above the year's low near 1.1160. USDJPY 157.52, from 156.74: 160 the door, 155 the level that brings the intervention talk back.
EWY 152.89 — Friday took the week. 165.91 the week's high close, 149.06 last week's low close; 180 far above. On the year the fund is still up by more than half.
Gold and the coin — new lines. Gold 355.78; the July low of 364.96 is now above the price, 391.74 above that. The bitcoin fund 43.36 under the 44.5 line; bitcoin 77,192 under the 83,000–87,000 zone. A weekly close for gold back above 364.96 would say Friday was a flush; a second week under it would make the July low a ceiling.
Brazil — after the reset. EWZ 32.46; 43.54 the record close of the year (October 9); the 52-week low close 30.97 (22 December 2025) is 4.6% below. The country fund now sits where it started 2026, +2.2% on the year.
5 · The ETF Portfolio — Global ETFs
Global ETFs — 16 positions · unrealized -3.4% · benchmark Nasdaq-100 · snapshot Nov 5, 2026
| # | Symbol | Name | Weight | Unreal. |
|---|---|---|---|---|
| 1 | VEU | — | 11.9% | -0.3% |
| 2 | QQQM | — | 8.9% | -10.3% |
| 3 | XLK | — | 8.1% | -12.3% |
| 4 | SMHX | — | 7.4% | +9.6% |
| 5 | INDA | — | 6.6% | -3.5% |
| 6 | QTOP | — | 6.6% | +13.4% |
| 7 | TOPT | — | 6.5% | +26.4% |
| 8 | SPMO | — | 6.1% | -22.2% |
| 9 | FLSW | — | 6.0% | +3.5% |
| 10 | EPOL | — | 5.8% | +7.5% |
| 11 | IBIT | — | 5.7% | +16.4% |
| 12 | EWT | — | 5.7% | -13.9% |
| 13 | ILF | — | 5.3% | -10.1% |
| 14 | GLD | — | 5.0% | -5.3% |
| 15 | EWY | — | 4.4% | -28.8% |
+ 1 more position · full per-position cost basis & P&L is C+ subscriber-only.
What we did this week: nothing — a fifteenth consecutive week without a transaction. The July rebuild remains the decision. Saturday's Pulse carries the five books' ledger: the four equity books did not trade; the derivatives book bought back three short puts and a short call on Thursday, a day before the chip fall.
The book, marked — the $6,469 week. The fifteen-position book closed Friday at a market value of $317,833 — down $6,469, or 1.99%, from $324,303 at last Friday's closes. Unrealized gains +1.87% on cost, from +3.95%; realized gains unchanged at $42,599; a headline return of about +19.4% on the $250,000 deposited. Three of fifteen lines green, twelve red.
What the week paid it — and what it charged. India +2.71% (+$504), Switzerland +2.36% (+$410), Korea +1.08% (+$163) — together $1,077. The charges: Latin America −14.77% (−$2,814, the book's worst by far), the bitcoin fund −5.66% (−$1,040), Taiwan −3.61% (−$758), QQQM −1.97% (−$573), XLK −2.03% (−$559), the Nasdaq top-30 line −2.39% (−$529), gold −2.95% (−$433), US momentum −1.72% (−$359); smaller, the fabless fund −$202, the US top-20 −$181, VEU −$59, Poland −$40. One line — Latin America, which is mostly Brazil — cost 43% of the week's loss.
What we plan to do: nothing on Monday — with the Latin America question on the table. ILF was bought as a diversifier: a region whose fortunes do not run on the AI cycle. This week showed the other side of that — a region that runs on its own politics. The line now carries 5.1% of the book, from about 5.9% a week ago. No decision today. The watch-items are the levels above — EWZ against its 30.97 low, VEU on its summer lows, the ten-year under 5.0%, the midterms on Tuesday.
The wikifolios — day zero. From this letter on, the four wikifolios that run alongside these books are marked here every week, and the end of October is their day zero: the closes of Friday 30 October are the line every later week is measured from. They are published on the wikifolio platform, where every transaction is visible, trade by trade: Core and Conviction, AI Cycle 2030, Global Generation and The Compound.
Where they start. Since each one's own start, against a comparison of our own choosing (an ETF on the same theme, rebased to the same day) — past values, all under twelve months, no forecast:
| wikifolio | Started | Since start | Our comparison | Since the same day |
|---|---|---|---|---|
| Core and Conviction | 20 July 2026 | −1.23% | Nasdaq-100 | +4.27% |
| AI Cycle 2030 | 25 July 2026 | +6.22% | Nasdaq Global AI & Big Data | +10.17% |
| Global Generation | 2 August 2026 | +3.28% | FTSE All-World | +5.20% |
| The Compound | 18 August 2026 | −1.21% | MSCI World Equal Weighted | +1.76% |
All four start behind their comparison. That is the honest line to start from. Core and Conviction is the concentrated one: its stock core is the AI-capex four this diary owns rather than trades — Nvidia, TSMC, SK Hynix and Advantest — alongside a set of ETFs. AI Cycle 2030 spreads the same thesis across about fifty names. Global Generation is the ETF book's thinking in wikifolio form; The Compound holds the non-tech compounders and is still in its test phase. How the vehicles work, and who the issuer is, lives on the Trade the Look page. Nothing here is a recommendation; this is a research diary.
6 · What May Go Wrong
One: the December hike arrives with growth still strong. The bond market priced the peak this week, but the futures price a hike in December near 80%. If the data stay hot, a close back above 5.31% on the ten-year would take away the floor under this month's defensive leadership — health care, staples and the bonds all lean on falling yields.
Two: Friday was the first day, not the only one. The chip index fell 7.2% in a session after rising 8.4% in three. Taiwan under 100 on a weekly close, and Korea back under last week's 149.06, would say the corridor's selling is a second leg, not a single day.
Three: Brazil spreads. This week it did not: Mexico −1.0%, emerging markets −1.6%. A second week in which Latin America falls with the emerging-markets fund behind it would turn a country repricing into an asset-class problem — and the book's Latin America line is already its worst.
Four: the metals are right. Gold under its July low, silver at its low of the year, copper miners lower — against oil at a record. Falling metals and rising oil together is the shape of slower growth with sticky prices, and Europe and Asia import the oil.
Five: the midterms move the bonds. A result that changes the fiscal outlook would reach the ten-year first. A close back above 5.0% after Tuesday would say the market read the result as more borrowing.
7 · Knowledge Corner
What an election does to a country fund — reading Brazil's week. A dollar-listed country fund like EWZ carries two prices at once: the price of the country's shares in their own currency, and the price of that currency in dollars. An election can hit both on the same day, and when it does, the losses multiply rather than add.
This week, in numbers. From Friday to Friday, Brazil's main index, the Bovespa, fell 18.1% in reais. The real lost about 8.5% against the dollar. A dollar investor holding the index therefore lost about a quarter: 0.819 times 0.915 is about 0.75. The fund itself fell 23.8% — close to that figure, with the gap coming from what the fund holds and how it weighs it.
Why so much in one day. Three things stack in an election week. The first round sets a bet: after the first round Brazil's fund rose to its record close of the year on 9 October, priced for one outcome. The weekend gap: the runoff is on a Sunday, so the whole reaction lands in Monday's first trade — a Tokyo-listed Brazil fund fell nearly 15% before Brazil even opened. Concentration: a country fund is heavy in a few banks, a few commodity producers and the state-linked companies most exposed to policy.
| What moved | Friday 23 Oct | Friday 30 Oct | Week |
|---|---|---|---|
| Bovespa (reais) | 205,083 | 167,922 | −18.1% |
| Dollars per real | about 0.201 | about 0.184 | −8.5% |
| Brazil fund EWZ (dollars) | 42.59 | 32.46 | −23.8% |
| Latin America 40 fund ILF (dollars) | 37.70 | 32.13 | −14.8% |
What this means for reading a book. A country line is two bets in one: on the shares and on the currency. A regional fund like ILF spreads the country bet, but not the political one when the biggest country in it is the one voting. The house reads a week like this the way it reads a broken support line: as information about what the line is exposed to, which the next weekly closes either confirm or soften.
8 · Final Words
Investors raised cash this week, but they did it one place at a time. On Monday they left Brazil, and the country fund lost almost a quarter in a week. On Friday they left the chips, and Korea and Taiwan went with them after rising into Wednesday. In between, Europe rose, Switzerland closed at a record, India rose, and health care climbed in three regions out of four.
The US ten-year closed the week under 5 percent for the first time since the peak in early October — the close this letter had named as the confirmation. Gold closed under its July low, silver at its low of the year, bitcoin under its line. The metals and the bonds are saying the same thing: slower growth ahead, even with a December hike priced.
The world ex-US held its summer-low support for a second week. The all-world index stayed under its range, a hair under its 2022 channel line. Software lost the lead it took a week ago, and Taiwan stayed under its steep line.
Price is the only truth. This week it said: the market is waiting, and it is waiting in health care, staples, Switzerland and the bonds. The weekly closes — 80 on the world ex-US, 156.82 on the all-world, 100 on Taiwan, 5.0% on the ten-year, 364.96 on gold — will say what it is waiting for.